Understanding Auto Insurance by Mile Options: A Comprehensive Guide to Usage-Based Coverage
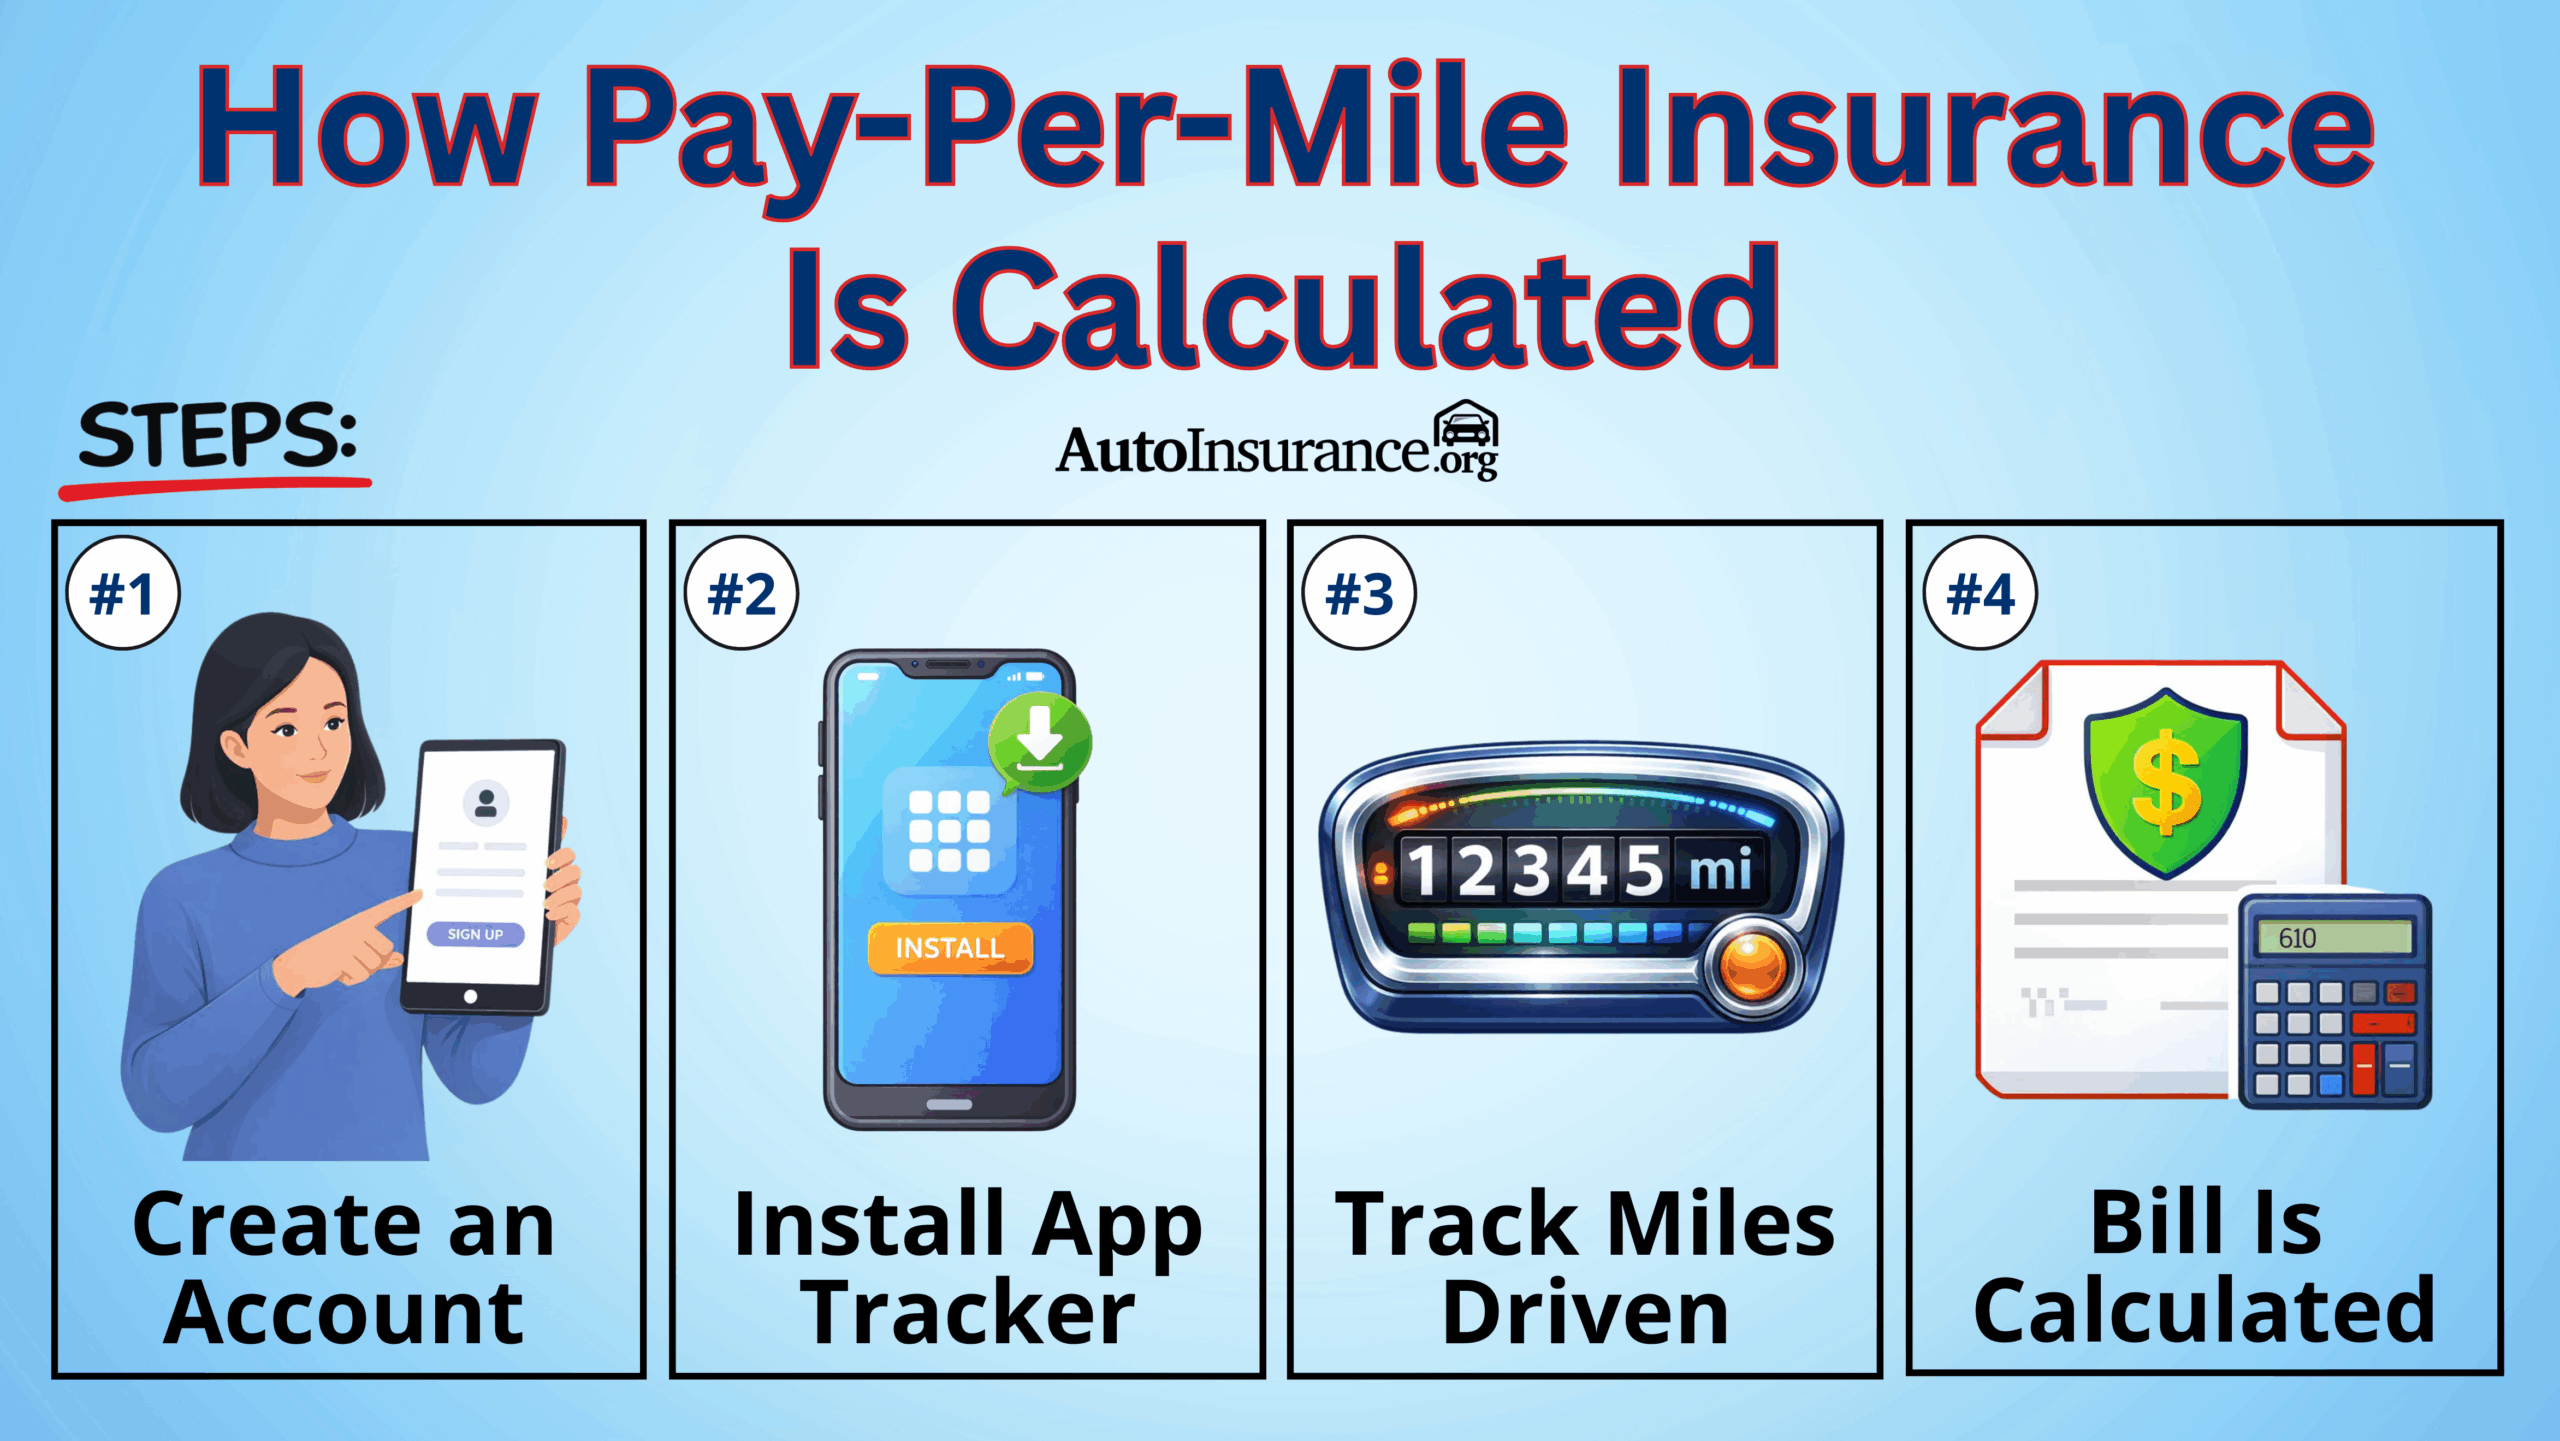
Auto insurance by the mile, often categorized under usage-based insurance (UBI) or pay-per-mile programs, is a model where premiums are structured based on the specific distance a policyholder drives, rather than a flat annual rate. These programs typically consist of a fixed base rate combined with a variable per-mile charge, allowing infrequent drivers to achieve significant premium reductions by limiting their time on the road.
The core premise of auto insurance by the mile is the alignment of risk with actual exposure. Traditional insurance models rely heavily on actuarial tables that categorize drivers into broad demographics, factoring in age, location, and vehicle type to estimate annual mileage. In contrast, pay-per-mile programs use telematics or manual odometer reporting to track the distance traveled, turning a fixed overhead cost into a variable expense that fluctuates monthly based on your driving activity.
How Pay-Per-Mile Insurance Functions
Unlike standard auto insurance, which assumes a fixed annual mileage cap (often 10,000 to 12,000 miles), pay-per-mile insurance operates on a billing cycle that adjusts based on real-time data. When you enroll in such a program, your total premium for a given month is calculated using two distinct components:
- The Base Rate: This is a set monthly fee that maintains your coverage regardless of whether you drive the car at all. It covers risks associated with the vehicle being parked—such as theft, vandalism, or weather-related damage—and contributes to the administrative costs of the policy.
- The Per-Mile Rate: This is a fractional cost applied to every mile recorded. For example, if your rate is $0.06 per mile and you drive 500 miles in a month, your mileage-based charge would be $30.00.
To accurately track this, most carriers utilize a telematics device—a small plug-in module that connects to your vehicle’s OBD-II port—or a mobile application that utilizes GPS data. Some insurers offer "check-in" programs where you may only need to photograph your odometer at set intervals, though automated telematics are increasingly standard as they provide more precise verification for the insurer and reduced friction for the driver.
Eligibility and Prerequisites for Usage-Based Plans
Not every driver or vehicle is compatible with pay-per-mile models. Because these programs rely on data precision, insurers enforce strict requirements regarding the technology used and the types of vehicles enrolled.
- Vehicle Compatibility: Older vehicles that lack an OBD-II port (typically cars manufactured before 1996) may not be eligible for plug-in device programs. However, some insurers allow these drivers to utilize mobile-app-based tracking or manual odometer reporting.
- Driving Habits: These programs are mathematically designed for low-mileage drivers. If you commute long distances for work or frequently take cross-country road trips, you may find that the variable costs of a pay-per-mile plan exceed the cost of a traditional, fixed-premium policy.
- Data Privacy Considerations: Since these programs require the collection of location and movement data, participants must be comfortable with the insurer monitoring their driving habits. While most companies state that this data is used solely for premium calculation and claims adjustment, potential policyholders should review the privacy policy of their chosen carrier to understand the extent of data collection.
Evaluating the Financial Trade-offs
The decision to switch to a per-mile policy should be driven by a cost-benefit analysis. A common point of confusion is the "break-even point"—the threshold at which a traditional policy becomes more economical than a per-mile plan.
Comparative Overview of Insurance Models
| Feature | Traditional Auto Insurance | Pay-Per-Mile Insurance |
|---|---|---|
| Pricing Structure | Flat monthly or annual premium | Base rate + cost per mile |
| Primary Variable | Demographic risk / Annual miles estimate | Actual miles driven |
| Data Collection | Minimal (occasional odometer check) | Constant (GPS or OBD-II telematics) |
| Ideal User | High-mileage commuters, families | Remote workers, retirees, city dwellers |
| Cost Predictability | High (fixed cost) | Low (variable monthly cost) |
This comparison highlights that your choice should align with your lifestyle. If your driving routine is consistent and falls below the 8,000 to 10,000-mile annual mark, you are likely in the target demographic for these programs. Conversely, if your mileage varies wildly from month to month, you may face budget volatility that makes financial planning more difficult.
The Role of Telematics and Data Security
In 2026, the technology underpinning pay-per-mile insurance has reached a high level of sophistication. Telematics devices no longer merely track distance; they can monitor braking patterns, acceleration speeds, and even time-of-day driving trends.
While some pay-per-mile programs focus exclusively on mileage, others are "behavioral," meaning they offer discounts for safe driving habits. It is critical to distinguish between these two:
- Pure Pay-Per-Mile: Focuses on how far you drive. Your rate is not penalized for hard braking or late-night driving.
- Behavior-Based UBI: Focuses on how you drive. These programs can technically lower your premium through safe driving scores, but they can also increase your rate if your driving habits are deemed "risky."
Before signing up, verify if your chosen plan includes "driving behavior" scoring. If you prefer to keep your driving style private while only paying for the distance you cover, seek out "mileage-only" programs that explicitly state they do not rate based on driving speed, cornering, or braking intensity.
Potential Pitfalls and Common Mistakes
Transitioning to a per-mile insurance policy requires a shift in how you manage your monthly expenses. Below are common errors to avoid:
- Ignoring the Base Rate: Some consumers focus solely on the "cents per mile" figure and neglect the base rate. A plan with a low per-mile cost but a high base rate might still be more expensive than a traditional policy. Always calculate the total monthly estimate based on your average usage.
- Failure to Report Odometer Readings: For programs that require manual reporting, missing a reporting deadline can result in the insurer defaulting to a maximum mileage assumption, which often leads to an inflated "estimated" bill.
- Road Trip Blindness: Remember that a long-distance vacation can significantly spike your premium for that specific month. While the average annual cost might still be lower, you must be prepared for that one-time financial impact during heavy travel months.
- Device Tampering: Removing an OBD-II device to avoid tracking is a violation of most insurance contracts. Modern telematics devices often have sensors to detect unplugging; tampering can lead to policy cancellation or the application of the maximum possible premium rate.
Frequently Asked Questions
Does pay-per-mile insurance cover me if I am not driving? Yes. Even though you are paying based on mileage, the policy remains a full-coverage insurance contract. It provides protection while your vehicle is parked at home, parked at work, or during periods where you do not drive for weeks at a time. The base rate you pay ensures you remain covered against theft, fire, and other non-driving risks.
Can multiple drivers be covered under a pay-per-mile policy? Yes, but the calculation varies. Most insurers apply the per-mile rate to the total mileage recorded on the specific vehicle regardless of who is behind the wheel. If you have multiple vehicles, some programs allow you to manage them under a single account, but you will typically pay a base rate for each car insured.
Is my location tracked at all times? It depends on the provider. Most modern pay-per-mile systems use GPS to accurately determine your mileage. While some providers store this location history, many state in their privacy agreements that they only store the total distance traveled and purge granular location coordinates after the billing cycle is processed. Always request a summary of the data retention policy before enrollment.
What happens if I sell my car or buy a new one? You must notify your insurer immediately. Since the device is linked to the vehicle, selling the car requires you to deactivate the telematics device and return it if required. When buying a new car, you will need to re-register the VIN and potentially install a new device, as the mileage calculation is unique to the vehicle's hardware.
Are there limits to how many miles I can drive? There is generally no "cap" on your mileage, but most programs include a daily maximum for billing purposes. For example, many insurers will cap the daily billable miles at 150 or 250 miles. This prevents a single long road trip from costing a disproportionate amount in a single day, essentially offering a volume discount for very long drives.
Next Steps for Choosing Your Plan
If you have determined that your current driving habits align with the pay-per-mile model, the next step is to perform a side-by-side comparison. Do not rely on quotes provided by search engines alone. Contact your existing insurance provider to see if they offer a usage-based or pay-per-mile subsidiary. Often, staying within the same insurance ecosystem can make the transition smoother, as they may already have your claims history and demographic data.
When requesting a quote, provide an accurate estimate of your annual mileage based on your previous year's registration or service records. Ask the agent for the "maximum monthly cost" scenario so you can evaluate how a high-mileage month would impact your budget. Finally, prioritize plans that offer clear, transparent monthly statements, allowing you to audit your mileage and verify the accuracy of your charges against your own records.
Image Gallery
Select an image to open it in a new tab.
Omar Farooq
EdTech Innovation and Virtual Pedagogy Journalist
