Navigating Workers Compensation States in the United States: Requirements, Frameworks, and Compliance
Workers' compensation across the United States operates as a state-regulated insurance system designed to provide medical benefits, wage replacement, and rehabilitation services to employees who suffer work-related injuries or illnesses. Understanding how these frameworks function requires examining distinct state-by-state mandates, variations in coverage thresholds, administrative structures, and the complex interplay between mandatory compliance and employer obligations.
Understanding the Landscape of Workers Compensation States in the US
The United States does not maintain a single, federal workers' compensation system for standard private-sector employment. Instead, the legal landscape is defined by fifty distinct state jurisdictions, alongside the District of Columbia and federal territories. Each jurisdiction establishes its own statutory framework, governing everything from which employers must carry coverage to the specific payout formulas applied when an employee is injured.
This decentralized approach means that an employer operating across multiple state lines must navigate entirely different regulatory environments. A business compliant with workers' compensation laws in Texas may find its coverage completely inadequate or non-compliant if it expands operations into New York or California. Consequently, understanding the structural differences among workers compensation states in the US is a fundamental operational necessity for risk management, human resources administration, and legal compliance.
- State-Specific Statutes: Every state enacts its own workers' compensation act, defining the exclusive remedy doctrine, benefit caps, and adjudication processes.
- Regulatory Oversight: State departments of labor, industrial commissions, or specialized workers' compensation boards enforce mandates and resolve disputes.
- Insurance Mechanics: Employers typically fulfill mandates through private insurance carriers, state-operated funds, or approved self-insurance programs.
Mandatory Versus Elective Coverage Models
One of the most critical distinctions among workers compensation states in the US is whether carrying insurance is compulsory for all employers or elective. While the vast majority of states enforce mandatory coverage, a few maintain elective frameworks that alter how legal liability is managed.
Compulsory States
In compulsory states, employers must secure workers' compensation insurance before hiring employees. Failing to do so carries severe legal, financial, and criminal penalties. In these jurisdictions, the law explicitly requires that nearly all businesses with one or more employees (though numerical thresholds vary) provide this safety net.
Elective States
In elective states, employers are not legally compelled to purchase workers' compensation insurance. However, choosing not to participate strips the employer of common-law defenses—such as contributory negligence, assumption of risk, and the negligence of a fellow employee—should an injured worker file a civil lawsuit for negligence. Because losing these defenses makes employers exceptionally vulnerable to massive jury verdicts, the vast majority of businesses in elective states still choose to purchase coverage.

Employer Thresholds and Coverage Exemptions
Even within compulsory systems, states establish distinct numerical and occupational thresholds that dictate who must be insured. These variations significantly impact small businesses, contractors, and specialized industries.
Employee Count Thresholds
Most states require coverage as soon as a business hires its first employee, whether full-time or part-time. However, several states apply minimum employee counts:
- Zero to One Employee: The majority of states mandate coverage starting with the very first worker.
- Three to Five Employees: Some states exempt very small businesses until their total employee headcount reaches three, four, or five. In these states, corporate officers or LLC members may or may not count toward this total depending on local statutes.
Occupational Exemptions
Certain classes of workers are frequently excluded from standard state workers' compensation acts, though they may be covered under federal statutes or specialized state programs:
- Independent Contractors: True independent contractors are generally excluded, though misclassification is a major regulatory enforcement priority.
- Agricultural and Domestic Workers: Many states historically exempted farmworkers and domestic household employees, though legislative trends increasingly narrow these exemptions.
- Maritime and Railway Workers: These workers typically fall under federal jurisdictions, such as the Jones Act or the Federal Employers' Liability Act (FELA), rather than state workers' compensation systems.
State-Funded Models: Monopolistic Versus Competitive Markets
The mechanism through which employers acquire workers' compensation insurance varies significantly across the country. States generally fall into one of two operational categories: monopolistic state funds or competitive open markets.
| Fund Type | Operational Structure | Key Characteristics | Examples of States |
|---|---|---|---|
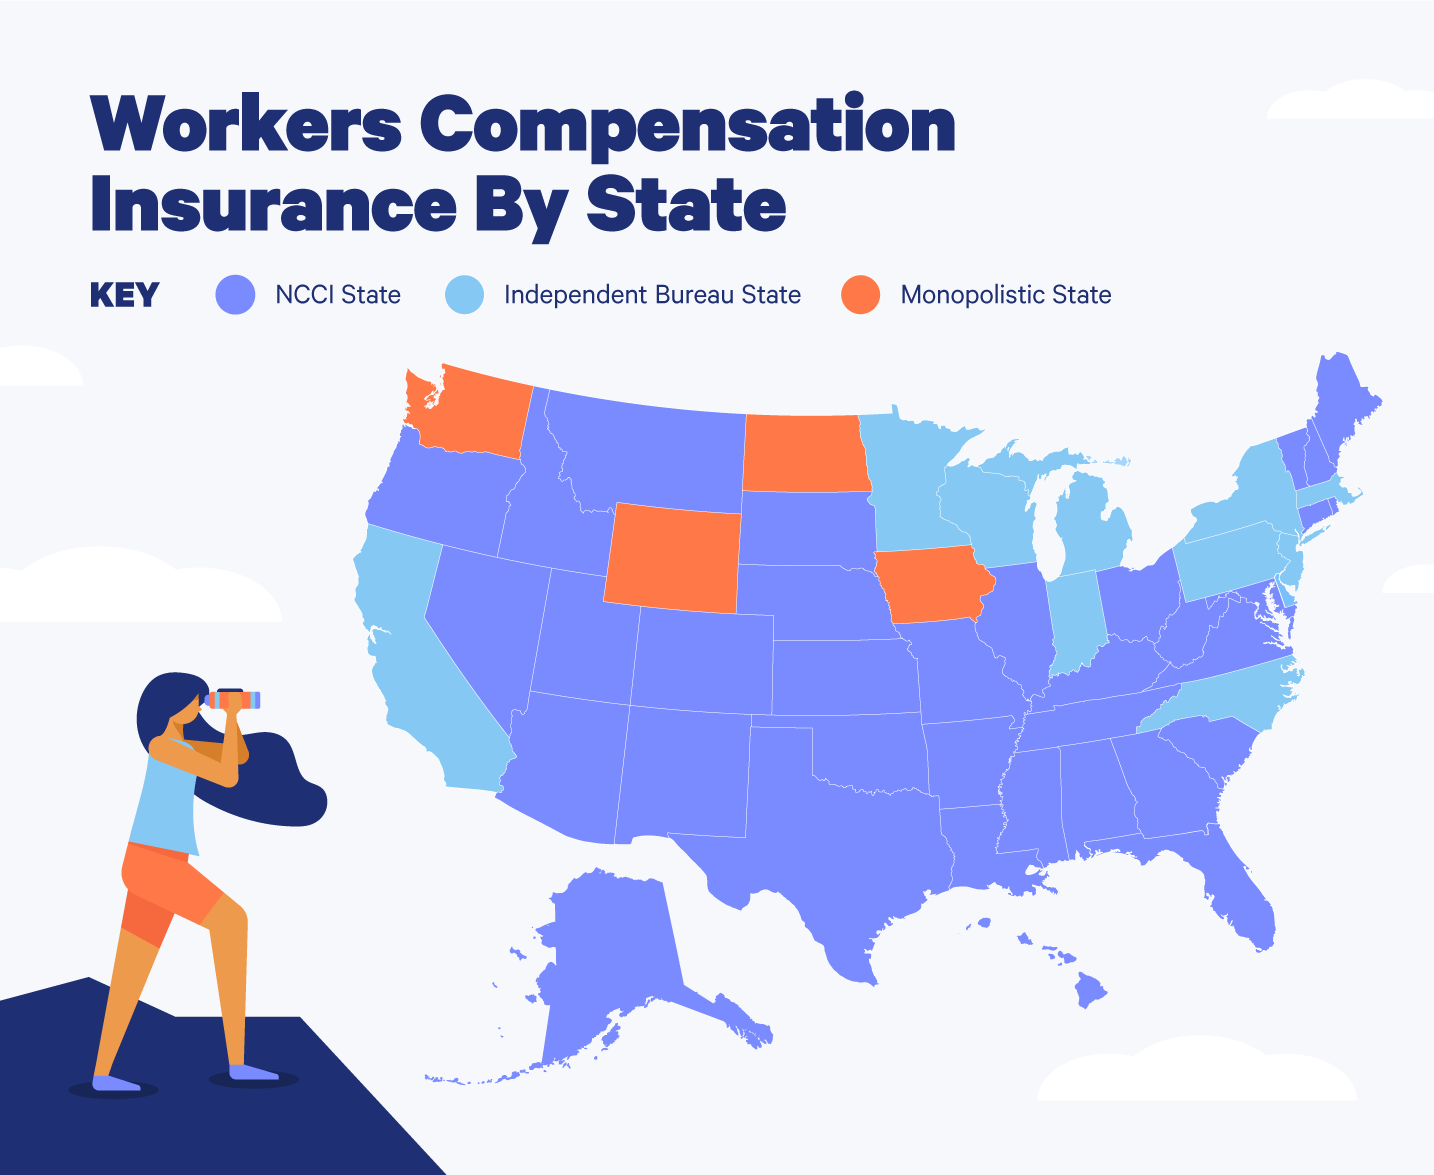
| Monopolistic States | State-run exclusive monopoly | Employers must purchase workers' compensation insurance directly from a state-operated fund. Private insurance carriers cannot write standard workers' comp policies in these states. | Ohio, Washington, North Dakota, Wyoming |
| Competitive States | Open market with private carriers | Employers purchase coverage from licensed private insurance companies, industry groups, or specialized group self-insurance pools. | California, New York, Texas, Florida |
In monopolistic states, employers must navigate state-specific administrative processes for underwriting, premium calculation, and claims management. In competitive states, private insurers compete on pricing, risk engineering services, and claims handling, though rates are often influenced by advisory organizations such as the National Council on Compensation Insurance (NCCI).
The Role of Assigned Risk Plans and Pools
What happens when an employer operates in a competitive state, but private insurance carriers refuse to write a policy due to a high-risk industry profile, poor safety history, or new business status? To address this, workers compensation states in the US maintain mechanisms known as assigned risk plans or residual markets.
When an employer cannot secure coverage in the voluntary open market, they can apply through the state's assigned risk pool (often managed by the NCCI or a state-specific equivalent). The plan assigns the high-risk employer to a participating private insurance carrier, which must issue a policy. While this guarantees access to mandatory coverage, premiums in the assigned risk pool are frequently higher due to the elevated risk profile of the participating employers.
Benefits Provided Under State Frameworks
Regardless of the specific state, workers' compensation systems generally provide four primary categories of benefits to injured workers. However, the duration, calculation formulas, and caps for these benefits differ widely from one jurisdiction to another.
- Work-Related Injury or Illness
- Medical Benefits (Treatment, hospitalization, pharmaceuticals)
- Temporary Disability (Wage replacement during recovery)
- Permanent Disability (Compensating for lasting impairment)
- Vocational Rehabilitation (Retraining and job placement)
Medical Benefits
State laws mandate that employers cover all reasonable and necessary medical treatment required to cure or relieve the effects of a work-related injury. This includes doctor visits, surgeries, physical therapy, diagnostic testing, and prescription medications. In many states, employers or their insurers have the right to direct the injured worker to specific medical provider networks, though employee rights regarding second opinions vary.
Temporary Disability Benefits
When an injury prevents an employee from working during the recovery period, temporary total disability (TTD) or temporary partial disability (TPD) benefits replace a portion of lost wages. Most states calculate this as a percentage of the worker's average weekly wage (typically around two-thirds), subject to state-mandated minimum and maximum caps.
Permanent Disability Benefits
If an employee suffers a lasting impairment that does not fully resolve after maximum medical improvement is reached, permanent partial disability (PPD) or permanent total disability (PTD) benefits are awarded. States use varying rating schedules, medical guidelines, and wage-loss formulas to determine the financial valuation of permanent impairments.
Vocational Rehabilitation
For workers who cannot return to their previous occupation due to lasting physical restrictions, many states provide vocational rehabilitation services. This can include job retraining, educational assistance, resume building, and placement services to help the worker re-enter the workforce in a new capacity.
Compliance, Penalties, and Enforcement
Enforcing workers' compensation mandates is a high-priority function for state regulatory agencies. Because uninsured employers shift the financial and medical burden of workplace injuries onto public health systems and taxpayers, penalties for non-compliance are severe.
- Stop-Work Orders: State regulators can issue immediate stop-work orders, forcing a business to halt all operations until proof of valid coverage is established.
- Financial Fines: Daily or lump-sum fines accrue rapidly for every day an employer operates without required insurance coverage.
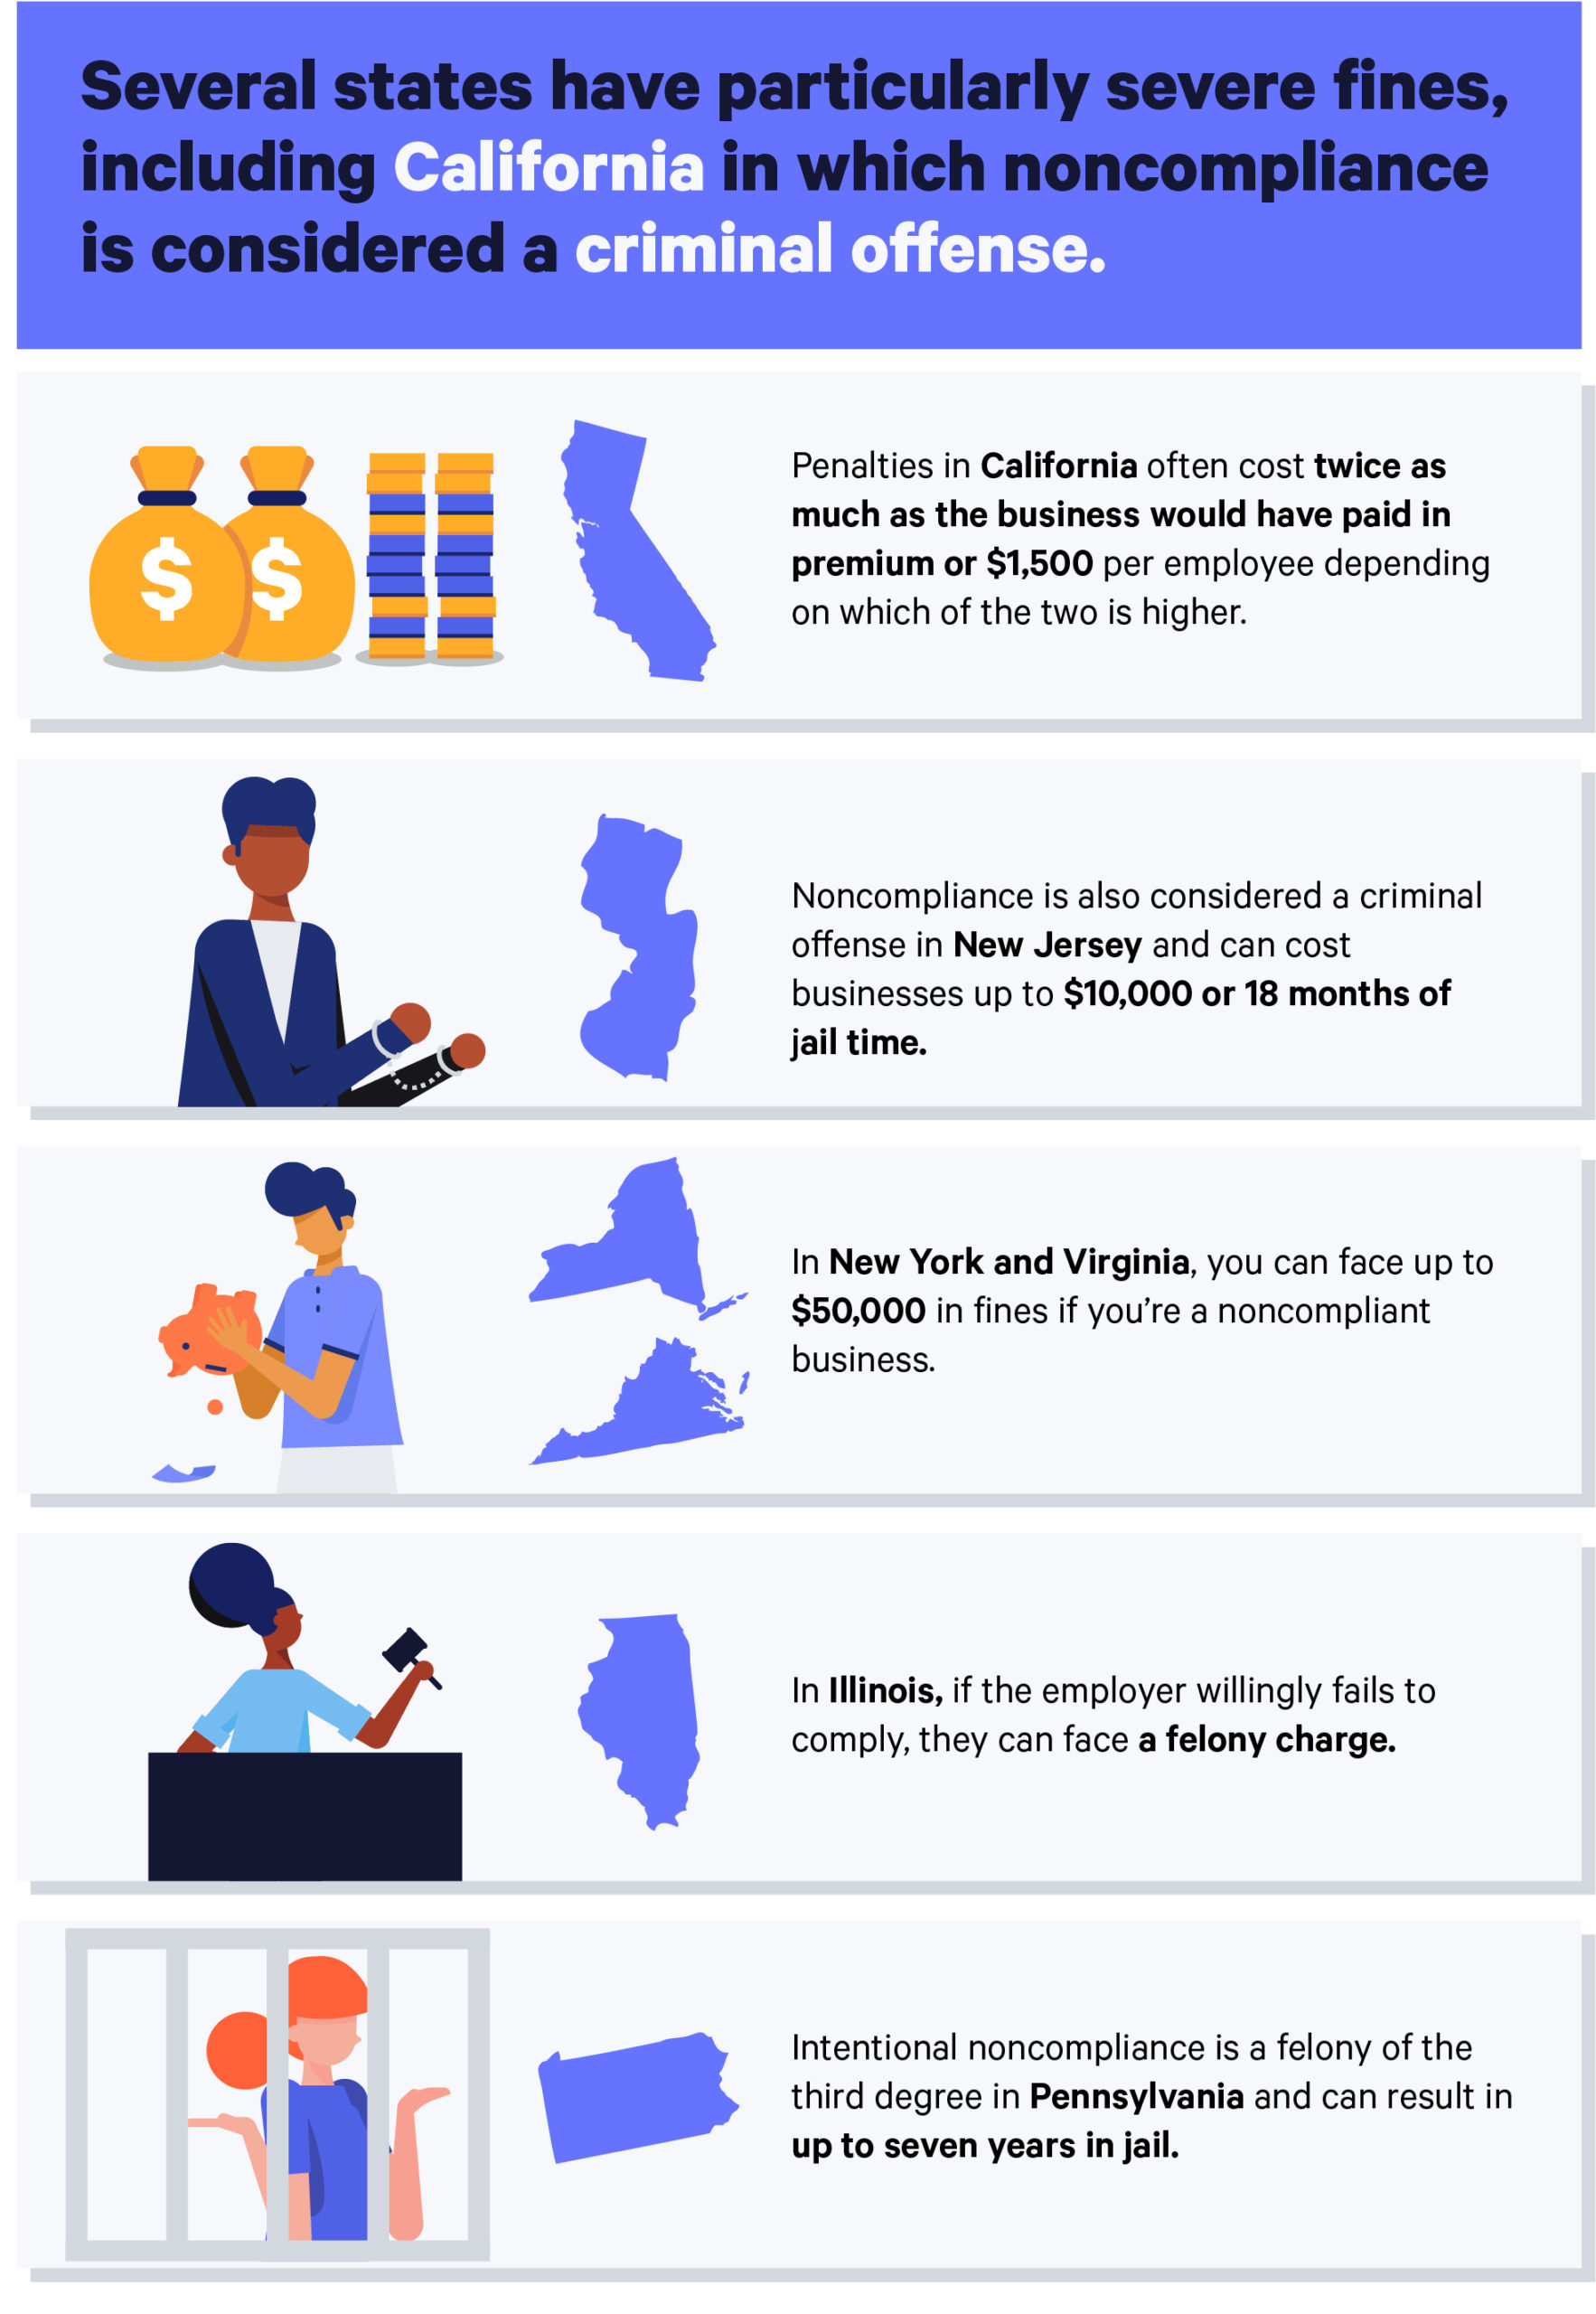
- Criminal Liability: In many jurisdictions, intentionally failing to carry workers' compensation insurance is classified as a felony, carrying potential prison sentences for corporate officers and business owners.
- Civil Exposure: Operating without coverage strips the employer of statutory immunity (the exclusive remedy doctrine), exposing them to direct civil lawsuits from injured workers where standard tort defenses are unavailable.
Frequently Asked Questions
Can an employer opt out of workers' compensation in Texas?
Yes. Texas is unique among workers compensation states in the US because it is the only state where private-sector employers are generally permitted to opt out of the system entirely. Employers who choose not to carry workers' compensation must notify both their employees and the state, and they lose common-law liability defenses if an injured worker sues them for negligence.
How do multi-state employers handle workers' compensation coverage?
Multi-state employers typically utilize "other states insurance" endorsements attached to their standard workers' compensation policy. This endorsement automatically extends coverage to employees who may travel or work temporarily in other states, provided those states are listed on the policy information page. If a business establishes permanent operations or hires permanent residents in a new state, a dedicated policy or specific state endorsement is usually required.
Are independent contractors required to have workers' compensation?
True independent contractors are generally responsible for their own insurance and are not covered under a hiring company's workers' compensation policy. However, state regulators strictly audit worker classifications. If a regulatory board or court determines that an "independent contractor" is actually a statutory employee based on the degree of control exerted by the hiring company, the employer can be assessed severe back premiums and penalties.
What is the exclusive remedy doctrine?
The exclusive remedy doctrine is a foundational legal compromise inherent to workers' compensation systems. In exchange for receiving guaranteed medical and wage benefits without needing to prove employer negligence, the injured worker gives up the right to sue the employer in civil court for standard workplace injuries. Exceptions generally apply only in cases of intentional torts or gross misconduct by the employer.
How are workers' compensation insurance premiums calculated?
Premiums are calculated using a formula based on payroll size, the specific classification of the business operations (which determines the inherent risk level), and the employer's Experience Modification Rate (EMR). The EMR compares an employer's actual claims history against the expected losses for similar businesses in the same industry; companies with safer records enjoy lower EMRs and reduced premiums.
Practical Next Steps for Employers
For business owners and operational managers navigating workers compensation states in the US, establishing proactive compliance protocols is essential. Begin by auditing current workforce classifications to ensure all workers are accurately categorized as employees or independent contractors. Next, verify that existing insurance policies cover all operational states where personnel perform services, paying close attention to remote workers residing across state lines. Finally, consult with licensed commercial insurance brokers or labor law counsel specializing in multi-state compliance to prevent costly coverage gaps and regulatory penalties.
Image Gallery
Select an image to open it in a new tab.




Celine Dubois
Contemporary Living and Global Arts Columnist
