A premium basis for workers' compensation is the fundamental monetary figure—typically employee payroll—used by insurance carriers to calculate the cost of a policy. Insurers multiply this base metric by an industry classification rate and adjust it via an experience modifier to determine the final premium an employer must pay.
Understanding the Core Concept of Workers' Compensation Premium Bases
Navigating the financial architecture of commercial insurance requires understanding how policies are priced. For business owners, workers' compensation is a mandatory safeguard that provides medical benefits and wage replacement to employees injured on the job. However, unlike general liability or commercial auto insurance, which might use gross sales or vehicle counts as rating metrics, workers' compensation relies primarily on workplace remuneration.
The premium basis serves as the denominator or multiplier against which insurance rates are applied. In standard actuarial practice, risk correlates closely with human capital exposure. More payroll generally implies more employee hours worked, higher exposure to occupational hazards, and a statistically greater likelihood of workplace incidents. Consequently, payroll functions as the most reliable, standardized proxy for risk exposure across diverse industries.
Beyond basic payroll, the premium basis can incorporate other forms of compensation, such as commissions, bonuses, and the value of certain perks or room and board. Insurance rating bureaus, such as the National Council on Compensation Insurance (NCCI) in the United States, establish strict guidelines regarding what constitutes payroll for premium calculation purposes. Understanding these parameters helps organizations avoid unexpected audit adjustments and properly budget for annual insurance expenses.
Components That Constitute a Workers' Compensation Premium Basis
When an insurance auditor evaluates a company's records at the end of a policy term, they examine specific ledgers to compile the total premium basis. While standard W-2 wages form the bulk of this calculation, the definition of remuneration extends far beyond base salaries.
To ensure accurate premium computations, employers must understand which types of compensation are included and excluded by statutory guidelines and rating bureau rules. Misclassifying these funds can lead to substantial financial penalties or underreported exposures during mandatory year-end audits.
Included Remuneration Elements
The premium basis encompasses nearly all forms of compensation paid to employees for services rendered. When calculating total payroll for workers' compensation, insurance regulations generally require the inclusion of the following items:
- Gross Wages and Salaries: All straight-time pay, hourly wages, and salaried earnings before payroll deductions.
- Overtime Pay: While overtime hours increase gross pay, standard rules in many jurisdictions require the inclusion of the straight-time portion of overtime, though some states include the total overtime premium. (This varies by state and rating bureau jurisdiction, requiring careful verification).
- Commissions and Piecework: Earnings paid to sales representatives based on performance or to manufacturing workers based on units produced.
- Bonuses and Incentives: Production bonuses, holiday bonuses, profit-sharing distributions tied to performance, and attendance awards.
- Paid Leave: Wages paid for vacation time, sick leave, and holiday pay while the employee remains on active status.
- Housing and Allowances: The market value of housing, rent, or food provided to employees as part of their compensation package.
Excluded Remuneration Elements
Conversely, certain disbursements are explicitly omitted from the premium basis because they do not represent active occupational exposure or direct wages for labor. Common exclusions include:
- Tips and Gratuities: In many states, tips received directly from customers are excluded from payroll calculations, though employers must report them for tax purposes.
- Severance Pay: Payments made upon termination that do not compensate for ongoing services rendered.
- Employer Contributions to Employee Benefits: Payments made by the employer for group health insurance, retirement plans (such as 401(k) matches), and formal pension funds.
- Third-Party Sick Pay: Payments made by a third-party insurer for short-term or long-term disability.
- Tips and Shareholder Distributions: True corporate dividends paid to stock-owning executives, distinct from officer salaries.
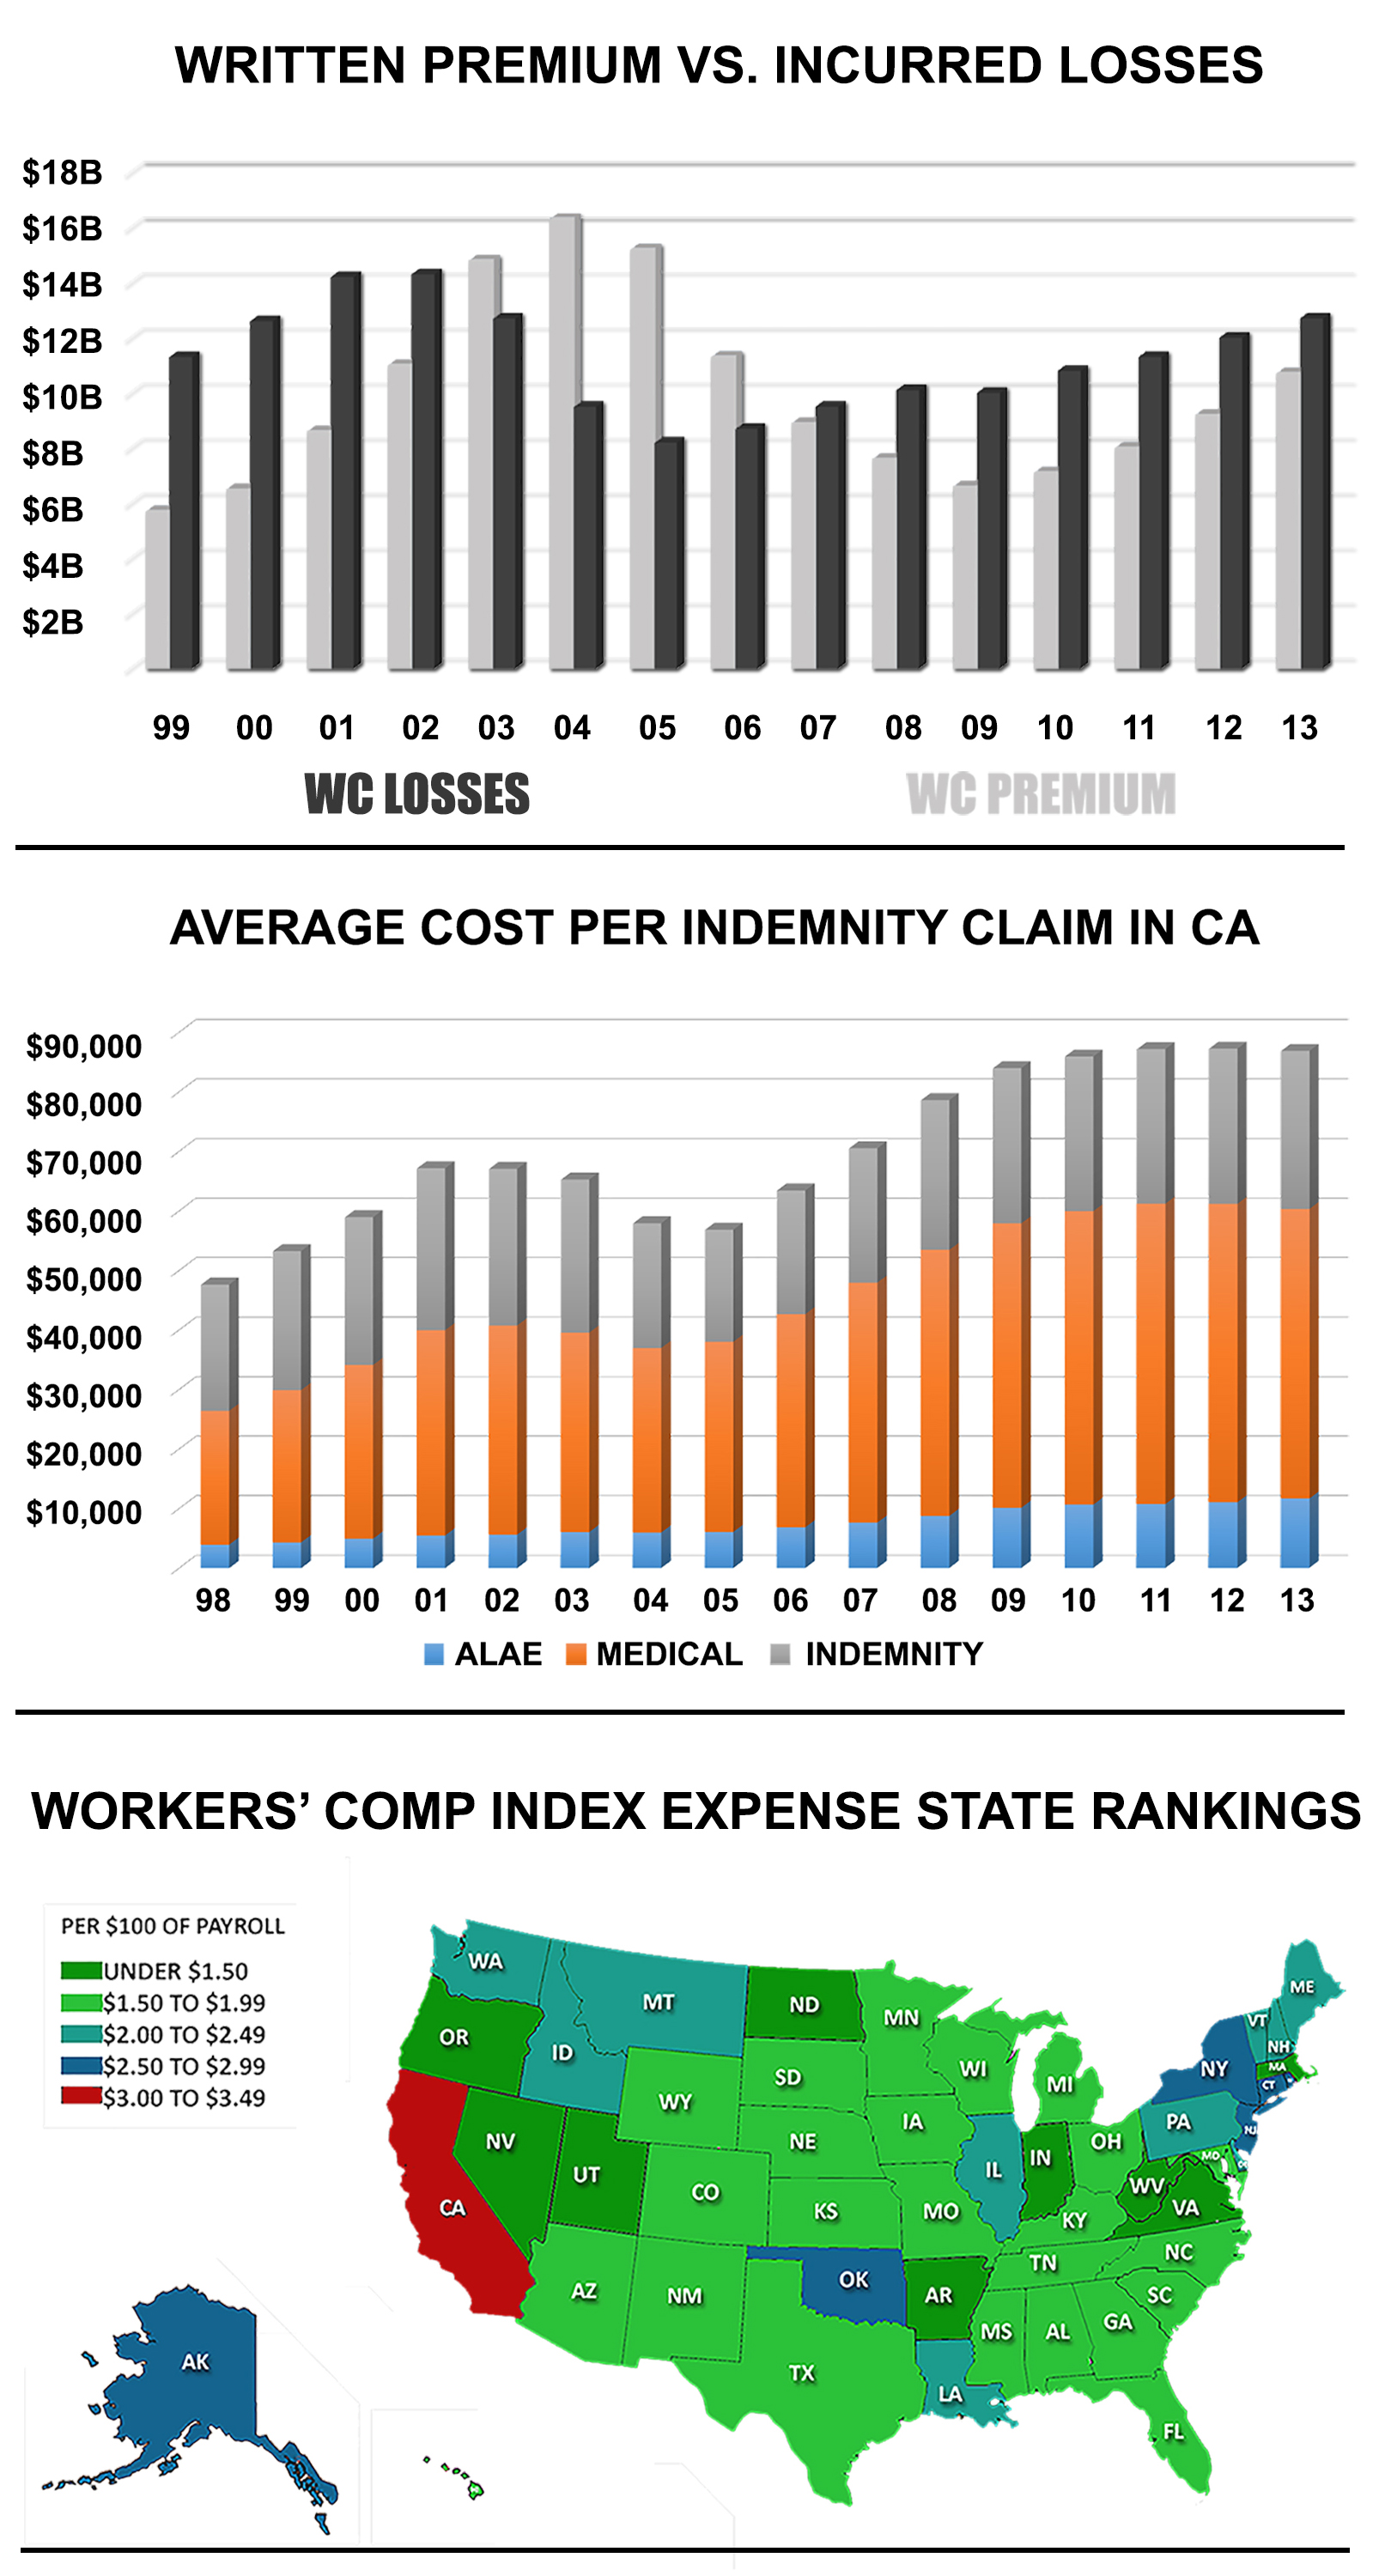
How the Premium Basis Directs the Calculation Formula
The premium basis is the central engine of the final premium calculation formula. Without an accurate determination of this financial exposure, the subsequent mathematical steps cannot yield a correct policy cost. Insurance underwriters utilize a standardized formula that scales risk according to payroll size, industry hazard, and company safety history.
| Formula Step | Variable Name | Description |
|---|---|---|
| 1 | Payroll (Premium Basis) | The total qualifying remuneration paid to employees within specific classification codes. |
| 2 | Classification Rate | A rate per $100 of payroll assigned by the rating bureau based on the specific operational risk of the job duties. |
| 3 | Manual Premium | The baseline cost calculated by multiplying the payroll by the classification rate (Payroll ÷ 100 × Rate). |
| 4 | Experience Modification Rate (Mod) | A multiplier derived from the company's historical claims frequency and severity compared to industry averages. |
| 5 | Premium Adjustments | Application of schedule ratings, premium discounts for larger policies, and expense constants. |
As demonstrated in the table, the process begins directly with the premium basis. If an organization has $1,000,000 in clerical payroll and a rate of $0.25 per $100, the manual premium calculation is straightforward: $($1,000,000 / 100) \times 0.25 = $2,500$. This manual premium is then adjusted by the experience modifier to arrive at the final payable premium.
Special Rules for Corporate Officers, Sole Proprietors, and Partners
Applying a premium basis becomes more complex when evaluating business owners, corporate officers, partners, and sole proprietors. Unlike standard W-2 employees, executives and owners often have variable compensation structures, dividend income, or statutory exemptions that affect how their exposure is measured.
Corporate Officers and LLC Members
In many jurisdictions, corporate officers and members of limited liability companies (LLCs) are automatically included in workers' compensation coverage. To prevent owners from underreporting their income to lower premiums—or conversely, claiming inflated wages to manipulate disability benefit payouts—rating bureaus establish strict maximum and minimum payroll inclusion caps for officers.
For instance, an NCCI guideline often sets a statewide average weekly wage cap and floor for officers. Even if an officer takes no salary or a multi-million-dollar distribution, the insurer may calculate their premium basis using a mandated statutory payroll amount unless they file a formal, state-approved exemption form.
Independent Contractors and Subcontractors
A frequent point of confusion during premium audits involves independent contractors. If a business hires subcontractors without verifying their own workers' compensation insurance certificates, state laws and insurance rules often dictate that the hiring company must treat those subcontractors as direct employees. In these cases, the payments made to uninsured subcontractors are added directly into the hiring company's premium basis, often resulting in massive, unexpected audit bills. Maintaining thorough compliance records regarding subcontractor insurance is essential to protecting the premium basis from artificial inflation.
The Role of Payroll Audits in Verifying the Premium Basis
Because workers' compensation policies are priced at the beginning of the term using estimated payroll projections, the initial premium is merely a provisional deposit. The true, final cost cannot be determined until the policy period concludes and a formal payroll audit is performed.
During a premium audit, the insurance carrier's auditor reviews actual financial records to verify the figures used for the premium basis. Sources examined during this process typically include:
- Federal and state quarterly tax returns (such as IRS Form 941 and state unemployment insurance reports).
- Detailed general ledgers showing payroll disbursements by account code.
- Journals documenting payments made to subcontractors and casual labor.
- Certificates of insurance for any third-party vendors utilized during the term.
If the audit reveals that the actual payroll was higher than estimated, the insurer issues a billing statement for additional premium. If actual payroll was lower, the employer receives a refund or credit. Ensuring that accounting software tracks payroll by exact workers' compensation classification codes throughout the year prevents friction and discrepancies during the audit process.
Frequently Asked Questions
What is the difference between estimated payroll and audited payroll?
Estimated payroll is the projected remuneration a business provides to its insurance carrier at the beginning of the policy year to calculate monthly or upfront deposit premiums. Audited payroll is the verified, actual remuneration paid out during the policy term, determined via a post-term financial review. The final premium is adjusted based on the audited figures.
Are bonuses always included in the workers' compensation premium basis?
Most performance-based bonuses, holiday bonuses, and production incentives are included in the premium basis. However, certain gifts or non-cash bonuses may be excluded depending on state-specific statutory guidelines and the exact nature of the compensation plan. Employers should consult their broker or state rating bureau rules for local compliance.
How do piecework and commissions affect the premium basis?
Piecework wages and sales commissions are fully included in the premium basis. Because these payments compensate workers for active labor and exposure to occupational duties, insurers treat them identically to standard hourly wages or fixed salaries during premium calculations and audits.
Can corporate officers exclude themselves from the premium basis?
In many states and business structures, corporate officers, LLC members, and sole proprietors can elect to exempt themselves from workers' compensation coverage by filing specific forms with the state insurance commissioner or the carrier. If a valid exemption is in place, the individual's payroll is entirely removed from the premium basis, meaning they sacrifice personal coverage in exchange for lower policy costs.
Why do uninsured subcontractors increase my premium basis?
If an organization hires a subcontractor who does not carry an independent workers' compensation policy, statutory regulations in most jurisdictions deem those workers to be employees of the hiring firm. Consequently, the total payments (labor costs) made to that subcontractor are folded directly into the hiring company's premium basis as uninsured payroll, significantly increasing the final insurance premium.
Next Steps for Managing Your Premium Basis
To maintain financial control over your commercial insurance expenses, proactive management of your premium basis is essential. Begin by auditing internal payroll systems to ensure wages are correctly mapped to appropriate job classification codes rather than lumped into broad categories. Review your experience modification worksheet annually to verify that payroll figures reported to rating bureaus align precisely with your tax documents. Finally, establish a strict compliance protocol for collecting and verifying certificates of insurance from every subcontractor or independent vendor before they step foot on a job site. By maintaining meticulous records, you insulate your business from costly audit surprises and ensure your workers' compensation costs accurately reflect your operational footprint.
Image Gallery
Select an image to open it in a new tab.


Celine Dubois
Contemporary Living and Global Arts Columnist
