Why Corporate Bonds Are Taxable: A Comprehensive Guide to Taxation and Yields in 2026

Corporate bonds are fully taxable at the federal, state, and local levels. The interest income generated from these securities is treated as ordinary income, taxed at your marginal tax rate, while any profit realized from selling a bond for more than its purchase price is subject to capital gains taxation.
The Fundamental Tax Status of Corporate Debt
When an investor purchases a corporate bond, they are essentially lending money to a private corporation in exchange for periodic interest payments (coupons) and the return of the bond's face value at maturity. Because these entities are private, for-profit organizations, the internal revenue services of most jurisdictions—including the United States—view the income generated from these loans as standard earnings.
Unlike municipal bonds, which are often issued to fund public works and receive tax-exempt status to encourage investment in infrastructure, corporate bonds offer no such federal incentive. In 2026, the tax landscape remains a critical factor for fixed-income investors, as the expiration of several previous tax provisions has shifted the effective "take-home" yield for those in higher income brackets.
Interest Income vs. Capital Gains
Taxation on corporate bonds occurs in two distinct ways: through interest payments and through price appreciation.
- Interest Income: The coupon payments you receive, typically twice a year, are classified as ordinary income. This means they are added to your wages, tips, and other earnings for the year and taxed according to your highest applicable tax bracket. If you are in the 32% or 35% tax bracket in 2026, a significant portion of your bond yield is redirected to the IRS.
- Capital Gains: If you buy a corporate bond on the secondary market for $950 and sell it later for $980, the $30 profit is a capital gain. If you held the bond for more than one year, it is taxed at the long-term capital gains rate (0%, 15%, or 20% depending on income). If held for less than a year, it is taxed at ordinary income rates.
Federal, State, and Local Taxation in 2026
The "triple threat" of taxation applies to most corporate bonds. This sets them apart from U.S. Treasury securities, which are taxable at the federal level but exempt from state and local taxes.
Federal Income Tax
Federal taxation is the largest hurdle for bondholders. For the 2026 tax year, investors must account for the standard income tax brackets. Because bond interest does not qualify for the lower "qualified dividend" rates that some stocks enjoy, the tax drag can be substantial. For example, an investor earning a 6% coupon on a high-yield corporate bond might only see a 4% net return after federal taxes are applied.
State and Local Income Tax
Almost all states that levy an income tax require investors to report interest from corporate bonds. In high-tax states like California, New York, or Oregon, the combined state and local tax can take another 5% to 13% of the interest earned. This makes the taxable-equivalent yield an essential calculation for anyone comparing corporate bonds to municipal bonds issued within their home state.
The Complexity of Original Issue Discount (OID) and Market Discount
Not all corporate bonds are issued at their face (par) value. Some are issued at a discount, which introduces the concept of Original Issue Discount (OID).
Understanding OID Taxation
If a corporation issues a bond at a price significantly below its par value (common with zero-coupon bonds), the difference between the issue price and the par value is considered interest. However, you do not receive this interest in cash until the bond matures. Under IRS rules, you must report a portion of this "phantom income" every year as it accrues. This can create a cash flow challenge, as you owe taxes on money you have not yet physically received.
Market Discount Rules
When you buy a bond on the secondary market for less than its original issue price, you are buying at a market discount. When that bond is eventually sold or redeemed, the portion of the gain attributable to the market discount is generally taxed as ordinary income rather than capital gains. This rule prevents investors from converting ordinary interest income into lower-taxed capital gains simply by purchasing discounted bonds.
Comparing Bond Tax Treatments
To understand the impact of taxes on your portfolio, it is helpful to compare corporate bonds against other common fixed-income instruments.
| Bond Type | Federal Tax | State/Local Tax | Primary Risk | Typical Relative Yield |
|---|---|---|---|---|
| Corporate Bond | Taxable | Taxable | Credit/Default Risk | Highest |
| U.S. Treasury | Taxable | Exempt | Inflation Risk | Lowest (Risk-Free) |
| Municipal Bond | Exempt* | Exempt* | Project/Credit Risk | Moderate |
| Zero-Coupon Corp | Taxable (Accrued) | Taxable (Accrued) | Reinvestment Risk | High |
*Note: Municipal bond interest is generally exempt from federal tax and exempt from state tax if the investor resides in the issuing state. Some "Private Activity" municipal bonds may be subject to the Alternative Minimum Tax (AMT).
Taxable-Equivalent Yield: A Critical 2026 Calculation
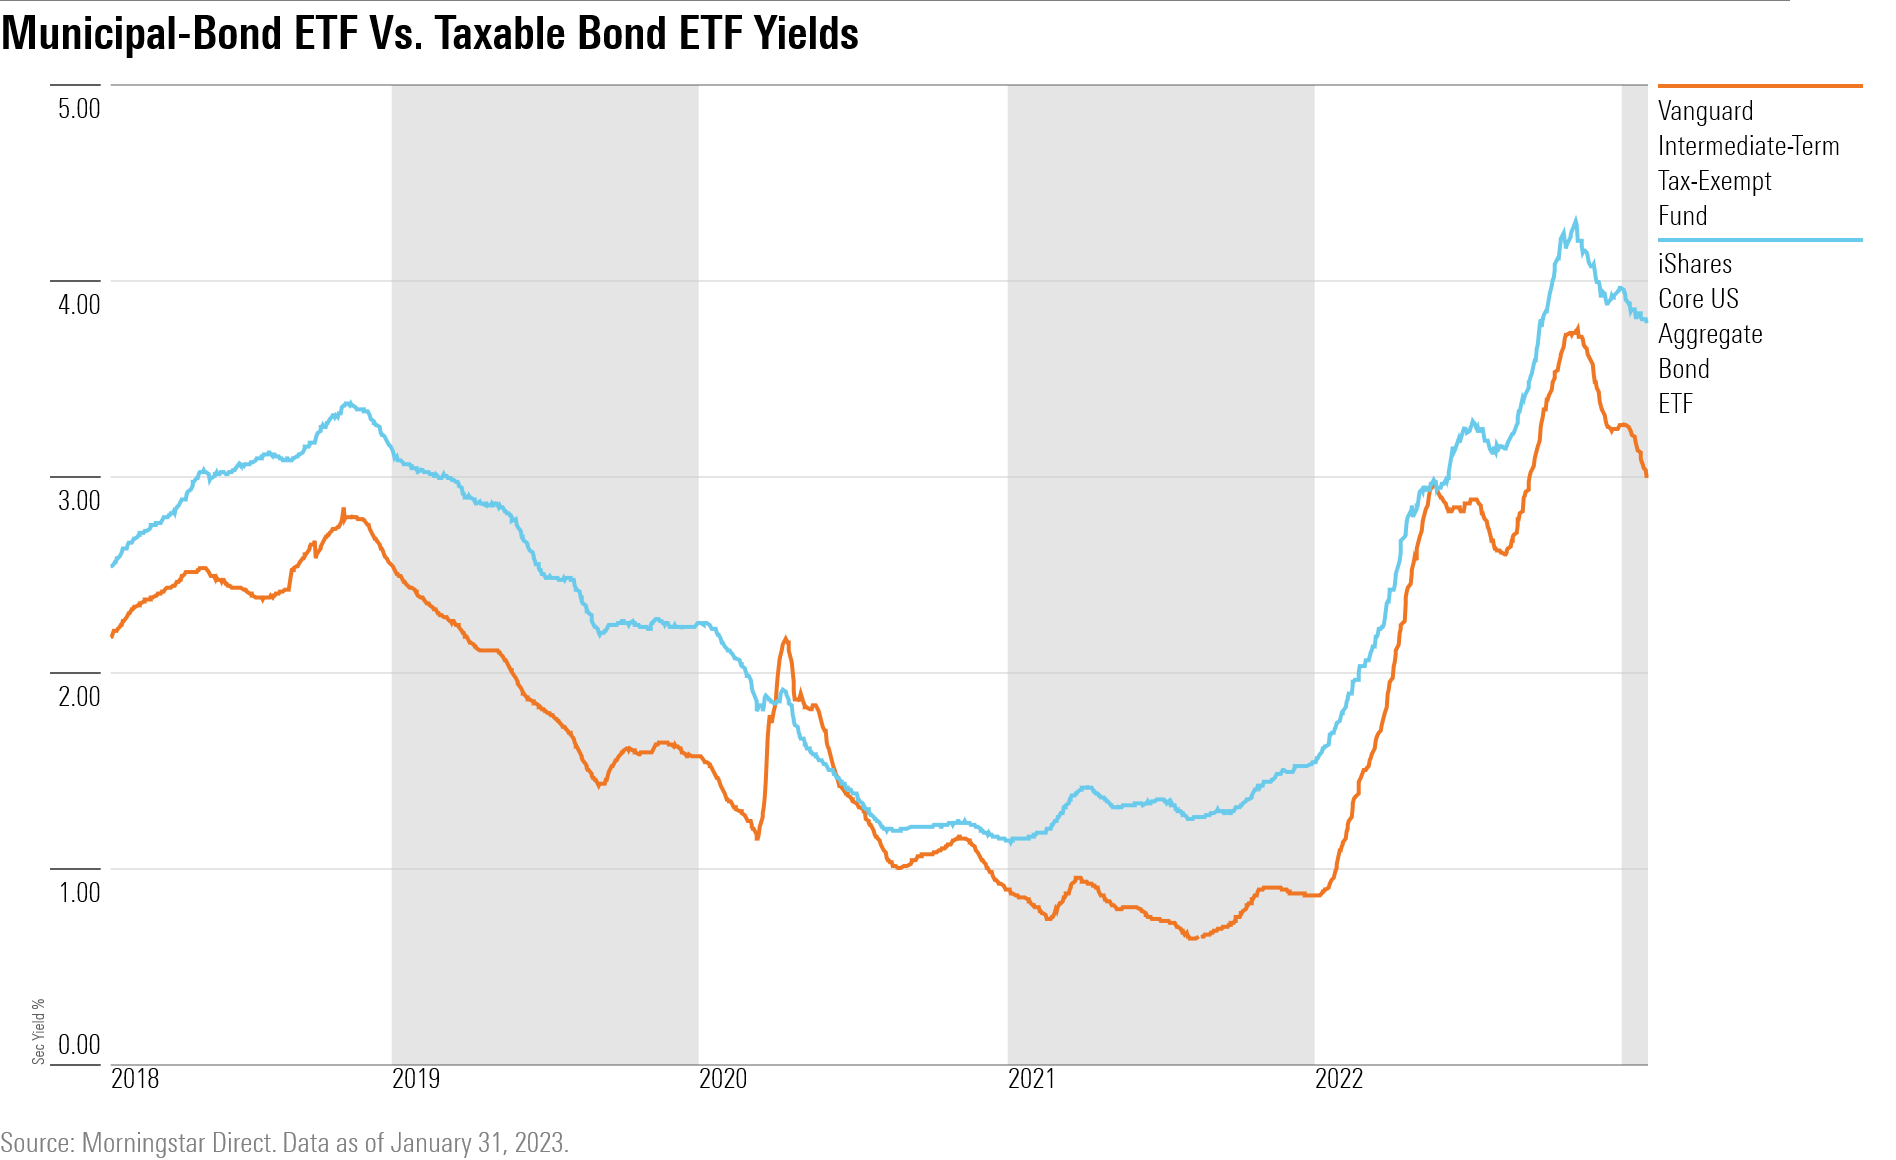
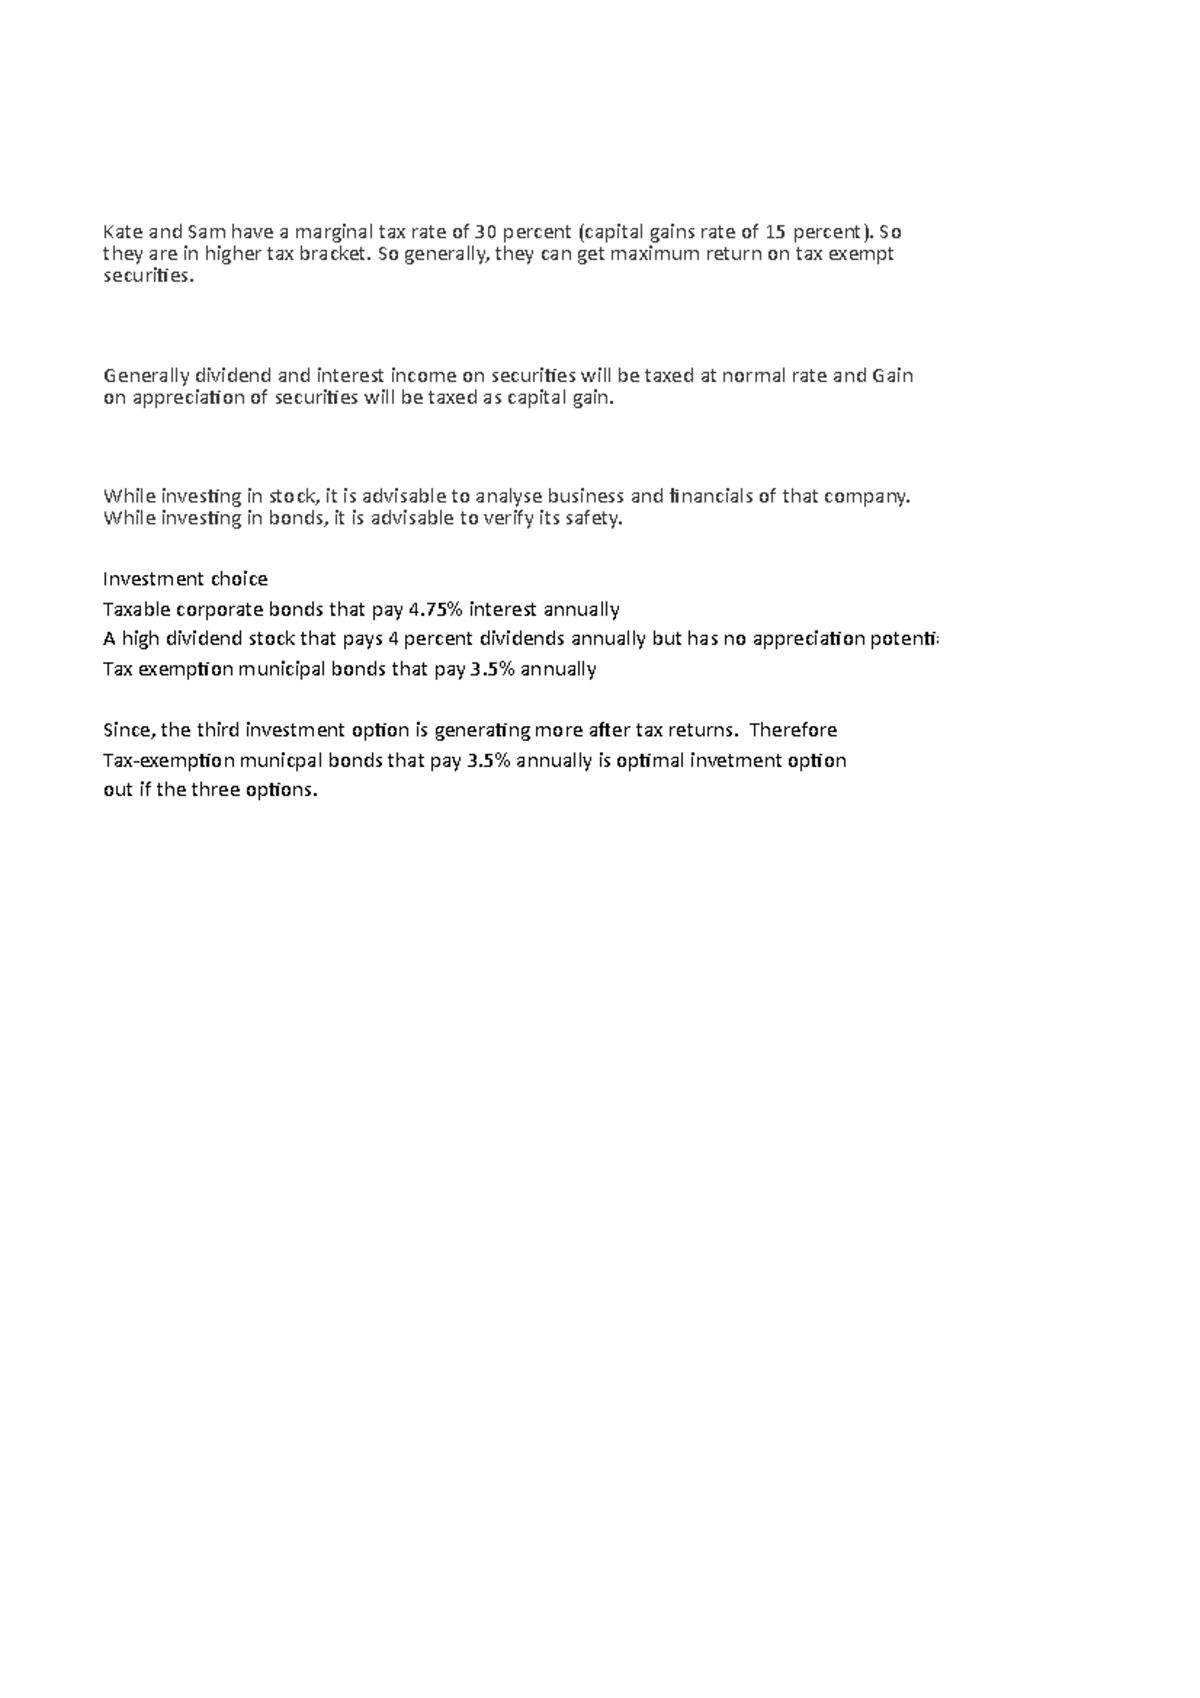
Because corporate bonds are fully taxable, comparing them to tax-exempt municipal bonds requires a calculation to see which investment actually puts more money in your pocket. This is known as the Taxable-Equivalent Yield (TEY).
The formula is:
TEY = Tax-Free Yield / (1 - Your Marginal Tax Rate)
For example, in 2026, if you are in a 35% federal tax bracket and are considering a tax-exempt municipal bond yielding 4%, the calculation would be:
0.04 / (1 - 0.35) = 0.0615 or 6.15%
This means a corporate bond would need to yield more than 6.15% to be a better investment than a 4% municipal bond, assuming all other risk factors are equal. This highlight why corporate bonds are often less attractive to individuals in the highest tax brackets unless held within tax-advantaged accounts.
Strategies for Managing Corporate Bond Taxes
Given the heavy tax burden, savvy investors use specific strategies to mitigate the impact on their total returns.
1. Asset Location
The most effective way to handle the taxability of corporate bonds is to hold them in tax-advantaged accounts, such as a Traditional IRA, Roth IRA, or 401(k).
- Traditional IRA/401(k): Taxes are deferred until you withdraw the money in retirement.
- Roth IRA: You pay taxes on the money going in, but all interest and capital gains earned within the account are tax-free upon withdrawal. By placing "tax-inefficient" assets like corporate bonds in these accounts, you avoid the annual tax drag on coupon payments.
2. Tax-Loss Harvesting
If the market value of your corporate bonds drops due to rising interest rates (a common occurrence in the volatile environment of 2026), you can sell those bonds at a loss to offset capital gains in other parts of your portfolio, such as stocks. You can also use up to $3,000 of capital losses to offset your ordinary income.
3. Avoiding "The Wash Sale Rule"
While the IRS wash sale rule primarily applies to stocks, the IRS Publication 550 provides guidelines on "substantially identical" securities. If you sell a corporate bond at a loss to gain a tax advantage, you must be careful not to buy back the same or a nearly identical bond within 30 days, or the tax loss may be disallowed.
Reporting Corporate Bond Income to the IRS
Documentation is essential for compliance. Financial institutions are required to send investors several versions of Form 1099 by early February each year.
- Form 1099-INT: This reports the interest income paid to you during the year. You must report this on Schedule B of your Form 1040.
- Form 1099-OID: If you hold zero-coupon bonds or bonds issued at a discount, this form shows the amount of "accrued interest" you must report as income, even if you didn't receive a check.
- Form 1099-B: This form reports the proceeds from the sale or redemption of a bond, which you will use to calculate your capital gains or losses on Schedule D.
Failure to accurately report this income can lead to penalties and interest. In 2026, the IRS has increased its automated matching capabilities, making it more likely that discrepancies between brokerage reports and individual filings will be flagged for review.
Frequently Asked Questions
Are corporate bonds taxed differently if they are "High Yield" vs "Investment Grade"?
No. The tax treatment remains identical regardless of the bond's credit rating. Both high-yield (junk) bonds and investment-grade bonds are subject to federal, state, and local taxes on interest and capital gains. However, high-yield bonds generate more interest income, which may push an investor into a higher tax bracket.
What happens if a corporate bond defaults?
If a corporation fails to make interest payments and the bond loses value or becomes worthless, you may be able to claim a bad debt deduction or a capital loss. The specifics depend on whether the bond is considered a "security" under tax law. Usually, for individual investors, this is treated as a capital loss on Form 8949.
Do I pay taxes on corporate bonds every year?
Yes, you generally pay taxes on the interest income in the year it is received. For OID bonds, you pay taxes on the accrued interest every year, even if no cash is paid out. The only exception is if the bonds are held in a tax-deferred account like an IRA.
Are there any corporate bonds that are tax-exempt?
No. By definition, corporate bonds are issued by private entities and do not qualify for the federal tax exemptions granted to government-sponsored municipal bonds. Some "green bonds" issued by corporations may offer ESG benefits, but they do not currently offer special federal tax breaks for individual investors.
How does the 2026 tax environment affect bond ladders?
With the sunsetting of certain tax provisions from previous years, the 2026 environment may see higher marginal rates for some individuals. When building a bond ladder (staggering maturities), it is vital to calculate the net-after-tax return for each rung to ensure the ladder is still meeting your income needs after the IRS takes its share.
Practical Recommendation for Investors
Before investing in corporate bonds in 2026, calculate your marginal tax rate (including state and local taxes). If you are in a high tax bracket (32% or higher), consider prioritizing corporate bonds for your retirement accounts (IRA/401k) and using municipal bonds for your taxable brokerage accounts. Always compare the taxable-equivalent yield of a corporate bond against a high-quality municipal bond to ensure you are being properly compensated for the additional tax burden and credit risk associated with corporate debt. If you are unsure of your specific obligations, consulting with a tax professional regarding IRS Schedule B requirements is highly recommended.
Image Gallery
Select an image to open it in a new tab.


Vivian Cho
Executive IT and Emerging Technologies Reporter
