How Mileage Amount Influences Health Insurance Premiums: Understanding the Relationship
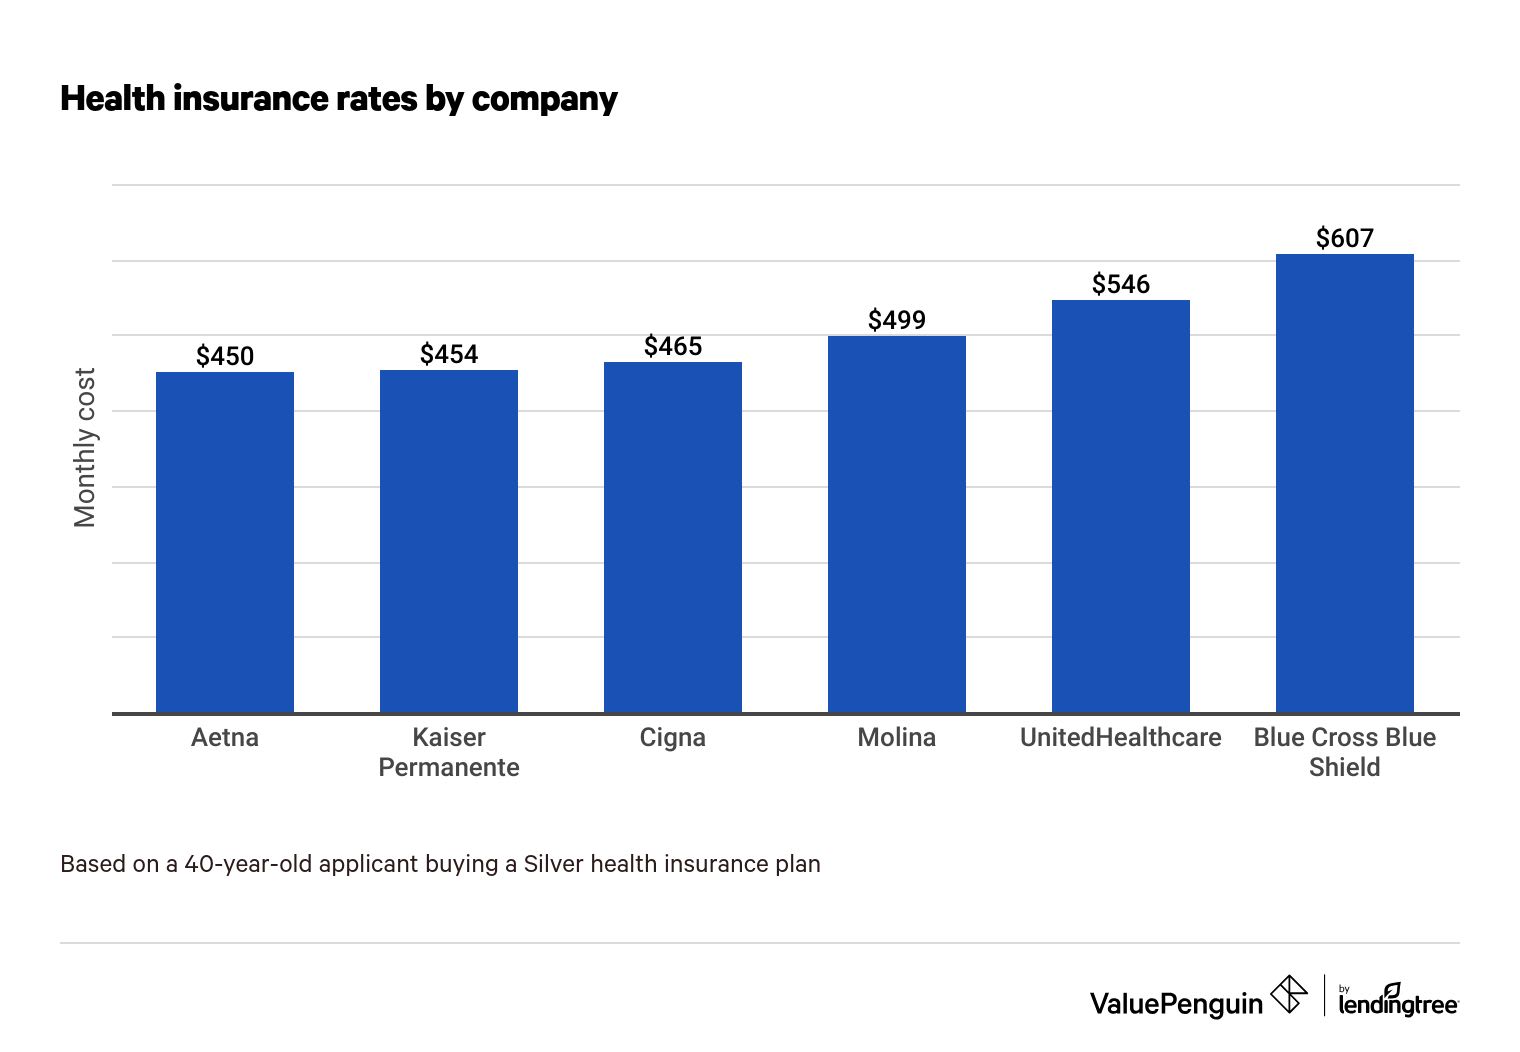
The amount of mileage an individual travels—typically associated with vehicle use—does not directly influence health insurance premiums. Health insurance pricing is fundamentally determined by factors such as age, location, tobacco use, and the specific plan category chosen. While vehicle mileage is a primary rating factor for auto insurance, it remains irrelevant to the underwriting processes used by health insurance providers in 2026.
Distinguishing Between Auto and Health Insurance Underwriting
To understand why mileage is not a factor in your health insurance costs, it is essential to first clarify how different types of insurance assess risk. Insurance companies function on the principle of actuarial science, where they calculate the likelihood of a claim being filed. The variables they analyze are directly correlated to the type of coverage provided.
Auto Insurance: Exposure and Mileage
In the auto insurance market, mileage is a critical metric. The more time a vehicle spends on the road, the higher the mathematical probability of an accident, theft, or mechanical incident. Insurers track annual mileage because it serves as a proxy for risk exposure. Higher mileage typically correlates with higher premiums, as the vehicle is subjected to more hours of traffic, varied road conditions, and a higher frequency of entry and exit from roadways.
Health Insurance: Biological and Demographic Risk
Health insurance underwriting operates on an entirely different set of metrics. Because health insurance covers medical costs—ranging from preventative screenings to major surgeries—the "risk" is tied to your physical body, your lifestyle choices, and your genetic predispositions. In 2026, the Affordable Care Act (ACA) guidelines remain in effect in the United States, strictly limiting the factors that insurers can use to determine your premium. These factors focus on personal health status and demographic information, not on how far you drive to work or travel for pleasure.
Factors That Actually Determine Health Insurance Premiums
If mileage is not a factor, what truly influences the monthly cost of your health insurance? The underwriting process is transparent and restricted by law. Understanding these pillars of pricing can help you better navigate plan selections and budget effectively.
1. Age
Age is one of the most significant predictors of medical service utilization. As individuals age, the frequency and complexity of medical visits often increase. Premiums are adjusted to account for the increased statistical probability of chronic conditions or age-related health needs.
2. Geographic Location
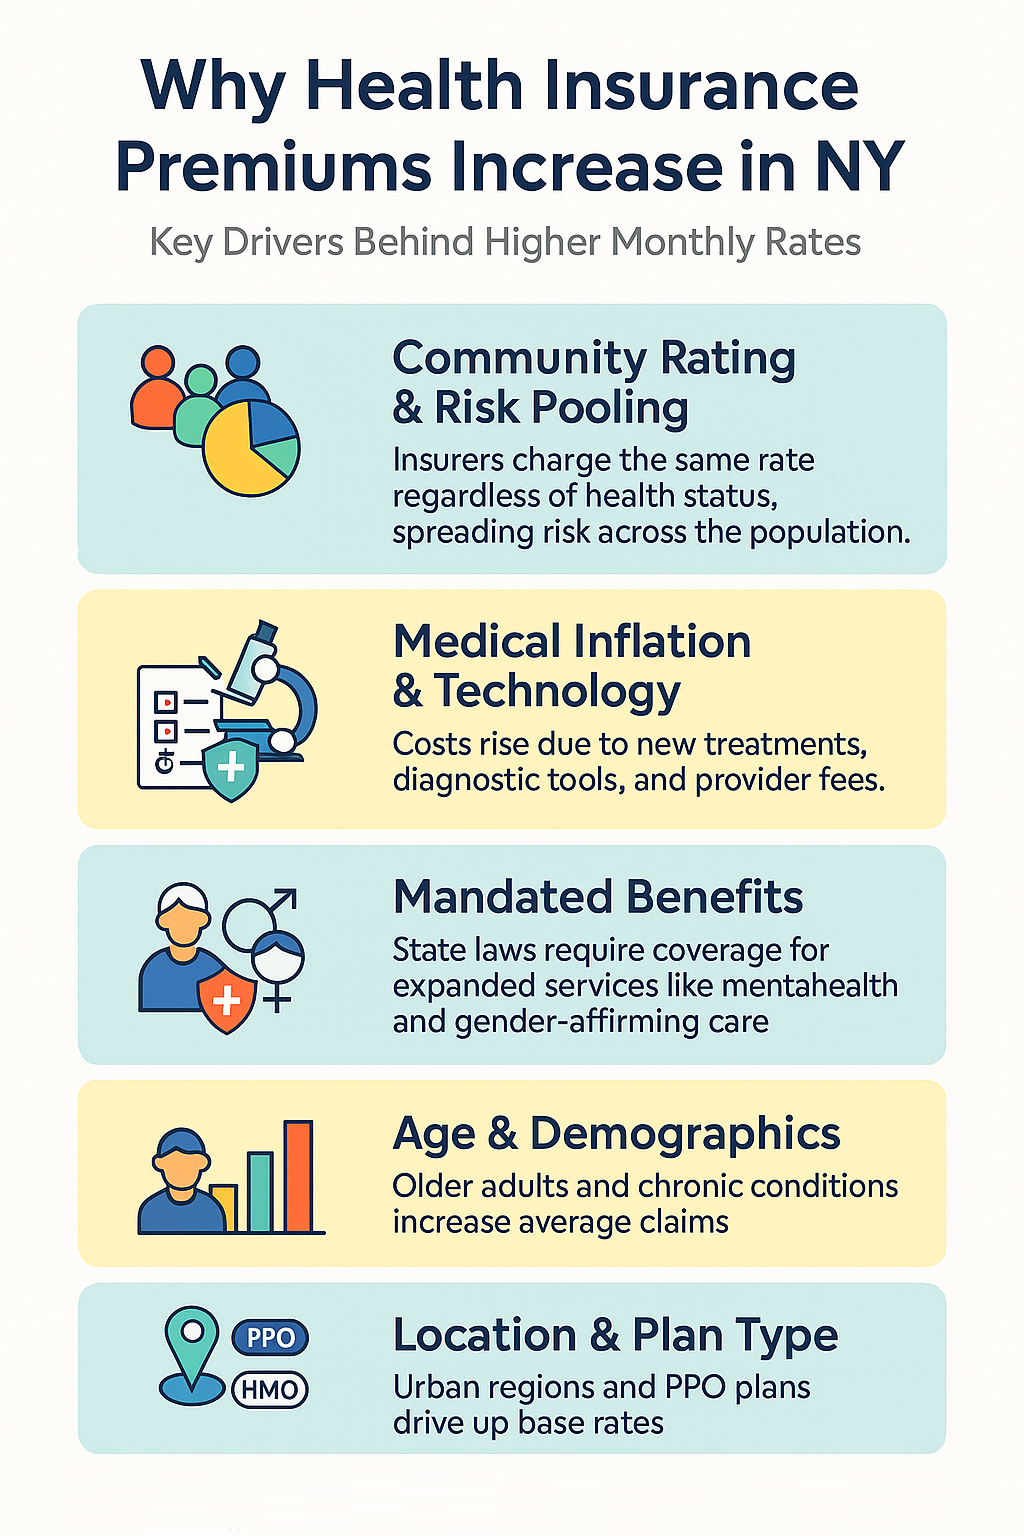
Where you live dictates your premium because of local healthcare market dynamics. The cost of medical services, the density of hospitals, the prevalence of insurance competition in your region, and the state-level regulations all play a role. A plan in a rural area with limited provider networks may be priced differently than a plan in a major metropolitan hub with high-cost facility overheads.
3. Tobacco Use
Most insurers are permitted to adjust premiums based on tobacco use. Because smoking and other forms of tobacco consumption are linked to significant health risks—such as cardiovascular disease, lung complications, and cancer—insurers view this as a modifiable risk factor. They may charge up to 50% more in premiums compared to a non-user, depending on the state’s regulatory environment.
4. Plan Category (Metal Levels)
The "metal level" (Bronze, Silver, Gold, Platinum) you choose determines the balance between your monthly premium and your out-of-pocket costs. Higher-tier plans (Gold/Platinum) have higher monthly premiums but lower deductibles and copayments. Lower-tier plans (Bronze/Catastrophic) offer lower monthly premiums but require you to pay more when you actually receive care.
Comparison of Insurance Rating Factors
The following table distinguishes between common factors analyzed by different insurance industries.
| Factor | Health Insurance Impact | Auto Insurance Impact |
|---|---|---|
| Annual Mileage | None | Primary rating factor |
| Age | High impact | Moderate to high impact |
| Geographic Location | High impact | High impact |
| Tobacco/Health Status | High impact | None |
| Driving Record | None | Primary rating factor |
| Credit Score | None | Variable by state |
Addressing the Confusion: Why People Link Mileage to Health Costs
If mileage has no bearing on health insurance, why does the question persist? The confusion often stems from the bundling of insurance products or the shift toward "telematics" in the broader insurance market.
Bundling Myths
Many consumers purchase their auto and health insurance through the same carrier. When they receive an annual notification that their total insurance bill has changed, they may conflate the two. If an individual drives significantly more in a given year and reports that mileage to their auto insurer, their auto premium will increase. If they mistakenly attribute this increase to their combined insurance profile, they may incorrectly conclude that their health insurance provider is also monitoring their driving habits.
The Rise of Wellness Programs and Digital Tracking
In 2026, some health insurers offer wellness programs that provide premium discounts for meeting certain health goals, such as completing a step count or attending a fitness class. While these programs involve tracking movement (often via wearable devices), they are strictly related to physical activity and health outcomes. They do not involve GPS tracking or mileage calculations associated with vehicle operation.
The Impact of Lifestyle on Health Costs (Beyond Mileage)
While "miles driven" is irrelevant, "lifestyle" remains a relevant factor in the broader context of health insurance—though not in the way mileage affects auto insurance. Lifestyle factors that influence your long-term health and your choice of plans include:
- Occupational Hazards: While your commute distance is ignored, your actual job function might influence your choice of insurance. For example, individuals in high-risk professions may look for plans with better accident or disability coverage, though this does not change the base premium of a standard health insurance plan.
- Preventative Care Participation: Engaging in regular preventative care does not lower your premium in a direct actuarial sense, but it does lower your total cost of ownership by preventing catastrophic health events.
- Diet and Exercise: Similar to preventative care, these factors improve personal health outcomes, which may influence your plan selection strategy, but they do not act as "rating factors" that an insurer uses to set your monthly price.
Next Steps: How to Optimize Your Health Insurance Premium
Since you cannot change your mileage to influence your health insurance rate, focus on the variables you can control to ensure you are getting the best value for your coverage.
Evaluate Your Plan Tier
If you have maintained a "Gold" plan but rarely visit the doctor, you may be overpaying for monthly premiums. In 2026, review your utilization from the previous year. If you only visit for annual checkups and infrequent sick visits, moving to a "Silver" or "Bronze" plan could significantly reduce your monthly fixed costs.
Check for Premium Tax Credits
If you purchase insurance through the Marketplace, ensure you are accurately reporting your projected income. Premium tax credits are tied to your financial situation, not your physical location or travel habits. An accurate income report ensures you receive the maximum subsidy for which you are eligible.
Leverage Employer-Sponsored Wellness
Many employers offer discounted premiums if you participate in wellness programs. Check your HR documentation to see if your company provides incentives for attending seminars, undergoing biometric screenings, or participating in corporate health challenges. These are the modern, legitimate ways to influence health insurance costs, which bear no relation to vehicle travel.
Frequently Asked Questions
Does my commute to work affect my health insurance rate?
No. Your commute distance, the time you spend in a vehicle, and the fuel efficiency of your car have zero impact on health insurance premiums. These factors are strictly reserved for auto insurance underwriting.
Can I get a discount on health insurance by walking to work?
You cannot get a direct discount on your monthly health insurance premium for walking to work. However, walking is a form of physical exercise that contributes to better health, which may lead to lower out-of-pocket medical costs over time.
Do insurance companies use telematics to track my health?
Some insurers provide optional wellness apps or trackers that monitor physical activity, such as steps taken or heart rate. These tools are used to reward healthy habits and are distinct from the GPS or telematics systems used by auto insurers to monitor driving speed, braking patterns, and mileage.
Why did my combined insurance bill increase?
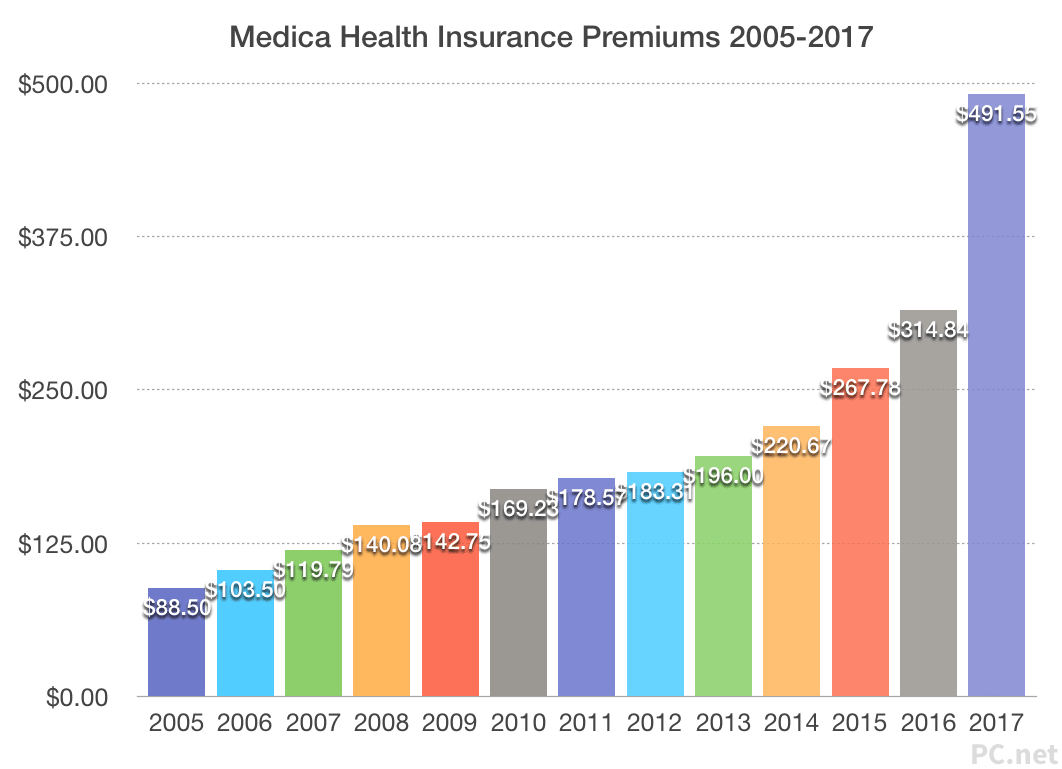
If your combined bill increased, it is likely due to an adjustment in your auto insurance premium—perhaps influenced by your mileage—or a change in the base rates of your health insurance plan due to age-rating or market-wide medical inflation. Always review the itemized statement to see which specific product (auto vs. health) experienced the price hike.
Are there any states where health insurance premiums are based on personal activity?
No. Under the Affordable Care Act, health insurance premiums are strictly regulated. They can only be adjusted based on age, location, family size, and tobacco use. No state is permitted to charge different health insurance premiums based on an individual's personal activity or travel habits.
Summary and Practical Recommendation
When analyzing your financial obligations for 2026, separate your insurance policies by their intent. Mileage is a valid concern for your vehicle coverage, as it accurately reflects your time spent on the road. For your health insurance, however, mileage is a non-factor. Do not attempt to modify your travel habits in an effort to save on healthcare costs; instead, focus on optimizing your plan level, exploring wellness credits offered by your employer, and maintaining health habits that reduce the need for high-cost medical interventions. Review your Summary of Benefits and Coverage (SBC) annually to ensure your plan tier aligns with your current financial and medical needs.
Image Gallery
Select an image to open it in a new tab.
Omar Farooq
EdTech Innovation and Virtual Pedagogy Journalist
