A Comprehensive Guide to Navigating Affordable Health Care Programs in 2026

An affordable health care program is a government-regulated or subsidized framework designed to provide medical insurance to individuals and families at reduced costs. In 2026, these programs primarily consist of the Affordable Care Act (ACA) Marketplace plans, Medicaid, and the Children’s Health Insurance Program (CHIP), which use income-based subsidies and eligibility rules to lower monthly premiums and out-of-pocket expenses.
The landscape of American health care continues to evolve, yet the core objective of an affordable health care program remains the same: ensuring that financial constraints do not prevent access to essential medical services. Whether you are self-employed, transitioning between jobs, or working for an employer that does not offer benefits, understanding how to navigate these programs is vital for both your physical and financial health.
The Pillars of Affordable Health Care in 2026
When discussing an affordable health care program, we are generally referring to a tripartite system involving federal oversight, state administration, and private insurance participation. By 2026, the mechanisms for making coverage affordable have become more streamlined, though the eligibility requirements remain specific to household size and annual income.
The Affordable Care Act (ACA) Marketplace
The ACA Marketplace, often accessed via HealthCare.gov or state-specific exchanges, is the most common route for those who do not qualify for employer-sponsored insurance. The "affordability" of these plans is driven by Advanced Premium Tax Credits (APTC). These credits act as a subsidy, paid directly to your insurance company to lower your monthly premium.
In 2026, these subsidies remain a critical component of the market. Following several legislative extensions over the early 2020s, the "subsidy cliff"—which previously cut off assistance for those earning more than 400% of the Federal Poverty Level (FPL)—has been managed through more progressive sliding scales. This ensures that even middle-income earners do not spend more than a fixed percentage of their income on health insurance premiums.
Medicaid and CHIP
For individuals and families with lower incomes, Medicaid serves as the primary affordable health care program. Unlike Marketplace plans, Medicaid often has little to no monthly premium and very low co-payments. Eligibility is determined primarily by income and, in some states, by categorical requirements such as pregnancy, disability, or age.
The Children’s Health Insurance Program (CHIP) works alongside Medicaid to provide low-cost health coverage to children in families that earn too much money to qualify for Medicaid but not enough to afford private insurance. By 2026, most states have expanded their CHIP programs to cover a wider range of preventative services, including dental and vision, which are essential for childhood development.
Understanding Plan Tiers and Cost-Sharing Reductions
One of the most complex aspects of choosing an affordable health care program is navigating the "Metal Tiers." These tiers—Bronze, Silver, Gold, and Platinum—do not reflect the quality of medical care but rather the distribution of costs between the insurer and the policyholder.
The Significance of Silver Plans
If you are looking for the most effective affordable health care program, the Silver Tier is often the most strategic choice. This is due to Cost-Sharing Reductions (CSRs). CSRs are a second type of subsidy that lowers the amount you have to pay out-of-pocket for deductibles, co-payments, and coinsurance.
Importantly, CSRs are only available if you enroll in a Silver-level plan. For an eligible family, a Silver plan with CSRs can effectively provide the low out-of-pocket costs of a Platinum plan but with the lower premium costs of a Silver plan.
Comparing the Metal Tiers for 2026
| Plan Tier | Premium Cost | Out-of-Pocket Cost | Best For |
|---|---|---|---|
| Bronze | Lowest | Highest | Healthy individuals who rarely see a doctor and want "catastrophic" protection. |
| Silver | Moderate | Moderate (Low with CSR) | Individuals qualifying for extra savings (CSRs) or those wanting balanced costs. |
| Gold | High | Low | Individuals with chronic conditions or those who prefer predictable monthly costs. |
| Platinum | Highest | Lowest | Individuals with very high medical utilization and frequent specialist visits. |
Eligibility and Requirements for 2026 Enrollment
To qualify for an affordable health care program through the Marketplace, several criteria must be met. These regulations ensure that subsidies are distributed to those who truly lack access to other "affordable" forms of coverage.
Income Calculations
Eligibility is based on your Modified Adjusted Gross Income (MAGI). This includes your adjusted gross income from your tax return, plus any tax-exempt interest and excluded foreign income. In 2026, the Marketplace uses the FPL guidelines from the previous year to determine your subsidy amount.
The "Affordability" Standard for Employer Coverage
If your employer offers health insurance, you generally cannot get a subsidized Marketplace plan unless the employer’s plan fails the "affordability test." In 2026, an employer plan is considered unaffordable if the premium for the lowest-cost self-only plan exceeds a specific percentage of your household income (usually around 8-9%). If the employer's plan is deemed unaffordable, you may then qualify for tax credits on the Marketplace.
Citizenship and Residency
To enroll in an affordable health care program, you must live in the United States, be a U.S. citizen or national (or be lawfully present), and not be incarcerated. Legal immigrants are generally eligible for Marketplace plans and subsidies, even if they have not been in the country long enough to qualify for Medicaid.
The Enrollment Timeline: Open vs. Special Enrollment
Timing is a critical factor in securing an affordable health care program. You cannot simply sign up for insurance at any time during the year unless you meet specific criteria.
- Open Enrollment Period (OEP): This is the annual window—typically running from November 1 to January 15—when anyone can sign up for a plan for the following year.
- Special Enrollment Period (SEP): Outside of the OEP, you can only enroll if you experience a Qualifying Life Event (QLE). These events include:
- Losing "minimum essential" health coverage (e.g., job loss or aging out of a parent's plan).
- Changes in household size (e.g., marriage, birth, or adoption).
- Changes in residence (moving to a new zip code or county).
- Changes in eligibility for subsidies based on income fluctuations.
In 2026, the window for an SEP is generally 60 days from the date of the qualifying event. Failing to enroll during this window may leave you without coverage until the next Open Enrollment Period.
How to Apply for an Affordable Health Care Program
The application process has been refined to be a "one-stop-shop" experience. When you apply through HealthCare.gov or your state exchange, the system automatically checks if you are eligible for Medicaid or CHIP before moving you to Marketplace plan options.
Step 1: Gather Documentation
Before starting the application, have the following ready:
- Social Security Numbers for everyone in the household.
- Information about your current income (W-2s, pay stubs, or tax returns).
- Details on any current health coverage available to you.
- Estimated household income for the 2026 tax year.
Step 2: Compare Plans
Use the online tools to filter plans by deductible, premium, and provider network. In 2026, it is essential to check the Provider Directory to ensure your preferred doctors and hospitals are in-network. Going out-of-network can result in massive bills that an affordable health care program would not otherwise cover.
Step 3: Select and Pay
Once you select a plan, you must pay your first premium directly to the insurance company to activate the coverage. Subsidies are handled automatically; if you qualify for a $300 credit and the plan costs $500, you will only be billed $200.
Common Pitfalls and Troubleshooting
Even with the best affordable health care program, users can run into complications. Awareness of these issues can prevent loss of coverage or unexpected tax liabilities.
Underestimating Income
Since tax credits are based on your estimated income for 2026, underestimating your earnings can lead to a surprise during tax season. If you earn more than you predicted, you may have to pay back some of the subsidies you received when you file your 2026 tax return. Conversely, if you earn less, you may get a refund. It is vital to update the Marketplace immediately if your income changes mid-year.
The "Family Glitch"
Historically, the "family glitch" prevented family members from getting subsidies if the employee’s self-only coverage was affordable, even if the family coverage was not. By 2026, regulations have solidified the fix for this issue, allowing family members to qualify for subsidies based on the cost of family coverage rather than just the individual's cost.
Network Restrictions (HMO vs. PPO)
Many affordable health care programs achieve lower premiums by using Health Maintenance Organization (HMO) or Exclusive Provider Organization (EPO) networks. These plans generally do not cover any out-of-network care except for emergencies. If you require a specific specialist, you must verify their participation in the plan’s network before enrolling.
Frequently Asked Questions
What happens if I miss the Open Enrollment deadline?
If you miss the deadline (typically mid-January for 2026 coverage), you cannot enroll in a Marketplace plan unless you qualify for a Special Enrollment Period (SEP). However, you can apply for Medicaid or CHIP at any time during the year, as these programs do not have restricted enrollment windows.
Can I get an affordable health care program if I am self-employed?
Yes. The ACA Marketplace was specifically designed to help the self-employed and "gig economy" workers. Your eligibility for subsidies is based on your net profit (income after business expenses), which often makes coverage highly affordable for small business owners and freelancers.
Are dental and vision covered under these programs?
For children, dental and vision are considered "essential health benefits" and must be covered. For adults, dental and vision are generally not included in standard Marketplace medical plans. You may need to purchase a separate "stand-alone" dental or vision plan, although some Gold or Platinum plans may include them as an added benefit.
How does the 2026 Federal Poverty Level affect my costs?
The Federal Poverty Level (FPL) is updated annually. As the FPL increases with inflation, the income thresholds for subsidies also shift. This means that a slight increase in your salary in 2026 might not necessarily disqualify you from subsidies, as the benchmarks for "affordability" have likely risen as well.
Is there a penalty for not having health insurance in 2026?
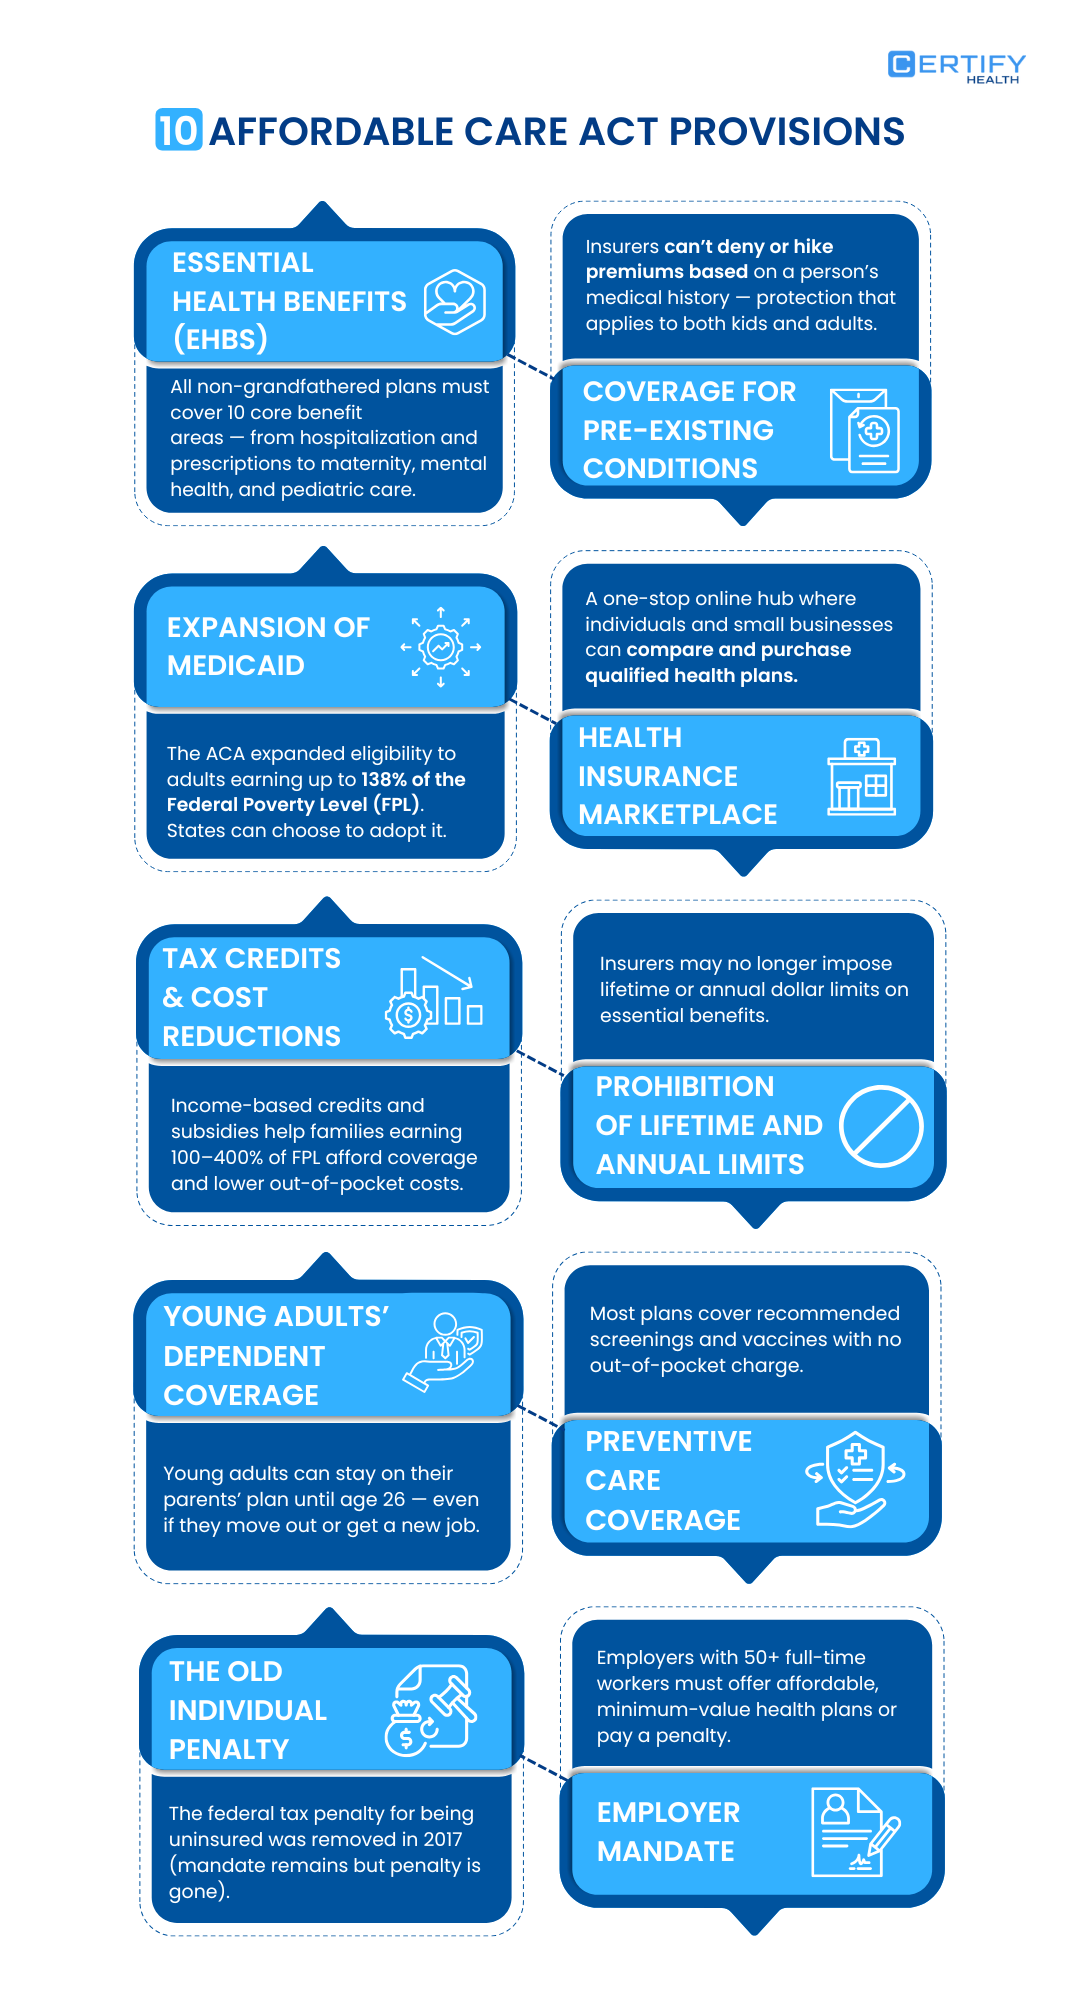
At the federal level, the individual mandate penalty was reduced to zero dollars starting in 2019. However, several states (such as California, Massachusetts, New Jersey, Rhode Island, and the District of Columbia) have their own state-level mandates. If you live in one of these areas and do not have an affordable health care program, you may face a penalty on your state tax return.
Taking Action for 2026
The most important step in securing an affordable health care program is early preparation. Review your current medical needs, estimate your 2026 income as accurately as possible, and begin comparing plans during the Open Enrollment Period. If you are currently uninsured or expect to lose coverage, visit HealthCare.gov to find your state’s specific portal and explore the financial assistance available to you. By taking advantage of the subsidies and cost-sharing reductions available in 2026, you can secure comprehensive coverage that protects both your health and your financial future.
Image Gallery
Select an image to open it in a new tab.

Ingrid Bjornson
Global Cyber Policy and Regulation Analyst
