Navigating Real Estate Projections: How to Use a Future Property Value Calculator

A future property value calculator is an online financial tool used by real estate investors, homeowners, and buyers to estimate what a piece of real estate might be worth at a specific date down the road. By factoring in historical appreciation rates, expected inflation, planned home renovations, and broader regional economic indicators, these calculators transform raw financial formulas into actionable forward-looking estimates. While no tool can predict market fluctuations or unexpected macroeconomic shocks with absolute certainty, understanding how to properly use and interpret these projections is essential for long-term financial planning and investment analysis.
Understanding the Mechanics of Property Appreciation
To understand how a future property value calculator works under the hood, you must first examine the core financial mechanics driving real estate appreciation. Property values rarely increase in a straight line, but digital calculators rely on standardized mathematical models to smooth out volatility and provide a baseline projection. The most common formula utilized is compound interest, mirrored from traditional finance to simulate year-over-year asset growth.
Appreciation is driven by a combination of macroeconomic factors and microeconomic variables. Macro factors include national inflation rates, population growth, employment rates, and benchmark interest rates set by central banks. When interest rates are low, borrowing costs drop, driving up demand and accelerating price growth. Conversely, micro factors involve neighborhood development, school district ratings, local zoning changes, and infrastructure investments, such as a new light rail station or highway expansion.
When inputting data into a projection model, users typically supply the current market value, an estimated annual appreciation rate, and a timeline measured in years. The calculator then applies the compound growth formula:
$$\text{Future Value} = \text{Current Value} \times (1 + r)^n$$
Where r represents the anticipated annual appreciation rate expressed as a decimal, and n represents the number of years into the future. Recognizing the limitations of this formula is critical. A linear compounding model assumes stable, uninterrupted growth, which historical real estate cycles prove is rarely the case. Real estate markets experience booms, corrections, and stagnation periods, making the output of any calculation a calculated estimate rather than a guaranteed financial outcome.
Key Inputs Required for Accurate Projections
The accuracy of any financial forecast depends entirely on the quality of the data entered. When utilizing a future property value calculator, users must gather specific, verified data points regarding the property and its surrounding market. Garbage-in, garbage-out applies directly to real estate modeling; vague or overly optimistic inputs will yield distorted financial forecasts that can derail investment strategies.
Current Market Value
The starting point for any calculation must be grounded in reality. Relying on outdated purchase prices or emotional attachments will invalidate the entire exercise. Users should establish current market value through recent comparable sales, known as "comps," of similar properties within the immediate neighborhood sold within the last three to six months. Professional appraisal reports or comparative market analyses (CMAs) provided by licensed real estate agents offer the most reliable baseline.
Estimated Annual Appreciation Rate
Selecting an appropriate appreciation rate is the most challenging step in the forecasting process. While historical national averages in the United States have traditionally hovered between 3% and 5% annually, local performance varies dramatically. A hot urban market or a rapidly growing suburban pocket might experience double-digit growth over short windows, while rural or economically stagnant areas might barely keep pace with inflation. Users should research historical ten-year and twenty-year appreciation trends for their specific zip code rather than applying a generalized national average.
Holding Period and Time Horizon
The duration of the projection significantly alters the outcome due to the compounding effect. Short-term forecasts (one to three years) are heavily influenced by current market momentum and seasonal cycles, whereas long-term forecasts (ten to thirty years) smooth out short-term volatility and lean more heavily on structural economic growth and inflation trends. Investors must align this timeline with their financial exit strategy, whether it is refinancing, selling, or transitioning the property into a long-term rental asset.
Evaluating Renovation Impacts and Capital Improvements
Property values are not purely passive reflections of the market; they can be actively manipulated through strategic capital improvements and regular maintenance. Advanced future property value calculators often include modules that allow users to factor in planned renovations, kitchen upgrades, bathroom additions, or energy-efficient retrofits.
When evaluating renovations, it is vital to distinguish between cosmetic updates and structural value-add projects. Replacing a leaking roof or updating an outdated electrical panel preserves value and prevents depreciation, but it rarely yields a dollar-for-dollar return on investment. On the other hand, functional layout changes, such as converting an unfinished basement into a legal accessory dwelling unit (ADU) or adding a second bathroom, can fundamentally alter the baseline earning potential and market appeal of the property.
Furthermore, investors must consider the concept of market ceiling. Every neighborhood has a maximum price threshold dictated by buyer willingness to pay for that specific location. Pouring substantial capital into luxury finishes in a modest, working-class neighborhood will yield diminishing returns because the property's value will inevitably be capped by surrounding comparable sales. Integrating renovation metrics into a valuation calculator requires balancing construction costs against projected equity increases and local market ceilings.
| Renovation Project | Average Cost Range | Estimated Value Add | Return on Investment (ROI) Potential |
|---|---|---|---|
| Minor Kitchen Remodel | $15,000 – $25,000 | $12,000 – $20,000 | 70% – 85% |
| Bathroom Addition | $35,000 – $60,000 | $20,000 – $35,000 | 55% – 70% |
| Siding Replacement | $12,000 – $22,000 | $10,000 – $18,000 | 75% – 80% |
| Backyard Deck Addition | $10,000 – $20,000 | $7,000 – $14,000 | 65% – 75% |
| Major Luxury Overhaul | $75,000 – $150,000 | $30,000 – $60,000 | 40% – 50% |
Comparing Forecasting Models and Analytical Tools
Not all valuation tools are built with the same underlying architecture. Understanding the differences between basic compound calculators and institutional forecasting platforms helps users select the right instrument for their specific needs, whether they are buying a single-family home or analyzing a multi-unit commercial portfolio.
Simple Compound Calculators
These are the most common tools found on public real estate portals and consumer finance websites. They require minimal inputs—typically current value, years, and appreciation rate—and output a single projected dollar figure. While easy to use, they lack granularity. They do not account for property taxes, insurance cost escalations, mortgage amortization, or transaction fees associated with eventually selling the asset.
Comprehensive Real Estate Investment Models
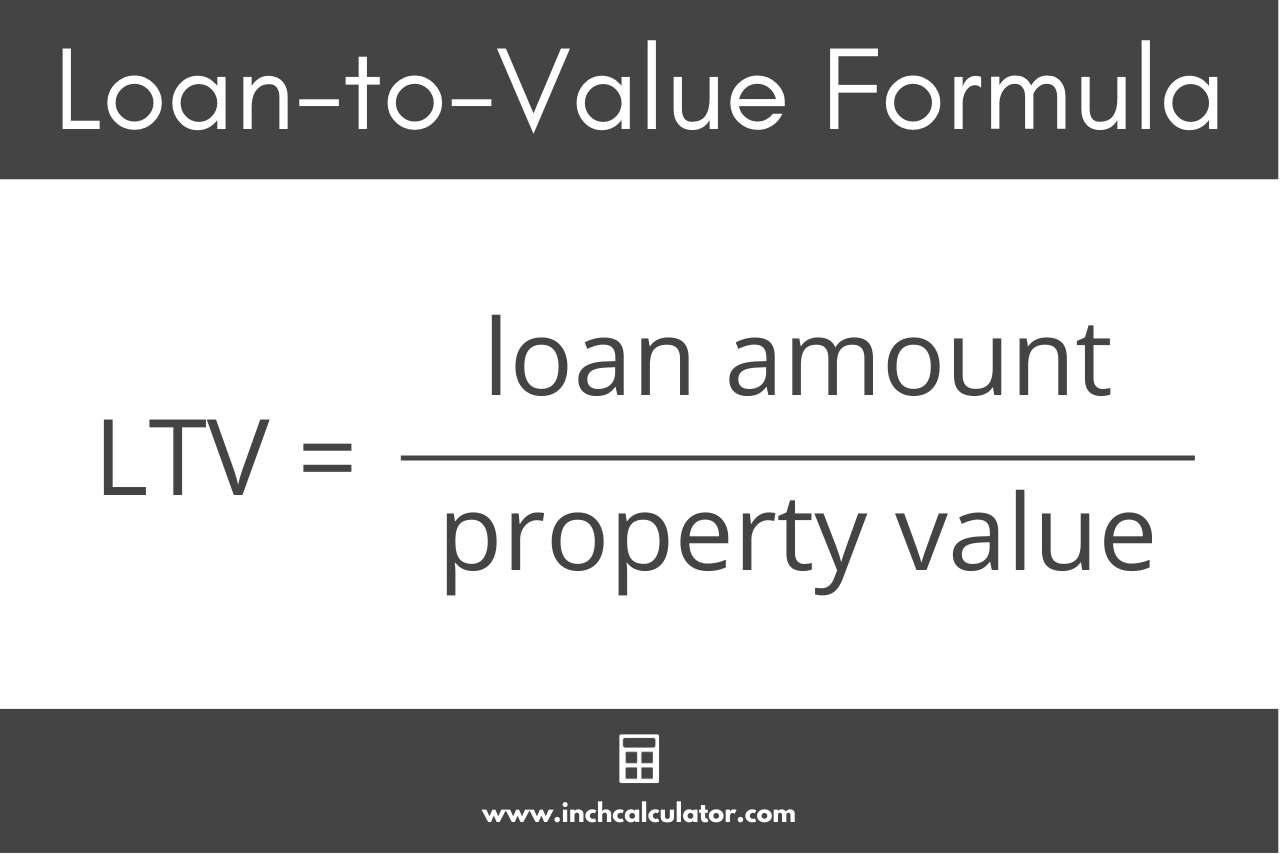
Advanced analytical platforms, often built in spreadsheet formats or specialized software suites, offer multi-variable projections. These tools factor in net operating income (NOI), cash flow growth, capital expenditure reserves, loan-to-value (LTV) ratios, and tax depreciation schedules. For serious investors, these models provide a holistic view of wealth accumulation, looking beyond mere property appreciation to evaluate total return on investment.
Automated Valuation Models (AVMs)
Utilized heavily by lenders and tech platforms, AVMs rely on machine learning algorithms and vast databases of public records, tax assessments, and MLS listings to estimate current and near-future property values. While powerful for quick appraisals, AVMs struggle to evaluate unique architectural features, recent custom upgrades, or localized neighborhood distress that has not yet registered in public sales databases.
Limitations, Risks, and Common Calculation Mistakes
Relying blindly on the output of a future property value calculator introduces significant financial risks. Real estate markets are inherently cyclical, and assuming that past performance guarantees future results is a dangerous trap for buyers and investors alike.
One of the most frequent mistakes is failing to account for inflation and holding costs. A property that appreciates from $400,000 to $600,000 over ten years looks like a massive win on paper, but if property taxes, insurance premiums, HOA fees, and maintenance costs have outpaced inflation, the net realized gain may be far lower than anticipated. Furthermore, selling a property incurs transaction costs—such as realtor commissions, transfer taxes, and closing fees—which typically consume 6% to 10% of the final sale price.
Macroeconomic shocks represent another uncontrollable risk variable. Sudden spikes in inflation can force central banks to raise interest rates aggressively, dampening buyer demand and causing temporary market corrections or stagnant pricing environments. Localized economic shifts, such as the closure of a major regional employer or military base, can also depress property values regardless of broader national economic health.
Investors must maintain a conservative margin of error when reviewing projections. Stress-testing a financial model by running scenarios with lower-than-average appreciation rates (or even flat growth periods) ensures that an investment strategy remains viable under adverse economic conditions.
Frequently Asked Questions
How accurate are future property value calculators?
Future property value calculators provide theoretical estimates based on mathematical formulas and historical trends rather than definitive predictions. Their accuracy depends heavily on the quality of the user's inputs, such as realistic appreciation rates and accurate current valuations, and they cannot foresee unforeseen economic downturns or market shocks.
What annual appreciation rate should I use in my calculations?
Users should research historical ten-year and twenty-year appreciation data specifically for their zip code or city rather than relying on generalized national averages. While historical national averages often sit between 3% and 5%, local markets can deviate significantly in either direction.
Do these calculators factor in mortgage debt and equity growth?
Most basic consumer-facing future property value calculators only measure total asset appreciation and do not calculate mortgage paydown or equity accumulation. To evaluate true wealth creation, investors must utilize comprehensive financial models that combine property appreciation with loan amortization schedules.
How do property taxes and maintenance costs impact future value?
While operating expenses like taxes and maintenance do not change the physical market value of the property, they heavily influence your net financial return. Rising holding costs reduce the net profit realized when the property is eventually sold, meaning gross appreciation should always be balanced against total cost of ownership.
Are renovations guaranteed to increase future property value?
Renovations do not automatically return their full cost in added property value. The increase in value is dictated by the quality of the work, prevailing neighborhood price ceilings, and whether the upgrade addresses functional deficiencies rather than hyper-personalized aesthetic tastes.
Next Steps for Strategic Property Planning
To move from theoretical calculations to practical financial execution, start by gathering verified comparable sales data for your target property to establish a rock-solid current baseline. Next, consult historical real estate performance metrics for your specific municipality to select a realistic, conservative appreciation rate rather than relying on best-case scenarios. Finally, factor in all anticipated holding costs, potential renovation expenses, and future transaction fees to ensure your long-term real estate strategy remains profitable across multiple economic cycles.
Image Gallery
Select an image to open it in a new tab.


Celine Dubois
Contemporary Living and Global Arts Columnist
