
International Private Placement Life Insurance (PPLI) has evolved from a niche offshore tax-optimization tool into a mainstream, transparent wealth-structuring vehicle for high-net-worth individuals. In 2026, the shift is defined by rigorous global compliance standards, the integration of complex alternative assets like private equity and digital tokens, and a move toward institutional-grade jurisdictions that prioritize regulatory stability over secrecy.
The Evolution of the PPLI Landscape
The historical perception of International Private Placement Life Insurance was often tethered to "offshore" banking—a term that once implied opacity and tax avoidance. However, as of 2026, the industry has undergone a radical transformation. This shift is primarily driven by the global demand for transparency and the realization that PPLI is, at its core, a highly efficient insurance wrapper rather than a mere tax loophole.
Modern PPLI structures are designed to provide tax-compliant growth and simplified reporting for families with cross-border footprints. The focus has moved from "hiding" assets to "protecting" them within a recognized legal framework. This evolution is most visible in the way policies are drafted; they now strictly adhere to the "Investor Control" doctrines of the policyholder’s home country, ensuring that the insurance remains valid in the eyes of tax authorities like the IRS in the United States or HMRC in the United Kingdom.
Furthermore, the "International" aspect of PPLI has expanded. While Bermuda and the Cayman Islands remains significant, there is a marked increase in the use of "mid-shore" jurisdictions like Luxembourg, Liechtenstein, and Singapore. These regions offer a sophisticated balance: they provide the robust legal protection of an insurance contract while satisfying the stringent "Substance" requirements and anti-money laundering (AML) protocols mandated by international bodies.
Regulatory Drivers: From Secrecy to Substance
The most profound shift in the PPLI market has been the global regulatory crackdown on non-compliant structures. In 2026, the operational environment for PPLI is governed by three major pillars: the Common Reporting Standard (CRS), the Foreign Account Tax Compliance Act (FATCA), and the OECD’s ongoing initiatives against Base Erosion and Profit Shifting (BEPS).
The Impact of CRS and FATCA
Under CRS and FATCA, the "automatic exchange of information" is no longer a future goal but a daily reality. International PPLI providers are now sophisticated financial institutions that report policy values and beneficial ownership to the relevant tax authorities. This transparency has actually increased the popularity of PPLI among the compliant wealthy. Because the insurance company technically owns the underlying assets, the policyholder’s reporting requirements are often simplified into a single line item on their tax return, rather than dozens of individual asset disclosures.
The Rise of Economic Substance Requirements
Jurisdictions are now required to prove that they are not merely "letterbox" locations. To remain on the "white lists" of the OECD and the EU, PPLI providers must demonstrate significant local presence, including qualified staff and physical offices. For the policyholder, this means choosing a provider in a jurisdiction with high "economic substance" is no longer optional—it is a prerequisite for ensuring the policy is not disregarded by their home country’s tax office.

Asset Class Diversification in 2026
Ten years ago, PPLI was used primarily for traditional portfolios of stocks and bonds. Today, the shift in international PPLI is characterized by the inclusion of highly illiquid and alternative assets. Wealthy families are increasingly looking to wrap "non-traditional" investments to benefit from the tax-deferred environment provided by the insurance structure.
Private Equity and Venture Capital
Private equity (PE) has become a staple of international PPLI portfolios. By holding PE interests within a PPLI policy, investors can avoid the complex annual tax filings associated with K-1s (in the US) or similar partnership distributions. The PPLI policy acts as a "blocker," allowing the capital to compound within the policy without triggering immediate tax events upon the sale of underlying portfolio companies.
Real Estate and Physical Assets
While more complex due to valuation and liquidity requirements, certain types of commercial real estate and even fine art are being integrated into PPLI structures. The key requirement in 2026 remains the "diversification rule." To qualify as life insurance in many jurisdictions, the policy’s underlying account cannot be concentrated in a single asset. This has led to the creation of bespoke "Insurance Dedicated Funds" (IDFs) that pool various alternative assets to satisfy regulatory diversification standards.
Digital Assets and Tokenization
In 2026, the integration of digital assets into PPLI is a major trend. Sophisticated carriers now have the custodial infrastructure to hold Bitcoin, Ethereum, and tokenized real-world assets (RWAs). For the policyholder, wrapping these high-growth, high-volatility assets in a life insurance policy provides a way to manage future capital gains taxes while facilitating the eventual transfer of these digital estates to the next generation.
Comparing Key PPLI Jurisdictions
Choosing a jurisdiction is a critical decision that impacts the policy’s legal strength and tax efficacy. The following table compares the dominant PPLI jurisdictions as they stand in 2026.
| Jurisdiction | Primary Strength | Regulatory Framework | Typical Asset Flexibility |
|---|---|---|---|
| Bermuda | Speed and Customization | BMA (Bermuda Monetary Authority) | High; excellent for PE and complex alternatives. |
| Luxembourg | EU "Passporting" and Security | CAA (Commissariat aux Assurances) | Moderate; strict "Triangle of Security" for asset protection. |
| Singapore | Access to Asian Markets | MAS (Monetary Authority of Singapore) | High; popular for VCC-linked insurance structures. |
| Liechtenstein | Civil Law Stability | FMA (Financial Market Authority) | High; integrated well with European private banking. |
| Cayman Islands | Institutional Expertise | CIMA (Cayman Islands Monetary Authority) | Very High; preferred for hedge fund-heavy portfolios. |
The Mechanics of an International PPLI Policy
Understanding the shift in PPLI requires a look at how these policies are structured to remain compliant in 2026. A PPLI policy is not a retail product; it is a bespoke contract between a high-net-worth individual and an international insurance carrier.
- The Premium Payment: The policyholder contributes cash or "in-kind" assets (like stock or PE interests) to the insurance company. The minimum entry point for international PPLI is generally $1 million to $5 million, though most institutional-grade policies involve $20 million or more.
- The Segregated Account: The assets are held in a separate account, legally insulated from the insurance company’s general creditors. If the insurance company fails, the policyholder’s assets remain protected.
- The Investment Manager: The insurance company appoints an external Investment Manager (often the policyholder’s existing wealth manager) to trade the assets. However, to satisfy "Investor Control" rules, the policyholder cannot dictate specific trades to the manager.
- The Death Benefit: Like any life insurance, the PPLI policy pays out a death benefit to beneficiaries. In an international context, this benefit is often structured to be paid out tax-free, providing a highly efficient mechanism for liquidity during estate settlement.
Risks and Pitfalls: The Modern Compliance Burden
The shift toward transparency means that errors in PPLI structuring are more likely to be discovered than ever before. There are three primary risks that investors must navigate in 2026.
The Investor Control Doctrine
This is the most common cause of PPLI failure. If a policyholder exercises too much influence over the underlying investment decisions—such as telling the manager which specific stocks to buy or sell—the tax authorities may "look through" the policy. If the policy is disregarded, all accumulated gains become immediately taxable as if the insurance never existed.
Valuation and Liquidity
For alternative assets like private equity or real estate, accurate annual valuations are mandatory. In 2026, regulators have increased their scrutiny of "stale" valuations. If an asset cannot be valued accurately, the insurance company may be forced to exclude it from the policy, potentially triggering a partial surrender and tax liabilities.
KYC and AML Compliance
The onboarding process for international PPLI has become incredibly rigorous. Carriers now require deep-dive "Know Your Customer" (KYC) documentation, including the detailed Source of Wealth (SoW) and Source of Funds (SoF). The shift here is from a "check-the-box" exercise to a forensic analysis of how the family’s wealth was generated over decades.
Why PPLI is Gaining Momentum with Family Offices
The "shift" isn't just about regulation; it’s about utility. Family offices are increasingly using PPLI as a "master wrapper" for their global holdings.
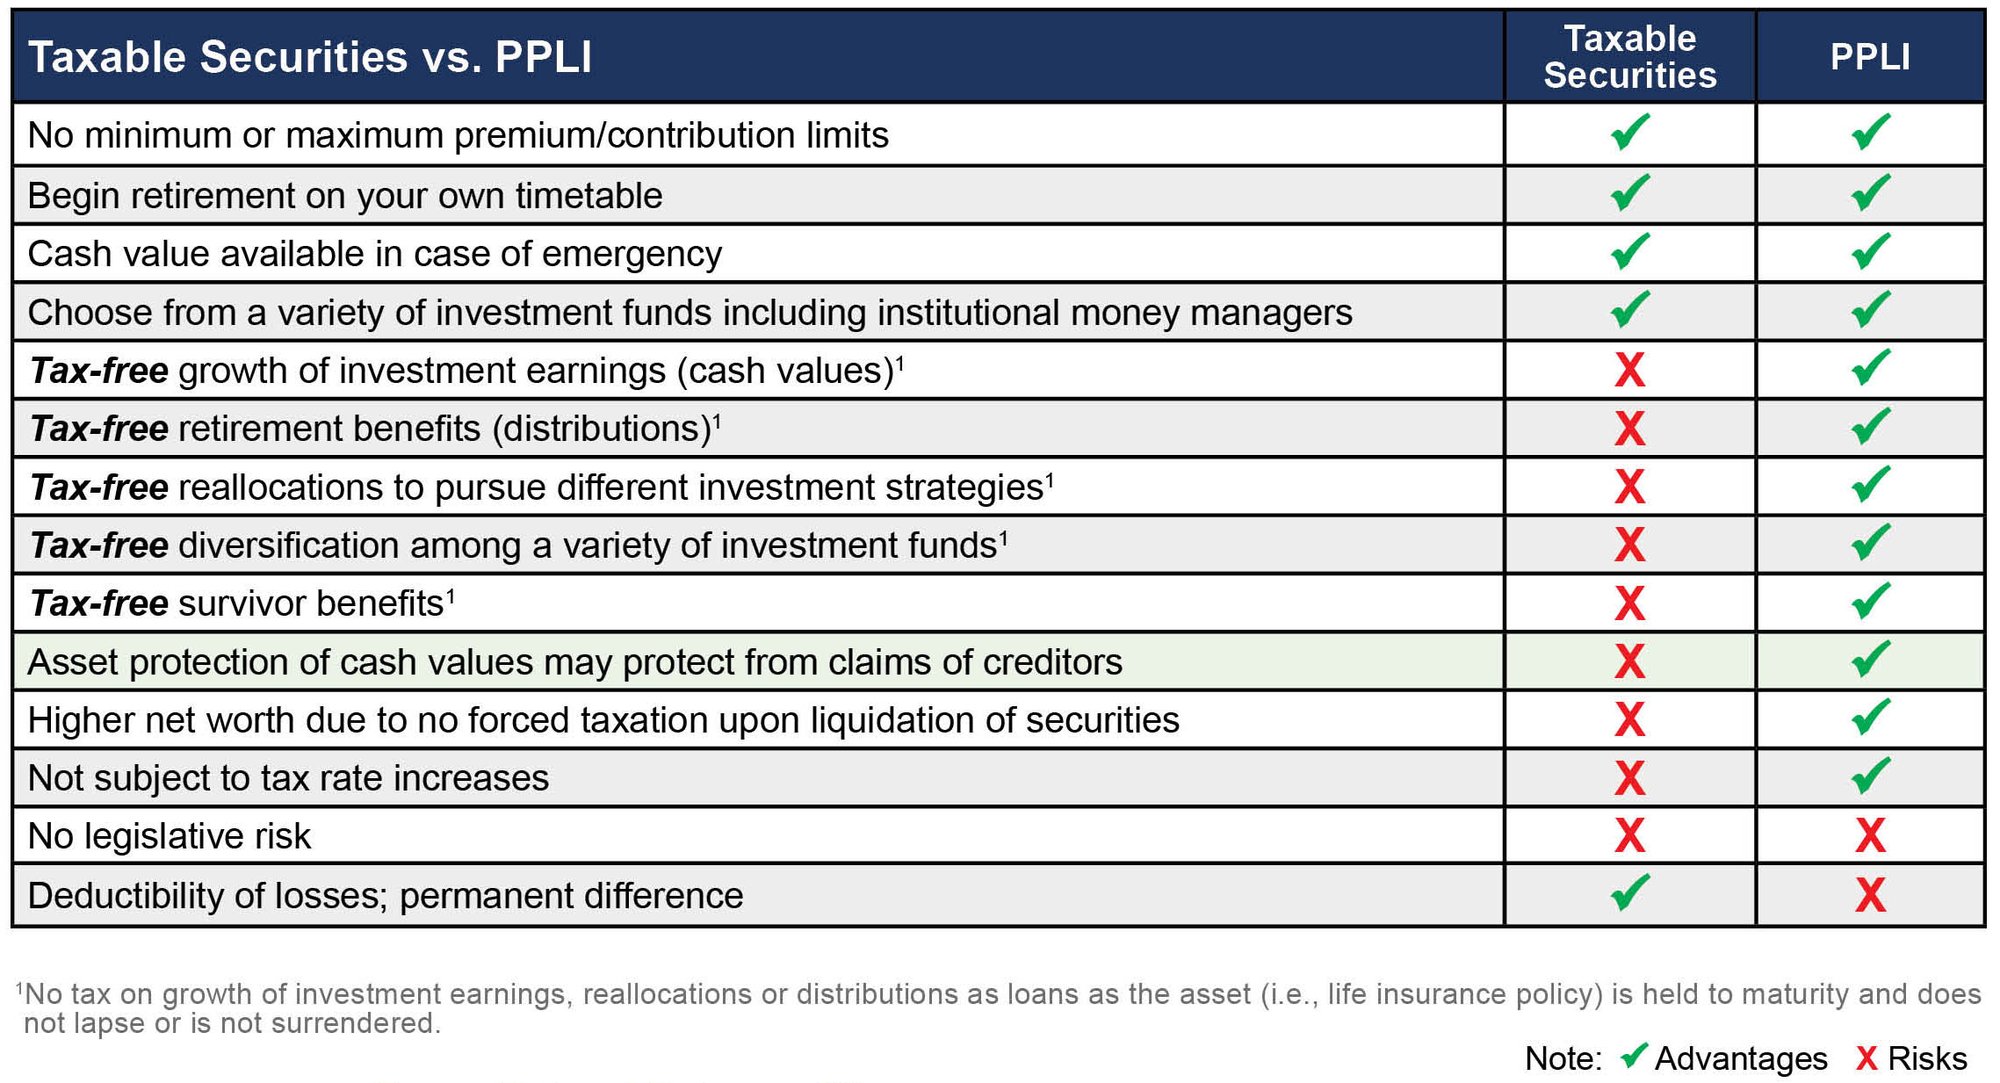
- Tax Deferral: Within the PPLI wrapper, dividends, interest, and capital gains accumulate gross of tax. This allows for faster compounding of wealth compared to a taxable brokerage account.
- Asset Protection: Most PPLI jurisdictions have robust laws that protect life insurance assets from the claims of future creditors (provided the transfer wasn't a fraudulent conveyance).
- Estate Simplification: Upon the death of the insured, the policy pays out to the beneficiaries. This bypasses the often lengthy and expensive probate process, which is especially beneficial for families with assets in multiple countries.
- Confidentiality (Post-CRS): While the government knows about the policy (due to CRS), the general public and potential litigants do not. PPLI provides a layer of privacy that is increasingly difficult to find in 2026.
Frequently Asked Questions
What is the minimum net worth required for an international PPLI policy? While insurance companies set their own minimums—often $1 million to $5 million in premium—PPLI is generally most cost-effective for individuals with a net worth exceeding $20 million. This is due to the fixed costs of legal structuring, independent investment management, and annual compliance reporting.
Can I move my existing stock portfolio into a PPLI policy? Yes, this is known as an "in-kind" contribution. However, it is a taxable event in many jurisdictions. You would technically be "selling" the assets to the insurance company, which may trigger capital gains taxes at the time of the transfer. Once inside the policy, however, all future growth is tax-deferred.
How does "Investor Control" work in 2026? The rule is simple but strict: the policyholder can select a general investment strategy (e.g., "Aggressive Growth" or "Fixed Income") and can choose the Investment Manager, but they cannot tell the manager what to buy or sell. If the policyholder retains the power to direct specific transactions, the tax benefits of the PPLI structure are usually lost.
Is PPLI still legal after the latest OECD updates? Yes. PPLI is a globally recognized insurance product. The shift in 2026 is not away from PPLI itself, but away from non-compliant, non-transparent versions of it. As long as the policy is properly reported under CRS/FATCA and follows the tax laws of the policyholder’s home country, it remains a robust and legal planning tool.
What happens to the assets if the international insurance company goes bankrupt? In top-tier jurisdictions like Luxembourg or Bermuda, PPLI assets are held in "segregated accounts." These accounts are legally separate from the insurance company's general ledger. If the carrier becomes insolvent, these assets are reserved for the policyholders and are generally not available to the company’s other creditors.
Final Considerations for 2026
If you are considering an international PPLI policy, the first step is a comprehensive "tax nexus" analysis. Because PPLI involves complex cross-border legalities, you must ensure the structure is compliant not just where the insurance company is located, but where you (the policyholder) and your beneficiaries reside. In 2026, the era of "set it and forget it" offshore planning is over; successful PPLI strategies require ongoing professional oversight and a commitment to total transparency with global tax authorities.
Disclaimer: This article is for informational purposes only and does not constitute legal, tax, or financial advice. Always consult with qualified professionals in your specific jurisdiction.
Image Gallery
Select an image to open it in a new tab.



Mateo Castillo
Decentralized Finance and E-Payments Strategist
