Finding the best auto insurance in the 75043 zip code of Garland, Texas, requires balancing state-mandated minimums with the specific risks of the North Texas region. In 2026, drivers in this area typically pay between $1,800 and $2,600 annually for full coverage, influenced by high-traffic commutes on I-30 and regional weather patterns like frequent hail.
The Landscape of Auto Insurance in 75043 (Garland, TX)
The 75043 zip code covers a significant portion of southern Garland, bordering Lake Ray Hubbard to the east and extending toward the intersection of Interstate 30 and the President George Bush Turnpike. This specific geography plays a massive role in how insurance actuaries determine premiums. Residents here aren't just driving local neighborhood streets; they are often part of the massive daily migration into Dallas or northern suburbs like Plano and Richardson.
In 2026, the Texas insurance market remains one of the most competitive in the United States. However, it is also one of the most volatile due to the increasing frequency of "billion-dollar" weather events and the rising cost of high-tech vehicle repairs. For a resident of 75043, understanding local rates isn't just about finding the cheapest monthly payment; it is about ensuring that the policy can withstand the specific environmental and legal pressures of living in Dallas County.
Why Zip Code 75043 Matters to Insurers
Insurers use zip codes to track "loss experience." In 75043, several factors contribute to the risk profile:
- Commute Intensity: Residents frequently use I-30 and the PGBT, both of which have high accident rates during peak hours.
- Weather Volatility: This area is situated in a high-risk zone for convective storms, which bring large hail and occasional tornadic activity.
- Vehicle Theft and Vandalism: While Garland has robust local law enforcement, being part of the greater Dallas metropolitan area means higher-than-average rates of vehicle-related crimes compared to rural Texas.
Minimum Texas State Requirements vs. Recommended Coverage
Texas law follows a "fault" system. If you cause an accident, you are responsible for the damages. The state-mandated minimum liability limits, often referred to as 30/60/25, are frequently insufficient for the realities of 2026.
Breaking Down 30/60/25
- $30,000 Bodily Injury per Person: This covers medical bills for a single person you injure. In 2026, a single overnight stay in a Dallas-area trauma center can easily exceed this amount.
- $60,000 Bodily Injury per Accident: This is the total the policy will pay for all injuries in one collision. If you hit a vehicle with three passengers, this limit is stretched extremely thin.
- $25,000 Property Damage: This pays for the other person’s car or property. Given that the average price of a new vehicle in 2026 hovers near $50,000, a $25,000 limit leaves the driver personally liable for the remaining balance if they total a modern SUV or electric vehicle.
The Case for Higher Limits in 75043
Because 75043 is a bridge between residential areas and major commercial hubs, the likelihood of an accident involving a high-value vehicle or multiple parties is elevated. Professionals in the area are increasingly opting for 100/300/100 coverage. While this increases the premium, it provides a buffer that protects personal assets—like a home in the many established neighborhoods of southern Garland—from being seized in a lawsuit following a major accident.
Factors Influencing 75043 Insurance Rates in 2026
Several primary variables dictate what a resident will pay. In 2026, these factors have evolved due to new technology and shifting economic conditions.
1. The "Hail Factor" and Comprehensive Coverage
North Texas is notorious for hail. In 75043, comprehensive coverage (which covers non-collision events) is often more expensive than in other parts of the country. Many residents choose a separate, lower deductible specifically for glass and hail damage. By 2026, insurers have integrated more precise meteorological data into their pricing, meaning if your specific neighborhood has a history of microbursts or hail "alleys," your rates may reflect that hyper-local risk.
2. Telematics and Driving Behavior
By 2026, most major carriers like State Farm, Geico, and Progressive offer significant discounts for using telematics—devices or apps that track braking, speed, and time of day. For a 75043 driver who avoids the I-30 rush hour or works from home, these programs can reduce premiums by up to 30%. However, for those with a heavy foot on the Bush Turnpike, these programs might actually lead to rate increases depending on the carrier's policy.
3. Credit-Based Insurance Scores
Texas remains a state where insurers can use your credit history to help determine your premium. In 75043, maintaining a high credit score is one of the most effective ways to lower insurance costs. Actuaries have found a high correlation between financial responsibility and driving safety.
4. Vehicle Sophistication
In 2026, even "budget" cars are equipped with LiDAR, cameras, and complex sensor arrays. A minor fender bender in a Garland parking lot that would have cost $500 to fix a decade ago can now cost $4,000 because of the calibration required for Advanced Driver Assistance Systems (ADAS). This "repair inflation" is a primary driver of the rate increases seen across 75043.
Comparing Major Carriers in the Garland Area
Residents in 75043 have access to national giants and Texas-specific regional players. Each has different strengths depending on the driver's profile.
| Carrier | Best For | Typical Discount Opportunities |
|---|---|---|
| State Farm | Personalized Service | Multi-policy (Home + Auto) is highly competitive in Garland. |
| GEICO | Budget-Conscious Drivers | Strongest discounts for federal employees and military. |
| Progressive | Tech-Savvy/Telematics | The "Snapshot" program is ideal for low-mileage 75043 drivers. |
| Texas Farm Bureau | Local Roots | Often provides lower rates for long-term Texas residents. |
| USAA | Military & Families | Generally the highest-rated for claims satisfaction in Dallas County. |
| Allstate | New Car Owners | Excellent "New Car Replacement" and "Gap Coverage" options. |
Essential Coverage Add-ons for North Texas
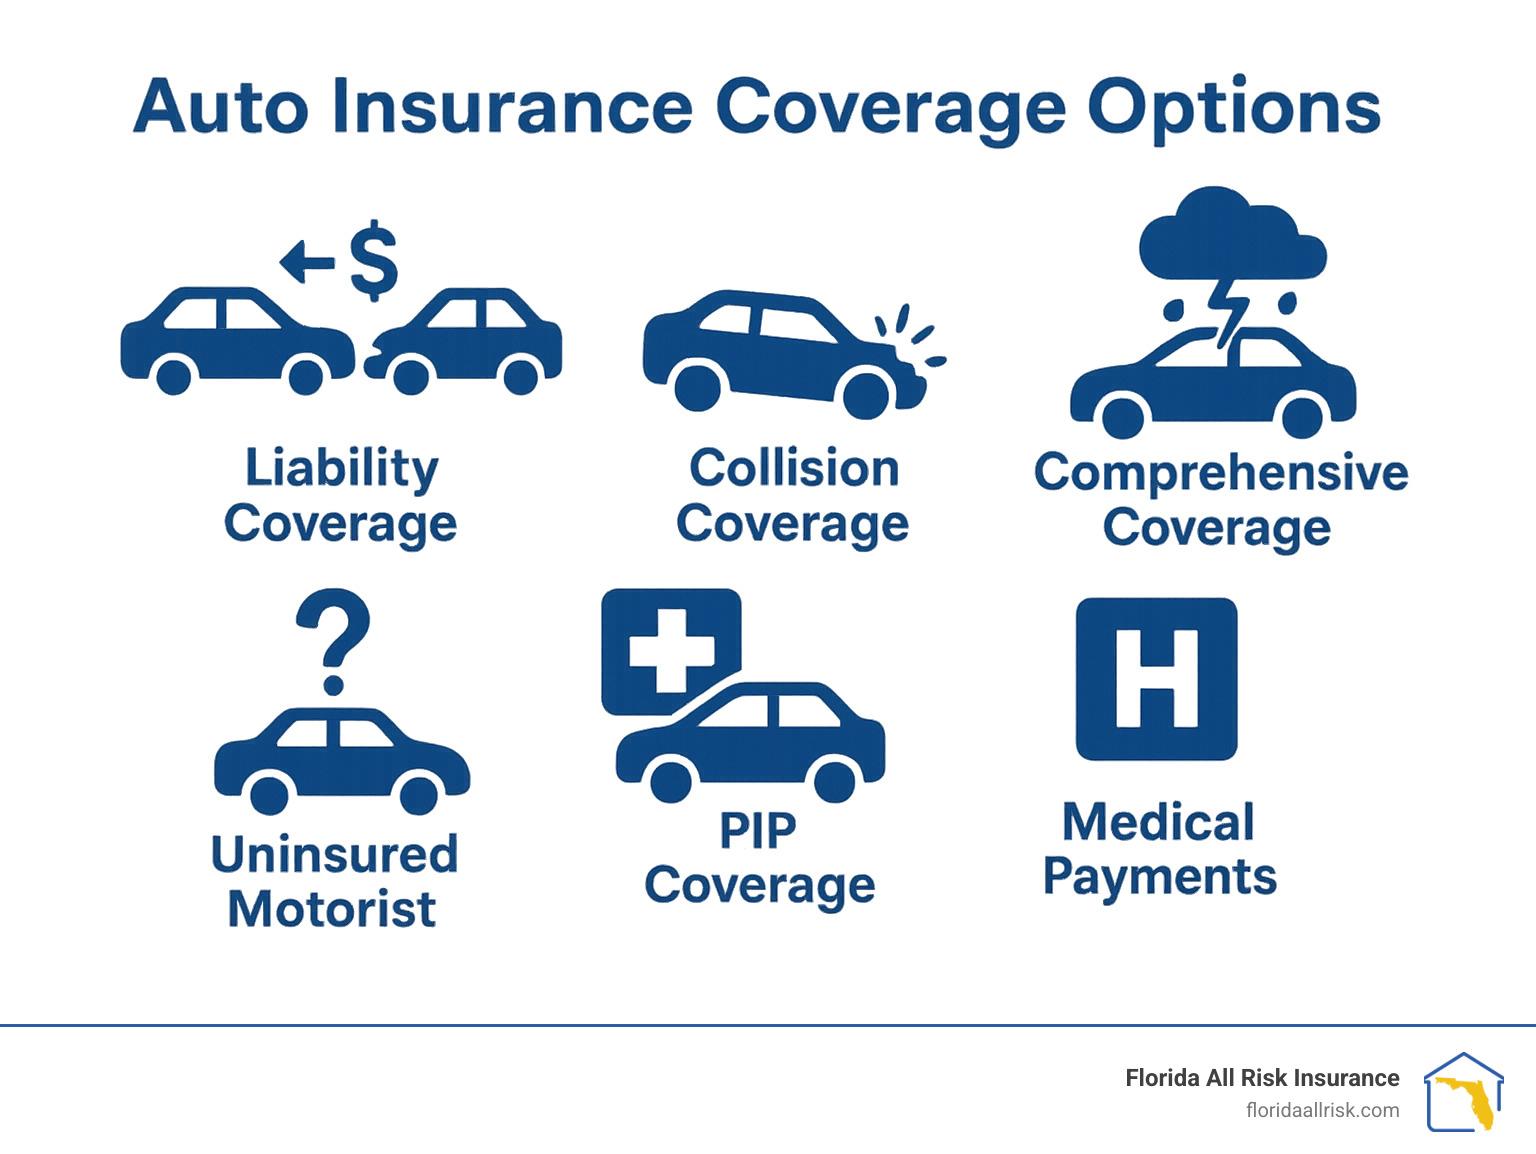
Standard liability and collision are often not enough. For those living in the 75043 zip code, specific endorsements provide necessary peace of mind.
Uninsured/Underinsured Motorist (UM/UIM)
Texas has a high rate of uninsured drivers. If you are hit by someone without insurance on a road like Broadway Blvd or Centerville Rd, UM/UIM coverage pays for your medical bills and car repairs. In 2026, this is considered an "essential" rather than an "optional" add-on by most financial advisors in the Dallas area.
Personal Injury Protection (PIP)
Texas law requires insurers to offer you at least $2,500 in PIP. While you can reject it in writing, PIP is invaluable because it pays out regardless of who was at fault. It covers medical expenses, 80% of lost wages, and even essential services (like house cleaning) if you are injured and cannot perform them.
Gap Insurance
If you are financing a vehicle in 2026, Gap insurance is vital. Because new cars depreciate quickly, you might owe $40,000 on a loan for a car that is only worth $34,000. If that car is totaled in a 75043 flood or accident, standard insurance only pays the $34,000. Gap insurance covers the $6,000 difference.
How to Lower Your Premiums in 75043
While regional rates are high, there are several localized strategies to reduce your monthly outlay without sacrificing necessary protection.
- Bundle with Homeowners Insurance: Many residents in 75043 own homes in neighborhoods like Shores of Eastern Hills or Mill Creek. Bundling home and auto with the same carrier is the single most effective way to secure a 15-25% discount.
- Increase Your Deductible: If you have an emergency fund, moving your deductible from $500 to $1,000 can significantly lower your premium. However, ensure you have the cash on hand, especially during hail season.
- Review Your Commute: If your job has shifted to remote or hybrid work since the start of 2026, update your mileage with your insurer. Lower annual mileage equals lower risk.
- Inquire About Group Discounts: Many employers in the Garland Independent School District or large local employers like Raytheon offer group insurance rates.
- Defensive Driving Courses: Completing a TEA-approved defensive driving course can provide a discount that lasts for three years, while also removing a ticket from your record if applicable.
The Claims Process in Garland
If an accident occurs in the 75043 area, the claims process follows standard Texas Department of Insurance (TDI) guidelines. However, local logistics matter.
- Police Reports: For accidents within Garland city limits, the Garland Police Department will typically handle the report. Ensure you obtain the incident number immediately.
- Repair Facilities: There are numerous high-quality body shops along the Lavon Dr and Forest Ln corridors. Most major insurers have "preferred" shops in the area that offer lifetime warranties on repairs, which can simplify the claims process.
- Appraisals: In the event of a total loss, ensure your adjuster is using "comparables" from the Dallas-Fort Worth market. A car in 75043 is often worth more than a similar model in a more rural part of the state due to local demand.
Navigating 2026 Regulatory Changes
As of 2026, the Texas Department of Insurance has implemented stricter transparency rules regarding how "non-weather related" claims impact future premiums. For 75043 residents, this means insurers must be clearer about why rates are rising. Additionally, new laws regarding "Right to Repair" have made it easier for Garland residents to choose their own repair parts rather than being forced to use cheaper, third-party components by their insurance company.
Frequently Asked Questions
What is the average cost of auto insurance in 75043?
In 2026, the average cost for a driver with a clean record is approximately $2,100 per year for full coverage. However, this varies significantly based on age, vehicle type, and exact location within the zip code. Those living closer to the high-traffic I-30 corridor may see slightly higher rates due to localized accident data.
Is it mandatory to have Uninsured Motorist coverage in Texas?
It is not mandatory, but Texas law requires insurance companies to offer it to you. To decline it, you must sign a written rejection. Given the number of motorists in the DFW metroplex driving without adequate insurance, it is highly recommended for all 75043 residents.
How does living near Lake Ray Hubbard affect my rates?
Living near a large body of water like Lake Ray Hubbard can occasionally impact rates due to increased risks of flooding during severe North Texas storms. Additionally, the recreational traffic near the lake on weekends can lead to a localized spike in minor collisions and "hit-and-run" incidents in parking areas.
Can I get a discount for my car's safety features?
Yes. In 2026, most insurers offer discounts for features such as automatic emergency braking, lane-keep assist, and advanced anti-theft systems. Since 75043 has a higher density of newer vehicles, these discounts are commonly applied to local policies.
What should I do if my insurance company denies a hail claim?
If your claim is denied or underpaid following a storm in Garland, you have the right to request an appraisal or file a complaint with the Texas Department of Insurance. Many 75043 residents use independent adjusters to ensure the damage to their vehicle's sensors and paint is fully accounted for.
Practical Recommendation for 75043 Residents
To ensure you are getting the best value in 2026, do not settle for a "set it and forget it" approach to auto insurance. Because the 75043 area is subject to rapid shifts in traffic patterns and weather-related risk, you should request new quotes at least once every 12 months. Start by comparing your current coverage against at least two national carriers and one Texas-based regional carrier. Prioritize a policy that includes Personal Injury Protection and Uninsured Motorist coverage to protect yourself against the specific urban risks of the Dallas-Fort Worth area.
Image Gallery
Select an image to open it in a new tab.
Zara El-Hashem
Sociocultural Dynamics and Academics Writer
