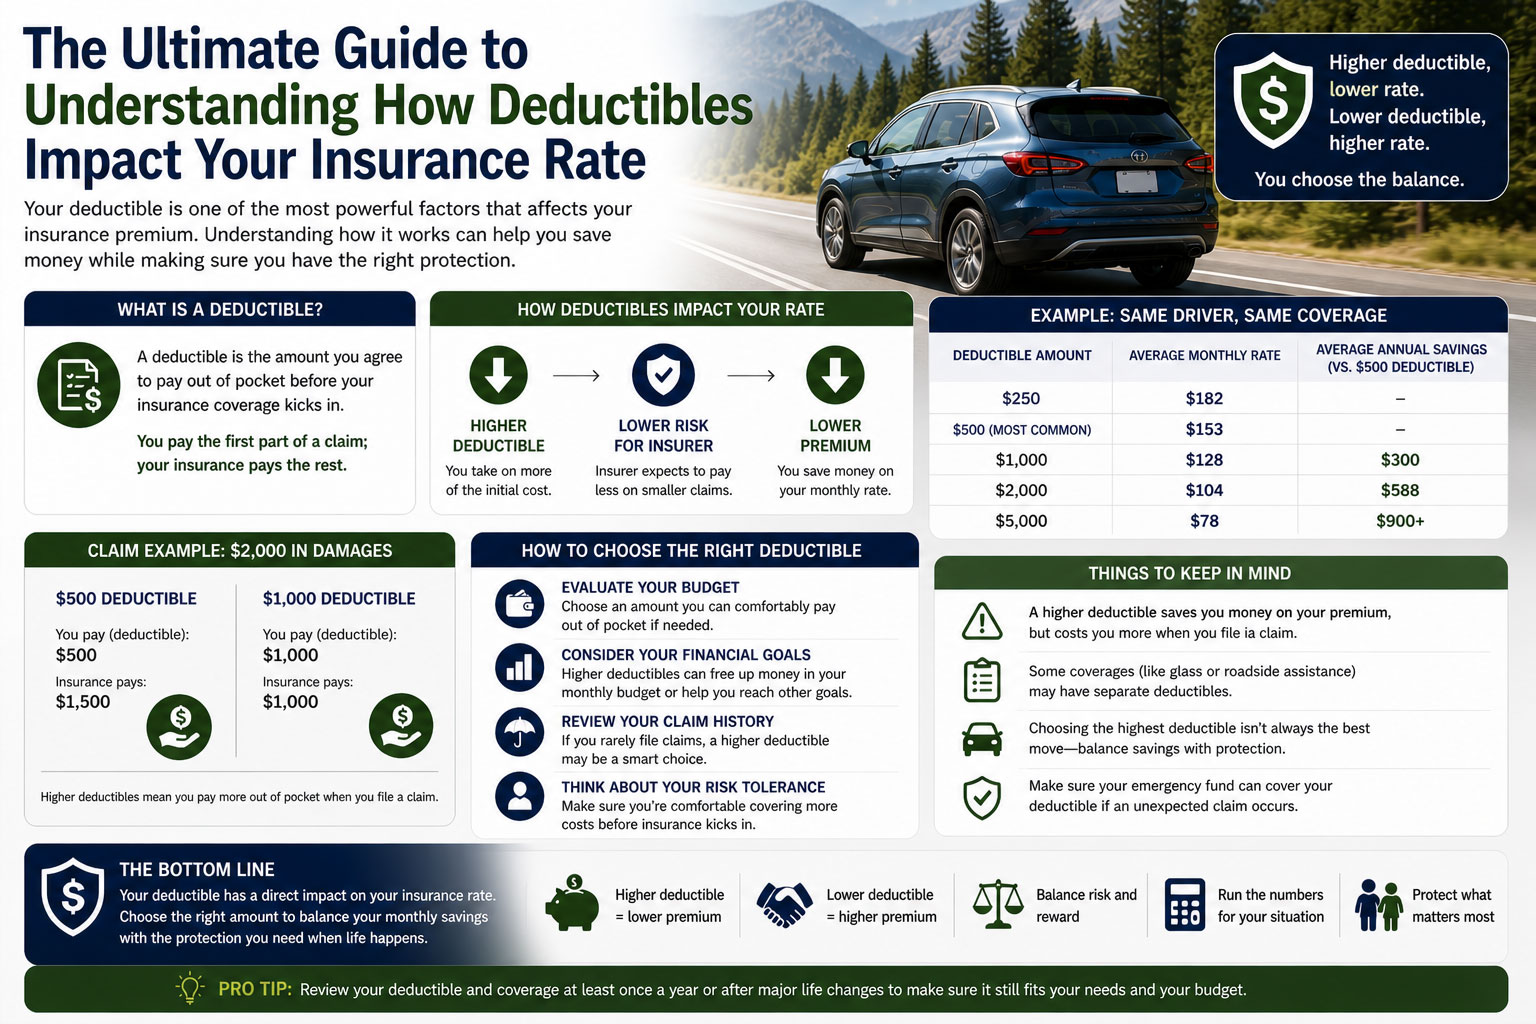
Opting for a higher deductible on your auto insurance policy in Killeen, Texas, is a proven strategy to lower your recurring premium costs. By assuming a larger portion of the financial risk during a claim, you signal to insurance providers that you are a lower-risk policyholder, which typically results in immediate monthly or annual savings.
The fundamental relationship between auto insurance premiums and deductibles is inverse: as the deductible increases, the premium decreases. For residents of Killeen, navigating the local market requires an understanding of how state-mandated coverage limits interact with voluntary deductible choices. Because insurance rates are highly individualized based on driving history, vehicle type, and credit profile, adjusting your deductible is one of the few levers you can pull to exert direct control over your insurance expenditure.
The Mechanics of Deductibles in Auto Insurance
A deductible is the amount of money you agree to pay out-of-pocket for covered losses before your insurance provider begins to pay for the remainder of a claim. This threshold applies primarily to comprehensive and collision coverage. It is vital to note that liability insurance—which covers damage or injuries you cause to others—does not carry a deductible.
When you choose a high deductible, you are essentially self-insuring against minor incidents. For example, if you have a $1,000 deductible and incur $1,200 in repair costs due to a minor fender-bender, the insurer covers $200. Conversely, if you have a $250 deductible, the insurer covers $950. Because the insurer is responsible for a smaller payout in the first scenario, they offer you a reduced rate for the policy.
Why Killeen Residents Should Consider Higher Deductibles
Killeen, situated in Bell County, presents a specific insurance landscape influenced by regional weather patterns and traffic density. Texas drivers are subject to specific minimum liability requirements, but voluntary coverages are where most residents find room for optimization.
- Long-term Savings: If you are a safe driver with a low probability of filing a claim, the accumulated savings from lower premiums over several years often outweigh the cost of a single high deductible in the event of an accident.
- Budgeting for Predictability: Monthly premiums are fixed expenses. By reducing them, you improve your monthly cash flow, provided you keep a dedicated emergency fund sufficient to cover the higher deductible amount.
- Vehicle Value Assessment: For older vehicles with lower market values, paying for low-deductible comprehensive and collision coverage may not be financially efficient. In some cases, the cost of the premiums combined with the low deductible could approach the total value of the vehicle over time.
Evaluating Your Financial Capacity
Before opting for a $1,000 or $2,000 deductible, you must honestly assess your financial liquidity. The strategy of choosing a high deductible is effective only if you possess the capital to cover that cost at a moment's notice.
If you have a high-deductible policy but cannot afford the out-of-pocket payment following an accident, you may find yourself unable to repair your vehicle, leaving it unusable or depreciating significantly in value. Before finalizing your policy changes for the 2026 coverage year, evaluate your emergency savings. A useful exercise is to maintain a "deductible fund" in a high-yield savings account, ensuring that you are prepared to meet your obligation without resorting to high-interest debt, such as credit cards.
Comparative Analysis: Deductible Impact on Premiums
The following table provides a conceptual look at how increasing your deductible typically impacts the annual premium cost. Note that actual savings vary based on individual risk profiles and the specific insurance company’s underwriting guidelines.
| Deductible Amount | Relative Premium Cost | Risk to Policyholder | Ideal Candidate |
|---|---|---|---|
| $250 | High | Minimal | Drivers prone to minor accidents |
| $500 | Moderate | Low | Average daily commuters |
| $1,000 | Low | Moderate | Safe drivers with emergency savings |
| $2,000+ | Very Low | High | Drivers with significant cash reserves |
Factors Beyond Deductibles Affecting Killeen Insurance Rates
While deductibles are a powerful tool for cost reduction, they are not the only variable influencing your total premium. In Killeen, your insurance rate is also shaped by:
- Driving Record: Traffic violations, moving citations, and previous at-fault accidents remain the most significant drivers of rate increases, regardless of your deductible choice.
- Credit-Based Insurance Score: In Texas, insurance companies may use credit information to determine premiums. Maintaining a healthy credit profile can unlock lower base rates.
- Vehicle Usage and Location: Where you park your vehicle, your annual mileage, and the specific safety features of your car (such as anti-theft systems or advanced driver-assistance features) influence the underlying risk assessment.
- Discounts: Always inquire about multi-policy bundles (e.g., combining auto and renters insurance), safe driver discounts, or student discounts, which can be applied alongside a high-deductible strategy.
Common Mistakes to Avoid
A common error among drivers is choosing the highest possible deductible simply to reach the lowest possible monthly rate without considering the long-term impact. If your financial situation changes—for instance, if you experience a temporary job loss or an unexpected medical bill—a high deductible can become a financial trap.
Another frequent mistake is failing to review your policy annually. In 2026, insurance markets are dynamic. You should revisit your policy every year, or after any major life event, to ensure that the balance between your monthly premium and your deductible still aligns with your current financial reality and risk appetite.
Steps to Optimize Your Insurance Strategy
To successfully implement a high-deductible strategy in Killeen, follow this systematic approach:
- Assess Your Current Policy: Request your current declarations page. Note your existing deductibles and ensure you understand the difference between collision and comprehensive deductibles.
- Determine Your "Emergency" Threshold: Calculate how much you can realistically pay out-of-pocket in the event of an accident without compromising your other financial obligations.
- Request Quotes: Contact your current provider and at least two competitors for updated quotes using higher deductible tiers. Ask them specifically, "How much will my premium decrease if I raise my collision deductible to $1,000?"
- Confirm Financial Readiness: Ensure you have enough liquidity in a savings account to cover the new deductible amount.
- Review and Update: Update your policy if the savings justify the increase in your out-of-pocket risk. Set a calendar reminder for six months or a year later to reassess.
Legal and Insurance Requirements in Texas
It is important to remember that Texas law mandates minimum liability insurance. The current requirement is known as "30/60/25" coverage:
- $30,000 for bodily injury per person.
- $60,000 for total bodily injury per accident.
- $25,000 for property damage per accident.
Increasing your deductible does not affect these liability limits. Liability insurance is essential for legal compliance and financial protection against lawsuits. Always prioritize maintaining adequate liability limits before attempting to cut costs by raising deductibles on physical damage coverage.
Frequently Asked Questions
Does a higher deductible affect my liability insurance? No. Deductibles only apply to your own vehicle's repair or replacement costs through collision or comprehensive coverage. Liability coverage, which pays for damage to others, does not have a deductible.
Is it worth having a $2,000 deductible if I drive an older car? It depends on the value of the vehicle. If the cost of the insurance premiums over two or three years is high relative to the car's actual cash value, a high deductible might be appropriate. However, if the car is only worth $3,000, paying a $2,000 deductible might leave you with very little benefit from an insurance claim.
Can I change my deductible at any time? Yes, you can generally change your deductible at any time during your policy term. However, keep in mind that some insurers may restrict changes if a claim is already pending.
Do insurance companies in Killeen provide discounts for high deductibles? Yes, they do. While it is technically a rate adjustment rather than a "discount" in the traditional sense, the reduction in premium is guaranteed by the structure of the policy.
What happens if I have an accident and cannot pay the deductible? If you cannot pay the deductible, the body shop may not release your car, or the insurance company may subtract the deductible from the total claim payout. In the latter case, you would receive less money to pay for the repairs, which could result in a shortfall.
Recommendations for Your Next Steps
If you are currently paying a low deductible, such as $250 or $500, and you have built a sufficient emergency savings fund, the most practical next step is to request a quote adjustment from your current insurer. Ask for a comparison between your current premium and the premium cost for a $1,000 deductible.
If the annual savings exceed $150–$200, it is likely worth making the change. Direct the money saved from your monthly premiums into a separate, high-interest savings account. By doing this, you are effectively self-insuring the difference between your old deductible and your new one, while simultaneously benefiting from lower monthly overhead. Always verify that any changes to your policy do not lower your liability limits below the Texas state minimums, as protecting your assets from liability is a higher priority than lowering your out-of-pocket costs for vehicle repairs.
Image Gallery
Select an image to open it in a new tab.
Mateo Castillo
Decentralized Finance and E-Payments Strategist
