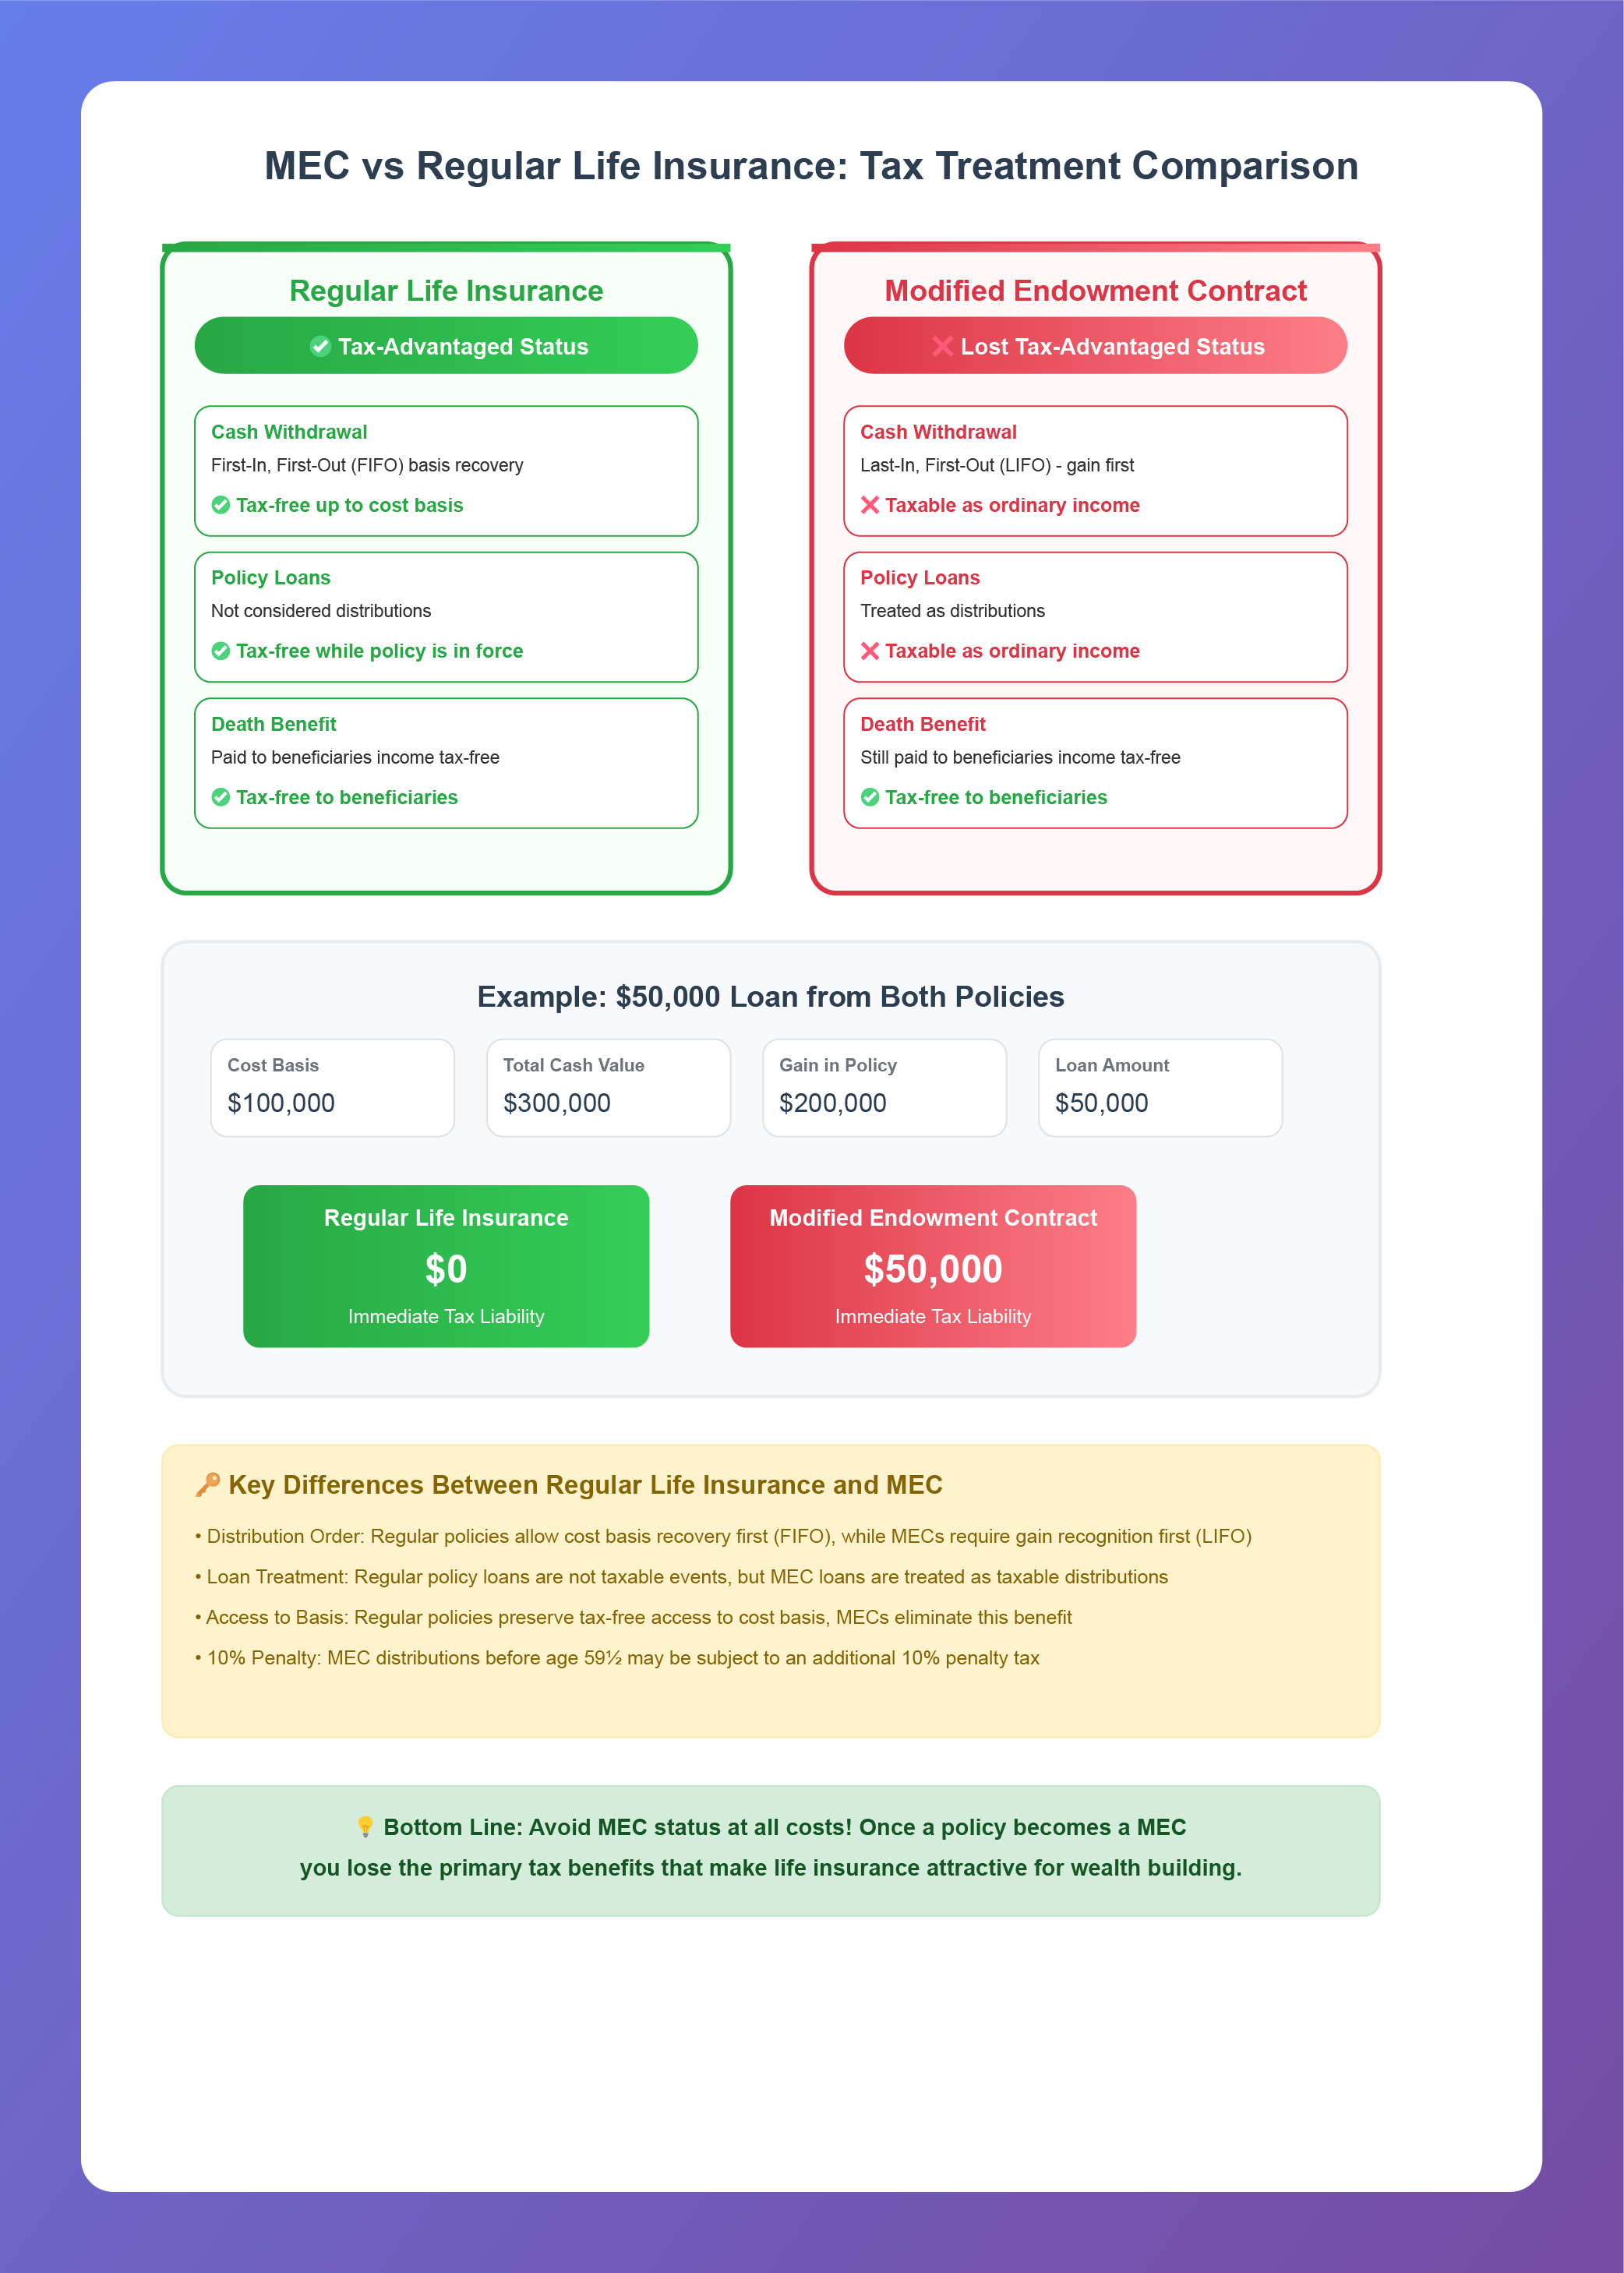
To set up life insurance to pay estate tax, you must establish an Irrevocable Life Insurance Trust (ILIT) to own the policy. This structure prevents the death benefit from being included in your taxable estate. Upon your passing, the trust receives the tax-free proceeds and provides liquidity to your estate through asset purchases or loans to cover tax liabilities.
As we move through 2026, the landscape of estate planning has shifted significantly. The expiration of the high federal gift and estate tax exemptions at the end of 2025 has brought thousands of additional families into the "taxable estate" bracket. For these individuals, the primary challenge is not just the tax amount itself, but the liquidity required to pay it. The IRS generally demands payment in cash within nine months of death. If your wealth is tied up in real estate, private business interests, or illiquid investments, your heirs may be forced to sell assets at a steep discount to meet this deadline.
Strategically structured life insurance offers a mathematical and legal solution to this "liquidity squeeze." By using a specialized trust, you can ensure that the insurance proceeds are available to the executor exactly when they are needed, without increasing the very tax bill you are trying to pay.
The Critical Role of the Irrevocable Life Insurance Trust (ILIT)
The most common mistake in estate planning is owning a life insurance policy in your own name. While life insurance death benefits are generally income tax-free, they are not estate tax-free if you own the policy or hold "incidents of ownership" at the time of your death. Under Internal Revenue Code Section 2042, if you have the right to change beneficiaries, borrow against the cash value, or cancel the policy, the entire death benefit is added to your gross estate, potentially triggering a 40% federal tax on those proceeds.
To avoid this, you must use an Irrevocable Life Insurance Trust (ILIT). An ILIT is a legal entity designed specifically to own and manage life insurance policies. Because the trust—not you—owns the policy, the proceeds do not count toward your taxable estate.
How the ILIT Provides Liquidity
An ILIT cannot legally be required to pay the estate taxes of the decedent, as that would imply the decedent still had control over the funds. Instead, the trust is drafted with "permissive" language. Upon the insured’s death, the trustee receives the insurance check and is authorized to either:
- Purchase assets from the estate: The trust buys illiquid assets (like shares in a family business or a piece of real estate) at fair market value. The estate gets the cash to pay the IRS, and the heirs keep the assets within the trust structure.
- Loan money to the estate: The trust provides a low-interest loan to the estate, providing the necessary cash for the tax bill while keeping the assets intact.
Step-by-Step Process for Setting Up the Strategy
Setting up this arrangement requires coordination between legal, financial, and tax professionals. In 2026, with the lower exemption levels, it is vital to begin this process early to account for the "Three-Year Rule" (IRC Section 2035), which states that if you transfer an existing policy into a trust and die within three years, the proceeds are still included in your estate.
1. Estate Valuation and Tax Projection
Before purchasing insurance, work with a tax professional to estimate your projected estate tax liability. As of 2026, the federal exemption has reverted to approximately $7 million per individual (adjusted for inflation from the 2011 base), down from the $13 million+ levels seen in previous years. You must also account for state-level estate or inheritance taxes, which often have much lower thresholds (e.g., $1 million to $5 million depending on the jurisdiction).
2. Drafting the Trust Document
Engage an estate planning attorney to draft the ILIT. The document must be irrevocable, meaning once it is signed, you cannot easily change its terms or dissolve it. You must appoint a trustee—someone other than yourself—to manage the trust. This can be a family member, a professional advisor, or a corporate trustee.
3. Applying for the Insurance Policy
The trustee should be the one to apply for the life insurance policy. To ensure the "incidents of ownership" rules are never triggered, the trust should be the original applicant, owner, and beneficiary. If you transfer an existing policy to the trust, the three-year lookback rule applies; however, if the trust buys a new policy directly, the proceeds are excluded from your estate from day one.
4. Funding the Trust via Gift Tax Exclusions
Since the trust is a separate entity, it needs money to pay the insurance premiums. You provide these funds by making annual gifts to the trust. In 2026, the annual gift tax exclusion is approximately $19,000 per recipient (subject to final inflation adjustments). To ensure these gifts qualify for the exclusion (rather than counting against your lifetime limit), the trust must include Crummey Powers.
5. Managing Crummey Notices
A Crummey Power gives the trust beneficiaries a limited window (usually 30 days) to withdraw the gifted funds. Even if they choose not to withdraw the money—which is the expectation—the right to withdraw it makes the gift a "present interest," qualifying it for the annual exclusion. The trustee must send formal written notices to beneficiaries every time you fund a premium payment. Failure to maintain these records can lead to an IRS audit and the loss of tax benefits.

Choosing the Right Policy Type for Estate Tax
Not all life insurance is suitable for estate tax planning. Because the goal is to provide a guaranteed sum at an unknown future date, "permanent" insurance is required. Term insurance is generally avoided because it may expire before the insured dies, leaving the estate without liquidity.
| Policy Type | Best Suited For | Pros | Cons |
|---|---|---|---|
| Survivorship Universal Life (SUL) | Married couples | Lower premiums than two individual policies; pays out only when the second spouse dies. | No death benefit provided when the first spouse dies. |
| Whole Life | Maximum Certainty | Guaranteed death benefit and fixed premiums; builds cash value. | Highest premium costs; less flexibility in payment timing. |
| Guaranteed Universal Life (GUL) | Pure Liquidity | Lower cost than whole life; focuses on the death benefit rather than cash accumulation. | Little to no cash value; if premiums are missed, the policy may lapse. |
| Variable Universal Life (VUL) | High Net Worth / Growth | Allows investment of cash value in market sub-accounts. | Market risk; if investments perform poorly, premiums may need to increase. |
The "Second-to-Die" Advantage
For married couples, Survivorship (Second-to-Die) Life Insurance is the gold standard for estate tax planning. Federal law allows an unlimited marital deduction, meaning no estate tax is typically due when the first spouse dies (provided the survivor is a U.S. citizen). The tax bill arrives only after the second spouse passes. A survivorship policy mirrors this timeline perfectly and is generally significantly cheaper than buying two separate policies because the underwriting covers two lives, and the payout is deferred.
Avoiding Common Pitfalls and "Incidents of Ownership"
The IRS scrutinizes ILITs closely. To ensure your life insurance remains outside your taxable estate, you must avoid these specific errors:
- Paying Premiums Directly: Never pay the insurance company from your personal bank account. You must gift the money to the trust, and the trustee must pay the premium from a trust-owned account.
- Acting as Trustee: If you are the trustee of your own ILIT, you hold "incidents of ownership." You must remain independent of the trust management.
- Borrowing from the Policy: You cannot take loans from the cash value of a policy owned by an ILIT for personal use.
- Improper Beneficiary Designations: The trust must be the beneficiary. If the proceeds are paid to your "estate," they become part of the probate process and are subject to estate taxes.
Professional Requirements and Ongoing Costs
Setting up this strategy is not a one-time event; it is an ongoing management commitment.
- Legal Fees: Expect to pay between $3,000 and $10,000 for the creation of a high-quality ILIT, depending on complexity.
- Trustee Fees: If you use a corporate trustee (like a bank’s trust department), they will charge an annual fee, often a percentage of assets or a flat administrative fee.
- Accounting: The trust may need to file an annual income tax return (Form 1041) if it generates income, although many ILITs are "grantor trusts" for income tax purposes, simplifying the filing.
- Premium Financing: For extremely large estates (e.g., $50 million+), some individuals use premium financing—borrowing the funds for premiums from a third-party lender—to avoid using up their gift tax exclusions too quickly. This adds significant complexity and interest-rate risk.
Frequently Asked Questions
Can I change the beneficiaries of my ILIT later?
Because the trust is irrevocable, you generally cannot change the beneficiaries yourself. However, you can give the trustee "power of appointment" or use a "trust protector" who has the limited authority to make changes based on specific future circumstances, such as the birth of a grandchild or a beneficiary's legal issues.
What happens if the estate tax laws change again?
Estate tax laws are highly volatile. This is why many ILITs include "flexible drafting" or "decanting" provisions. Decanting allows a trustee to move assets from an old, outdated trust into a new trust with more favorable terms, provided it complies with state law.
Is the death benefit of the life insurance taxable to the trust?
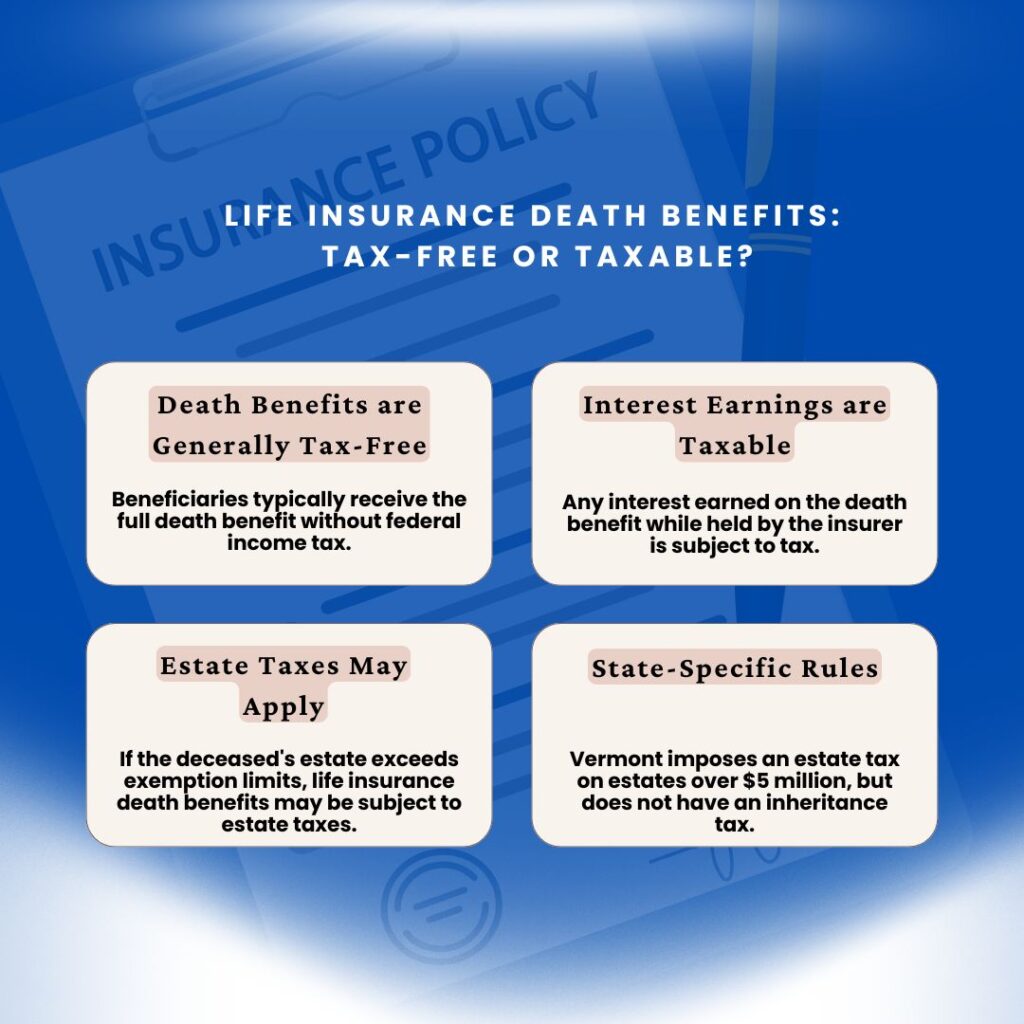
No. Under Section 101(a) of the Internal Revenue Code, life insurance death benefits are generally received income-tax-free by the beneficiary (in this case, the ILIT). This provides the "full" dollar value of the policy to cover the tax liability.
Can I use term insurance if I'm on a budget?
While technically possible, it is risky. If you outlive the 20 or 30-year term, the policy will disappear, and you may be uninsurable at that age. If the estate tax is a permanent problem, it requires a permanent solution. Some people use "Convertible Term" which allows them to switch to a permanent policy later without a new medical exam.
What is the "Three-Year Rule" for existing policies?
If you currently own a policy and transfer it into an ILIT today, and you pass away within three years of that transfer, the IRS will ignore the trust and include the proceeds in your taxable estate. This is why it is often better to have the trust buy a new policy or to plan well in advance of health issues.
Final Recommendation
As of 2026, the reduction in the federal estate tax exemption makes the "Insurance-in-an-ILIT" strategy a necessity for more families than ever before. To implement this correctly, your first step should be a comprehensive liquidity analysis. Do not guess at your estate’s value; get a formal appraisal of business interests and real estate. Once you know your projected tax gap, hire an experienced estate planning attorney to draft the ILIT before you apply for insurance. This ensures the trust is the original owner, bypassing the three-year lookback rule and securing your family's legacy against forced asset liquidations.
Image Gallery
Select an image to open it in a new tab.
Ingrid Bjornson
Global Cyber Policy and Regulation Analyst
