
Employer-provided life insurance typically costs businesses between $0.20 and $0.50 per $1,000 of coverage per month for basic group term policies, making it a highly affordable benefit. However, total expenses vary significantly based on company size, employee demographics, coverage amounts, and whether the plan includes voluntary add-ons or permanent policy options.
Navigating the landscape of employee benefits requires a careful balance between financial stewardship and competitive workforce attraction. Among the various perks modern companies offer, group life insurance stands out as a foundational pillar of comprehensive compensation packages. Yet, decision-makers often struggle to calculate the actual financial commitment involved. Understanding the underlying pricing structures, carrier calculations, and total cost of ownership allows organizations to budget accurately while providing meaningful security to their teams.
The Fundamentals of Employer-Provided Life Insurance
Group life insurance is a single contract that provides coverage to an entire group of people, typically the employees of a specific company. Unlike individual policies that require extensive medical underwriting and individual medical exams, group plans assess risk across the entire collective. This fundamental difference alters how pricing is determined and who bears the financial burden.
In most scenarios, employers purchase basic group term life insurance. Term insurance provides financial protection for a specified period—usually while the employee remains active with the company. If an employee passes away during the term, their designated beneficiaries receive a predetermined payout, known as a death benefit. Because these policies do not build cash value and expire when employment ends or the group contract terminates, the administrative overhead and underlying costs remain relatively low.
How Underwriting Differs from Individual Policies
Understanding the cost mechanics requires examining how insurers calculate risk for groups versus individuals. For individual life insurance, an underwriter evaluates an applicant's exact age, personal medical history, family medical history, driving record, and lifestyle habits like smoking.
Group life insurance, by contrast, relies on group underwriting. Insurers look at macroscopic data:
- The average age of the workforce.
- The ratio of male to female employees (since actuarial tables differ by gender).
- The industry sector and associated occupational hazards.
- The geographic location of the business operations.
By spreading risk across dozens, hundreds, or thousands of workers, insurers mitigate the impact of high-risk individuals. Consequently, workers with pre-existing medical conditions cannot be denied basic group coverage, and they receive the same baseline rates as their healthier colleagues.
Breaking Down the Costs: Who Pays and How Much?
The financial outlay for employer-sponsored life insurance depends heavily on the funding model chosen by the organization. Costs can be fully employer-paid, shared through cost-sharing arrangements, or entirely employee-funded via voluntary programs.
Employer-Paid (Non-Contributory) Plans
In a non-contributory plan, the employer covers 100% of the premium for a baseline amount of coverage, such as a flat $25,000, $50,000, or an amount equal to one times the employee’s annual salary.
- Average Cost: For a standard group term policy, employers generally pay between $2.00 and $6.00 per employee, per month, for a $50,000 death benefit.
- Perceived Value: This approach maximizes employee participation because enrollment is automatic, serving as a powerful recruitment and retention tool.
Employee-Paid (Contributory or Voluntary) Plans
Many organizations offer basic coverage paid by the company, but allow employees to purchase supplemental or voluntary life insurance through payroll deductions.
- Average Cost: The employee pays the full premium, which is calculated based on age brackets (age-banded rates). For example, a 30-year-old might pay pennies per thousand dollars of coverage, while a 60-year-old will face significantly higher rates due to actuarial mortality curves.
- Administrative Burden: While the employer incurs little to no direct cost for the supplemental coverage, the human resources and payroll departments must manage accurate deductions and compliance.
| Plan Type | Premium Responsibility | Typical Cost Structure | Primary Benefit |
|---|---|---|---|
| Basic Employer-Paid | 100% Employer | Flat rate per $1,000 of coverage; low monthly per-employee cost. | High participation, strong recruitment incentive. |
| Voluntary Supplemental | 100% Employee | Age-banded rates increasing in cost as workers age. | Customizable coverage levels without employer expense. |
| Shared Cost (Contributory) | Split between Employer/Employee | Subsidized base rate with optional employee-paid add-ons. | Balanced budget control with flexible employee options. |
Key Factors That Influence Group Life Insurance Pricing
While average benchmarks provide a helpful starting point, every business receives a customized quote from insurance carriers. Several variables directly influence the final premium calculation.
Workforce Demographics
The age distribution of the company is the single most impactful pricing variable. An organization with a young, millennial-heavy workforce will command much lower group rates than a firm with an older demographic nearing retirement age. Insurers evaluate the overall mortality risk of the aggregate pool; an older average age shifts that risk upward, increasing the base rate per thousand dollars of coverage.
Group Size and Participation Rates
Insurance carriers prefer larger groups because statistical predictability increases with scale. Small businesses (typically defined as having fewer than 10 to 50 employees) may face higher administrative fees or minimum premium requirements. Furthermore, insurers often mandate a minimum participation rate—such as 75% of eligible employees—for voluntary plans to prevent adverse selection, where only older or unhealthy workers enroll.
Coverage Multipliers and Flat Amounts
The generosity of the policy design directly dictates cost. Employers can structure benefits in several ways:
- Flat Benefit: Every employee receives the exact same death benefit, such as $25,000 or $50,000, regardless of salary. This is the easiest to budget for.
- Salary Multiplier: Coverage is tied to compensation, such as one, two, or three times the employee's annual salary. Higher-earning executives drive up the aggregate cost of this model.
- Class-Based Structure: Different tiers of employees (e.g., hourly workers versus executive management) receive different coverage multiples.
Industry Risk Classification
Insurers categorize businesses by industry codes. Office-based technology firms or professional services agencies represent low actuarial risk. Conversely, construction companies, manufacturing plants, and firms involving hazardous materials or heavy machinery face higher risk classifications, resulting in elevated premium rates.
Hidden Costs and Administrative Overhead
When evaluating employer life insurance cost, decision-makers must look beyond the monthly invoice from the insurance carrier. Total cost of ownership includes administrative time, legal compliance, and tax implications.
Human Resources and Payroll Integration
Managing enrollment changes, beneficiary updates, new hires, and terminations requires dedicated administrative effort. While modern benefits administration software automates much of this process, HR teams still spend valuable hours resolving discrepancies, managing billing reconciliations, and answering employee inquiries during open enrollment periods.
Tax Considerations and IRS Section 79
For employer-paid group term life insurance, the tax treatment is governed by Internal Revenue Service (IRS) Section 79.
- The $50,000 Threshold: Employers can deduct the cost of group term life insurance premiums for up to $50,000 of coverage per employee as a standard business expense. These premiums are generally tax-free to the employee.
- Imputed Income: If an employer provides more than $50,000 of group term life insurance coverage, the cost of coverage exceeding that threshold is considered taxable income to the employee. This amount, known as "imputed income," must be calculated using IRS Table I rates and added to the employee’s W-2 form for tax withholding purposes.
Comparing Group Life Insurance to Individual Policies
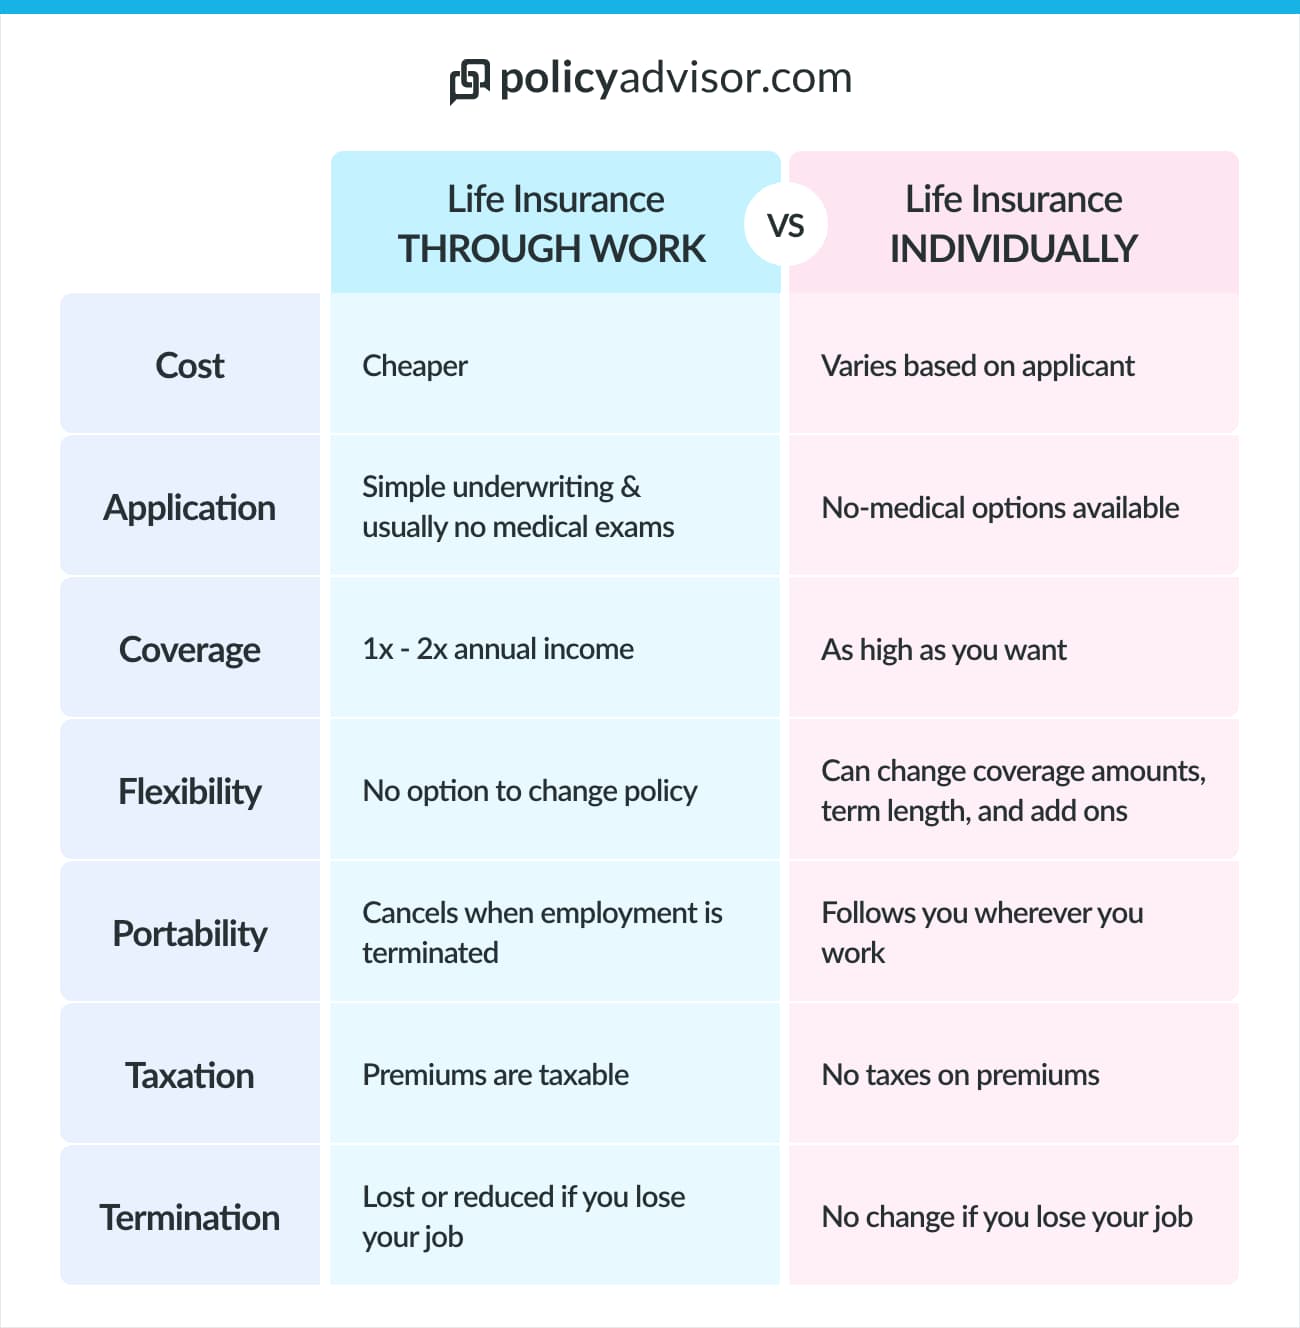
To understand why group life insurance is cost-effective, it helps to compare it directly to individual policies purchased on the open market.
| Feature | Group Life Insurance | Individual Life Insurance |
|---|---|---|
| Medical Exam Required | Rarely (for standard basic plans) | Frequently (blood, urine, vitals) |
| Cost to Employee | Often free or heavily discounted | Paid entirely out-of-pocket |
| Portability | Usually non-portable | Fully portable |
| Underwriting Basis | Collective group risk | Individual risk profile |
While group life insurance offers unmatched convenience and low cost, it comes with a major limitation: lack of portability. Most group term policies terminate when the employment relationship ends. While some plans offer a "conversion option"—allowing a departing employee to convert the group policy into an individual permanent policy without a medical exam—the resulting individual premiums are typically much higher.
Strategic Steps for Implementing or Reviewing a Policy
Organizations looking to establish a new group life insurance policy or audit an existing benefits package should follow a structured evaluation process.
- Assess Workforce Demographics: Analyze the age distribution, salary ranges, and occupational risk profiles of current employees to anticipate carrier pricing tiers.
- Determine Budgetary Limits: Decide whether the company will fund a flat basic benefit, a salary-multiplied benefit, or implement a voluntary employee-paid supplemental program.
- Request Competitive Quotes: Engage independent insurance brokers or group benefits consultants to solicit proposals from multiple top-tier insurance carriers.
- Evaluate Policy Riders: Review available riders, such as Accelerated Death Benefit (allowing terminally ill employees to access a portion of funds early) or Accidental Death and Dismemberment (AD&D) coverage.
- Ensure Compliance: Verify that plan documents comply with state insurance regulations, ERISA guidelines (if applicable), and IRS tax reporting requirements.
Frequently Asked Questions
Can an employee be denied basic employer life insurance due to poor health?
No. Standard basic group life insurance plans do not require medical underwriting or individual health exams for the baseline coverage amount. All eligible employees are accepted regardless of pre-existing medical conditions, provided they enroll during their designated initial eligibility window.
What happens to employer-provided life insurance when an employee quits or retires?
In most cases, group term life insurance coverage ends when employment terminates, typically on the last day of the month or employment. However, many group policies include a conversion privilege, allowing the former employee to convert their group coverage into an individual permanent life insurance policy within a specific timeframe without medical proof of insurability.
Are employer-paid life insurance premiums tax-deductible for the business?
Yes. Premiurs paid by an employer for group term life insurance up to $50,000 per employee are generally tax-deductible as ordinary and necessary business expenses. Amounts exceeding $50,000 are subject to specific tax rules and imputed income calculations.
Is voluntary supplemental life insurance more expensive than individual policies?
Not necessarily. Because group programs leverage collective purchasing power, voluntary supplemental rates are often competitive compared to retail individual policies, particularly for older workers or individuals with minor health complications who would otherwise face high individual rating tiers.
How does company size affect the cost of group life insurance?
Larger companies benefit from economies of scale and greater statistical predictability, which often translates to lower administrative fees and more favorable rate stabilization from carriers. Small businesses may face tighter underwriting constraints or higher minimum flat fees, though group pools provided through professional employer organizations (PEOs) can help mitigate these disparities.
Conclusion and Next Actions
Employer life insurance remains one of the most cost-effective ways to deliver meaningful financial security to a workforce. With basic policies often costing mere dollars per employee each month, the return on investment through improved recruitment, morale, and retention is substantial. Decision-makers should review their current census data, consult with a licensed independent benefits broker, and evaluate whether their current funding structure aligns with both organizational budgets and employee expectations.
Image Gallery
Select an image to open it in a new tab.

Vivian Cho
Executive IT and Emerging Technologies Reporter
