Comprehensive Guide to Capital Car Financing Options: Personal Auto Loans, Business Capital Leases, and Financing Structures

Capital car financing options encompass both consumer vehicle loans offered by major institutional lenders—such as Capital One Auto Finance—and commercial financing structures, including capital leases and fleet lines of credit for corporate vehicle acquisition. These financial products enable individual buyers and enterprise borrowers to purchase or lease vehicles through structured amortization, fixed or variable interest rates, and customized loan-to-value ratios.
Disclaimer
This guide is for educational and informational purposes only and does not constitute formal financial, legal, or tax advice. Auto financing terms, interest rates, and tax regulations (such as IRS Section 179 guidelines) vary based on individual credit profiles, business structures, and local jurisdictions. Consult a certified financial planner, legal professional, or CPA before entering into auto loan or capital lease agreements.
Defining Capital Car Financing Options
When navigating capital car financing, borrowers typically encounter two primary categories: institutional consumer auto financing and commercial capital vehicle financing. Understanding the distinction between these pathways ensures that individual buyers secure optimal interest rates while commercial entities structure vehicle acquisitions to optimize tax liabilities and operational cash flows.
Institutional consumer financing refers to vehicle loans underwritten by major commercial banks, credit unions, and specialized finance corporations. Providers such as Capital One Auto Finance operate largely through digital pre-qualification frameworks coupled with direct-to-dealer network integration. Borrowers secure pre-arranged capital based on creditworthiness, allowing them to shop participating dealership inventory with clear loan parameters before completing final contract execution at the dealership.
Commercial capital financing, by contrast, focuses on auto acquisition for business enterprises. This path relies heavily on capital leases (also designated as finance leases under financial accounting standards) and enterprise auto lines of credit. Under a capital lease, the vehicle is recognized on the business balance sheet as a capital asset, enabling the company to claim depreciation expenses and deduct interest payments while retaining an option to take full legal title at lease expiration.
| CONSUMER INSTITUTIONAL FINANCING (e.g., Capital One, Direct Auto Loans) | COMMERCIAL CAPITAL LEASING (Finance Leases, Enterprise) |
|---|---|
| • Pre-Qualification (Soft Credit Pull)• Direct Dealer Network Integration• Fixed Amortization Schedules | • Balance Sheet Asset• Depreciation & Interest• Bargain Purchase Options |
Consumer Institutional Auto Loans: Mechanics and Features
Consumer capital auto financing options allow buyers to purchase new vehicles, certified pre-owned (CPO) models, or used cars through financial institutions. Understanding how these institutional loan products operate helps buyers maximize their purchasing leverage and avoid predatory dealer markup strategies.
1. Pre-Qualification vs. Hard Approval
Most institutional capital lenders offer a digital pre-qualification process. Pre-qualification uses a soft credit inquiry, which evaluates a borrower’s credit profile without affecting their FICO score.
- Pre-Qualification: Yields an estimated loan amount, interest rate range, and maximum loan-to-value (LTV) limit. It allows buyers to preview payment scenarios across different vehicle price points.
- Hard Approval (Final Underwriting): Triggered when the buyer selects a specific vehicle at a participating dealership. The lender executes a hard credit pull, verifies income documentation, checks the vehicle’s book value (via Kelley Blue Book or NADA guides), and issues final binding terms.
2. Direct vs. Indirect Institutional Lending
Institutional capital financing operates through two primary distribution channels:
- Direct Lending: The applicant applies directly to a financial institution (bank, online lender, or credit union), receives a loan commitment, and brings that funding commitment to the dealership.
- Indirect Lending: The dealership acts as an intermediary. The buyer fills out a credit application at the finance and insurance (F&I) department, and the dealership submits the application across a network of wholesale lenders (including major entities like Capital One Auto Finance). The dealer may add an interest rate markup (often 1% to 2%) above the buy rate provided by the lender as compensation for arranging the loan.
3. Loan-to-Value (LTV) and Payment-to-Income (PTI) Caps
Capital lenders establish strict underwriting parameters to mitigate default risk:
- Loan-to-Value (LTV): The maximum percentage of the vehicle’s value that the lender will finance. Institutional lenders typically cap LTV between 100% and 125%. An LTV above 100% allows financing for additional costs, such as sales tax, title fees, extended warranties, and gap insurance. However, high LTVs increase the risk of entering a negative equity position ("being underwater").
- Payment-to-Income (PTI): Lenders require that the proposed monthly car payment does not exceed a designated percentage of the applicant’s gross monthly income, generally capping PTI between 15% and 20%.
Commercial Capital Vehicle Financing: Capital Leases and Fleet Loans
For enterprises, commercial capital car financing provides a framework to acquire individual vehicles or enterprise fleets while balancing liquidity and financial reporting requirements.
Standard Accounting Criteria for Capital Leases
Under Financial Accounting Standards Board (FASB) guidelines and Financial Accounting Standard ASC 842, a vehicle contract is classified as a capital lease (finance lease) if it satisfies any one of the following criteria:
- Ownership Transfer: Ownership of the vehicle automatically transfers to the lessee by the end of the lease term.
- Bargain Purchase Option: The lease agreement contains an option allowing the lessee to purchase the vehicle at a price significantly below fair market value (FMV).
- Lease Term Duration: The lease term covers 75% or more of the vehicle’s estimated economic useful life.
- Present Value of Payments: The present value of minimum lease payments equals or exceeds 90% of the fair market value of the vehicle at contract inception.
- Specialized Asset Status: The vehicle is customized to such a degree that it has no alternative practical use to the lessor at the end of the term.
Operational vs. Capital Lease Accounting Comparison
Unlike an operating lease, where monthly payments are reported purely as rental expenses, a capital lease treats the vehicle as a acquired capital asset. The business records the vehicle on its balance sheet under fixed assets, offset by a corresponding lease liability.
- Depreciation Expense: The enterprise depreciates the vehicle asset over its useful life using standard straight-line or accelerated depreciation methods.
- Interest Expense Deduction: The interest portion of each monthly lease payment is deductible as a corporate financing cost.
- Section 179 Tax Deductions: Under United States tax code guidelines, businesses utilizing capital vehicle financing may qualify for accelerated Section 179 expense deductions, allowing them to deduct the full or partial purchase price of eligible vehicles (such as trucks or SUVs with a Gross Vehicle Weight Rating over 6,000 lbs) in the year of acquisition.
Comprehensive Comparison of Capital Car Financing Options
The following table summarizes key operational, tax, ownership, and credit implications across standard capital auto financing options available to individual consumers and corporate entities.
| Financing Option | Ownership Structure | Primary Target Audience | Tax Treatment | Balance Sheet Impact | Typical Credit Requirement |
|---|---|---|---|---|---|
| Institutional Direct Auto Loan | Borrower holds title (lender maintains lien) | Individual consumers, sole proprietors | Interest deductible only for business use | Appears as personal or business debt liability | Fair to Super-Prime (FICO 620–850+) |
| Indirect Dealer Capital Loan | Borrower holds title (lender maintains lien) | Individual consumers seeking convenience | Standard depreciation/interest for business credit | Appears as personal or business debt liability | Subprime to Prime (FICO 500–850) |
| Commercial Capital Lease (Finance Lease) | Lessee takes ownership at term end or via purchase option | Small-to-medium enterprises, fleet operators | Depreciation and interest expense tax deductions | Vehicle listed as Asset; payments listed as Liability | Business Credit Profile + Personal Guarantee |
| Commercial Operating Lease | Lessor retains full title and ownership | Businesses desiring short lifecycle turnover | Monthly lease payments deducted as operational expense | Right-of-use asset recorded under modern accounting | Established Business Credit |
| Auto Refinancing Loan | New lender replaces original lienholder | Existing vehicle owners seeking lower APR | Same as primary auto loan structure | Replaces existing debt liability with new loan terms | Prime to Super-Prime preferred for rate reduction |
Prerequisites, Underwriting Requirements, and Tiered Rates
Lenders evaluate capital auto financing applications through risk-based pricing models. Understanding credit tier classifications helps applicants position themselves for competitive interest rates.
CREDIT TIER RANGE & TYPICAL UNDERWRITING OUTCOMES
- Super-Prime (780 - 850): Best APR, 0% Down Options, Max LTV (125%)
- Prime (660 - 779): Competitive Rates, Standard Terms
- Non-Prime (600 - 659): Stricter LTV Caps (100%), Proof of Income Required
- Subprime (< 600): Higher APR, Mandatory Down Payment, Stricter DTI
1. Consumer Underwriting Thresholds
- Credit Score Tiers:
- Super-Prime (780–850): Qualifies for baseline annual percentage rates (APR), zero-down-payment incentives, and extended term options (up to 72 or 84 months).
- Prime (660–779): Qualifies for competitive rates with minimal loan origination fees.
- Non-Prime / Subprime (< 600–659): Requires down payments (typically 10% to 20%), proof of income (pay stubs or W-2s), proof of residence, and stricter debt-to-income limits.
- Debt-to-Income (DTI) Ratio: Most institutional capital lenders require an applicant’s total monthly debt obligations (including housing, credit cards, and the proposed auto loan) to remain below 45% to 50% of gross monthly income.
- Employment and Income Verification: Lenders usually look for at least six months of continuous employment with the current employer or two years within the same line of work.
2. Commercial Credit Underwriting Requirements
When applying for commercial capital leases or fleet lines of credit, financial institutions assess the business entity directly:
- Business Documentation: Articles of Incorporation, Operating Agreements, corporate tax returns for the prior two fiscal years, and current profit and loss (P&L) statements.
- Commercial Credit Ratings: Lenders review business credit scores from agencies such as Dun & Bradstreet (PAYDEX score), Experian Commercial, or Equifax Small Business.
- Personal Guarantee: For small or mid-sized enterprises without established independent corporate credit histories, major owners (typically those holding 20% or more equity) must sign personal guarantees, making their personal credit profile part of the underwriting process.
Step-by-Step Application and Acquisition Workflow
To secure capital car financing efficiently, follow this structured roadmap:
CAPITAL FINANCING WORKFLOW
- Step 1: Financial & Credit Audit
- Check FICO/Business Credit, calculate DTI, set maximum budget.
- Step 2: Obtain Institutional Pre-Qualification
- Run soft-pull application with direct/capital lenders to lock target rates.
- Step 3: Inventory Matching & Vehicle Inspection
- Match loan parameters to qualifying dealership inventory; check book value.
- Step 4: Underwriting Submission & Document Verification
- Submit proof of income/tax returns, verify insurance coverage.
- Step 5: Final Underwriting & Lien Execution
- Sign note/lease agreement, finalize lienholder listing, take delivery.
Step 1: Conduct a Comprehensive Financial Audit
Calculate your total budget by examining monthly free cash flow rather than focusing solely on the monthly payment. Account for non-loan costs such as auto insurance premiums, state sales taxes, registration fees, and routine vehicle maintenance.
Step 2: Acquire Pre-Qualification
Apply for pre-qualification through institutional capital platforms or direct lenders. Secure your estimated APR and loan cap before entering a dealership showroom. This step eliminates high-pressure sales tactics surrounding monthly payment negotiations.
Step 3: Select Eligible Vehicles within Lender Constraints
Institutional lenders often enforce strict vehicle age and mileage restrictions. For instance, many capital financing programs will not fund vehicles that:
- Are older than 10 to 12 model years.
- Exceed 120,000 to 150,000 miles on the odometer.
- Possess branded, salvage, or rebuilt titles.
Ensure your chosen vehicle meets your lender's specific eligibility rules before negotiating the purchase price.
Step 4: Finalize Dealership Purchase Structure
Present your pre-qualification details to the F&I manager at a participating dealership. The dealership cross-checks the vehicle's Vehicle Identification Number (VIN) and exact invoice pricing against the lender’s automated underwriting portal to verify that the loan stays within authorized LTV limits.
Step 5: Execute Contract and Complete Lien Placement
Review the final truth-in-lending disclosure document (required under federal law). Pay close attention to:
- Annual Percentage Rate (APR): The total cost of credit expressed as a yearly rate.
- Finance Charge: The total dollar amount the credit will cost you over the full term.
- Amount Financed: The net amount of credit provided to you.
- Total of Payments: The total sum paid after completing all scheduled payments.
Once signed, the lender places a lien on the vehicle title, which remains active until the loan balance is paid in full.
Financial Strategies: Total Cost Optimization and Pitfalls to Avoid
Managing a vehicle loan involves more than securing an approval; it requires optimizing the loan structure over its entire lifecycle.
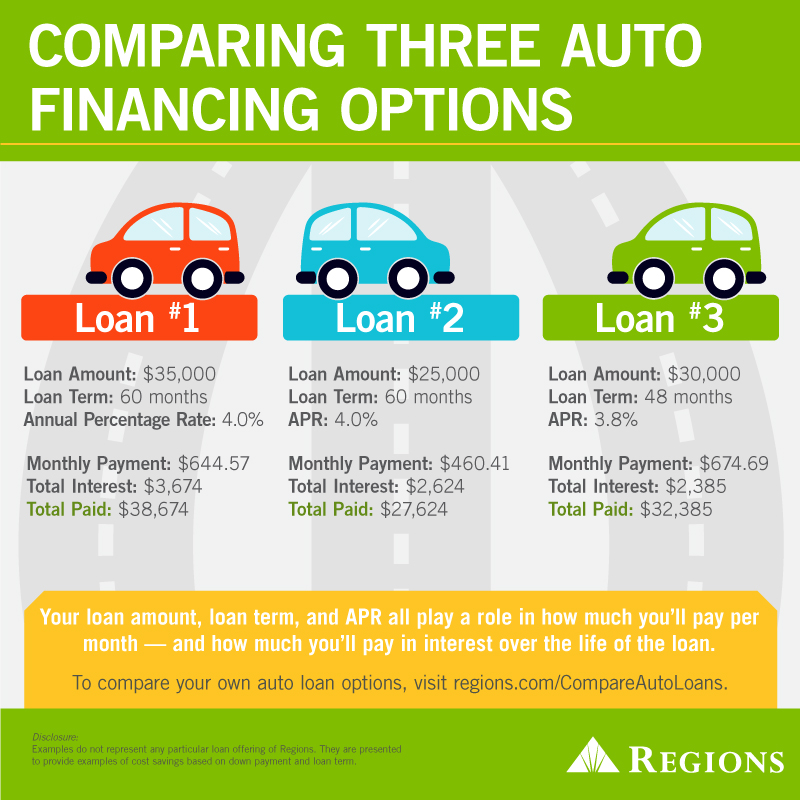
1. Loan Term Length vs. Total Interest Expenses
While extended loan terms (such as 72 or 84 months) reduce monthly payments, they significantly increase the total interest paid over the life of the loan. Furthermore, long terms keep the vehicle in a negative equity state for a longer period, as depreciation often outpaces principal reduction during the first three years.
$$\text{Total Loan Cost} = \text{Principal Amount} + \sum (\text{Monthly Interest Charges}) + \text{Origination Fees}$$
Choosing a shorter term (e.g., 48 to 60 months) increases monthly payments but cuts total interest costs and builds positive equity faster.
2. Strategic Down Payments
Making a down payment of at least 15% to 20% upfront helps offset immediate vehicle depreciation, lowers monthly obligations, and improves loan approval terms for non-prime applicants.
3. Avoiding Common Capital Financing Errors
- Rolling Negative Equity into New Loans: Transferring an unpaid balance from a trade-in vehicle into a new capital loan artificially inflates the new loan's LTV ratio. This can result in elevated interest rates and requirement for mandatory Gap insurance.
- Focusing Exclusively on Monthly Payments: Dealership F&I departments may offer longer loan terms to meet a targeted monthly payment, masking a higher overall purchase price and increased interest costs. Always evaluate the vehicle purchase price, interest rate, and term length independently.
- Overlooking Lease-End Capital Obligations: In commercial capital leases containing balloon payments or fixed purchase options, businesses must budget for the lump-sum capital payout required to acquire full title at contract termination.
Frequently Asked Questions
What is the difference between direct capital auto financing and dealership auto financing?
Direct capital financing involves securing a loan commitment directly from an institutional lender (such as a bank, credit union, or direct auto finance company) before visiting a vehicle seller. Dealership auto financing occurs when the dealer's F&I department submits your credit application to its network of third-party lenders. Direct financing gives you pre-arranged loan parameters before negotiating, whereas dealer financing offers convenience but may include interest rate markups added by the dealership.
Does applying for capital car financing pre-qualification affect my credit score?
Initial pre-qualification using capital auto portals typically relies on a soft credit pull, which does not impact your credit score. However, once you select a vehicle and finalize the loan application at the dealership, the lender performs a hard credit inquiry. A hard pull is recorded on your credit report and may cause a temporary drop of a few points in your overall score.
Can I secure commercial capital car financing for a new business without established corporate credit?
Yes. However, if your business lacks an established corporate credit history or sufficient operating revenues, institutional capital lenders usually require a personal guarantee from the business owner. The lender evaluates the owner's personal credit score, assets, and tax returns to underwrite the commercial vehicle loan or capital lease.
What happens if I want to pay off my capital auto loan early?
Most institutional auto loans are structured without prepayment penalties, allowing borrowers to pay off the principal balance early and reduce total interest expenses. However, you should inspect your loan contract's terms and disclosures to confirm that there are no prepayment penalty clauses or administrative payoff processing fees.
How does a commercial capital lease differ from a standard auto operating lease?
A commercial capital lease (finance lease) is structured like a funded asset purchase, transfering the risks and rewards of ownership to the lessee. The vehicle appears as a capital asset on the company’s balance sheet, allowing the enterprise to claim depreciation and interest deductions. By contrast, a standard operating lease functions like a long-term rental; the vehicle does not appear as a capital asset owned by the business, and monthly lease payments are reported directly as operational expenses.
Recommended Next Actions
To move forward with securing optimal capital car financing options:
- Pull Your Credit Profiles: Request free copies of your credit reports via AnnualCreditReport.com to check for inaccuracies before applying. For commercial applications, check your Dun & Bradstreet or Experian Commercial report.
- Determine Budget Parameters: Establish your total target purchase price based on a realistic down payment (15–20%) and a payment-to-income (PTI) ratio below 15%.
- Obtain Capital Pre-Qualifications: Submit soft-pull applications through institutional direct lenders or major auto finance portals to establish your baseline interest rate and maximum loan amount.
- Shop Network Inventory: Select eligible vehicles from authorized auto dealers that fit within your lender's LTV, age, and mileage guidelines.
- Review Truth-in-Lending Disclosures: Before signing, verify that the final APR, term length, total finance charges, and itemized fee lines match your pre-approval expectations.
Image Gallery
Select an image to open it in a new tab.


Lars Thomsen
Global Labor Markets and Economic Strategy Editor
