Can You Take Out Life Insurance on an Ex-Spouse? Requirements and Legal Guidelines
Yes, you can take out a life insurance policy on your ex-spouse, provided you can demonstrate a valid "insurable interest" and obtain their written consent. In 2026, insurance providers strictly require the insured person to participate in the application and underwriting process, meaning you cannot legally or practically secure a policy on an ex-spouse in secret.
Managing financial risks after a divorce often necessitates life insurance, particularly when there are ongoing financial obligations like child support or alimony. While the marriage has ended, the financial interdependence often continues for years, creating a legitimate need for a death benefit to replace lost income or support. Understanding the intersection of insurance law, divorce decrees, and underwriting requirements is essential for anyone looking to secure this type of coverage.
The Foundation of Insurable Interest
The primary legal hurdle to insuring an ex-spouse is the principle of insurable interest. Under insurance law in most jurisdictions, including the United States, United Kingdom, and Canada, you cannot buy insurance on someone else's life unless their death would cause you a direct financial loss. This doctrine exists to prevent "moral hazard"—the incentive to cause harm for financial gain—and to ensure that life insurance remains a tool for risk management rather than a form of gambling.
When you are married, insurable interest is generally assumed by the state of the relationship. However, once a divorce is finalized, that automatic assumption disappears. To take out a new policy on an ex-spouse in 2026, you must provide evidence of a continuing financial connection.
Common Examples of Insurable Interest Post-Divorce
- Child Support Obligations: If your ex-spouse pays child support, their death would result in a significant loss of income necessary to raise your children. This is the most widely accepted form of insurable interest.
- Alimony (Spousal Support): If you receive alimony, your financial stability is tied to your ex-spouse’s ability to generate income. A life insurance policy protects you if that income stream is cut short.
- Joint Debt and Mortgages: If you both remain on a mortgage or have significant shared business debts, the death of one party could leave the other solely responsible for the entire liability.
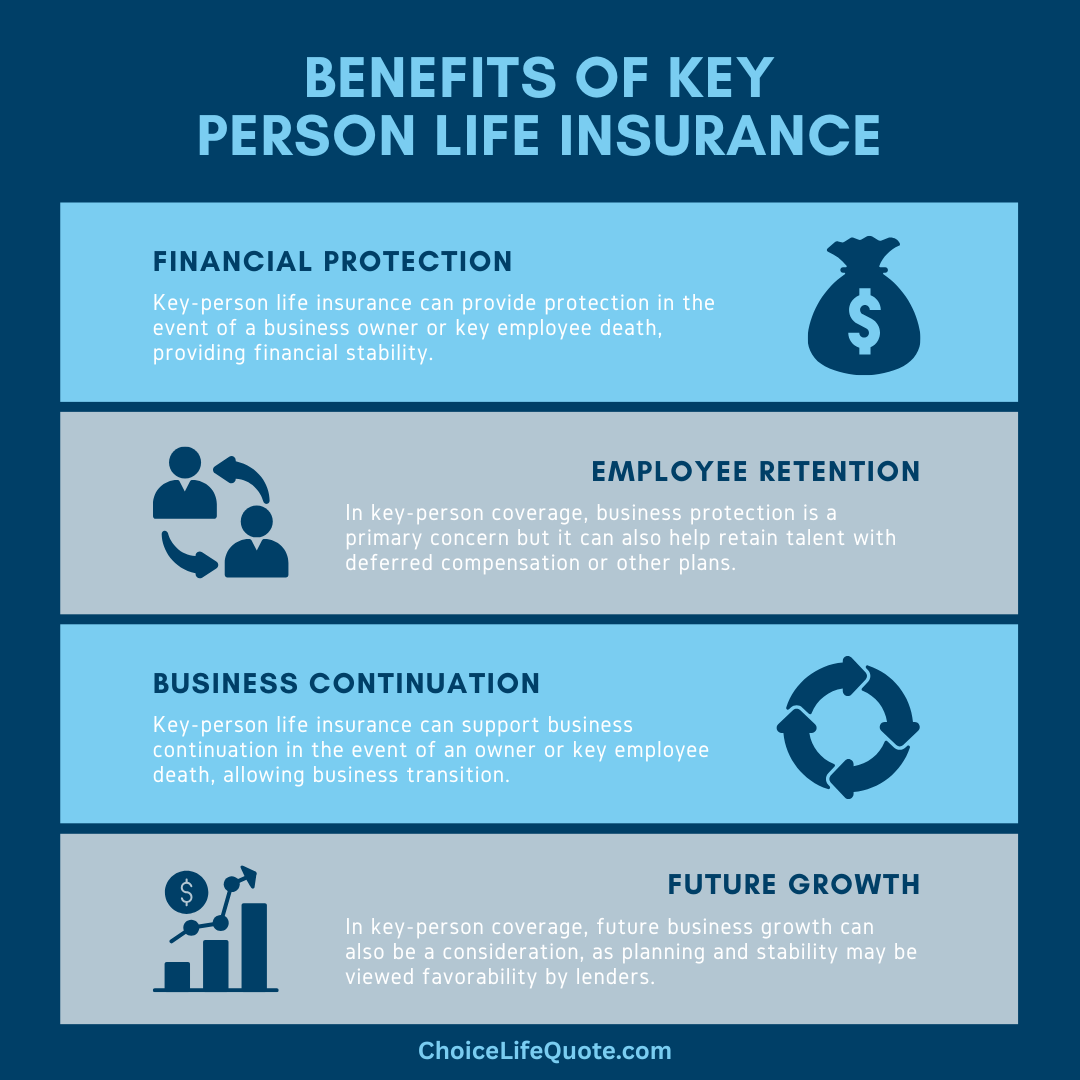
- Business Partnerships: If you and your ex-spouse continue to run a business together, the loss of a key partner justifies a "key person" life insurance policy.
Without one of these specific financial ties, most insurance companies will deny an application for a policy on an ex-spouse. The mere fact that they are the parent of your children is usually not enough; there must be a quantifiable financial obligation.
The Necessity of Consent and Cooperation
A common misconception is that a person can take out a policy on their ex-spouse "just in case" without the ex-spouse’s knowledge. This is legally impossible in 2026. Life insurance applications require the signature of the person being insured. Furthermore, the underwriting process almost always requires the insured to participate in a medical interview or provide access to their electronic health records.
The Role of the Signature
The ex-spouse must sign the application as the "proposed insured." By signing, they acknowledge that a policy is being taken out on their life and that you (the ex-spouse) will be the owner and/or beneficiary. Forcing or forging a signature is insurance fraud and carries severe legal penalties.
Medical Underwriting in 2026
Modern underwriting has become increasingly data-driven. While "no-exam" policies exist, they still require the insured's consent to pull data from the Medical Information Bureau (MIB), prescription drug databases, and motor vehicle records. If your ex-spouse refuses to authorize these checks, the insurance company cannot assess the risk and will not issue the policy.
Ownership vs. Beneficiary Status
When setting up life insurance on an ex-spouse, how the policy is structured is just as important as the coverage amount. There are two primary ways to handle this, and each has distinct implications for control and reliability.
1. You Own the Policy
In this scenario, you are the policyowner, and your ex-spouse is the insured. As the owner, you:
- Receive all premium notices directly.
- Are the only person who can change the beneficiary.
- Have the right to keep the policy in force even if your ex-spouse objects later (provided the policy was legally issued).
- Are responsible for paying the premiums.
Experts generally recommend this route. If your ex-spouse owns the policy and is supposed to name you as the beneficiary, they could stop paying the premiums or change the beneficiary without your knowledge, leaving you unprotected.
2. Your Ex-Spouse Owns the Policy
In some cases, a divorce decree may order the ex-spouse to maintain a policy and name you as the beneficiary. While this is common, it is riskier for the recipient. You must ensure the decree includes a "notice of lapse" provision, requiring the insurance company to notify you if a premium is missed. Without this, the policy could be cancelled for non-payment, and you might not find out until you attempt to make a claim after their death.
Court-Ordered Life Insurance
Many people seeking life insurance on an ex-spouse do so because it was mandated during the divorce proceedings. Family court judges frequently order the "obligor" (the person paying support) to maintain life insurance to secure their financial obligations.
As of 2026, standard legal practice involves including specific language in the Separation Agreement or Divorce Decree regarding:
- The required face amount of the policy (often tied to the total remaining support obligation).
- The duration of the coverage (e.g., until the youngest child turns 18 or 21).
- The designation of the owner and beneficiary.
- Proof of coverage requirements (e.g., providing an annual certificate of insurance).
If your ex-spouse refuses to cooperate with the insurance application despite a court order, they may be held in contempt of court. In such cases, your attorney can file a motion to compel their cooperation or seek other legal remedies, such as a lien against their estate.
Determining the Right Type of Coverage
Not all life insurance policies are suitable for protecting post-divorce interests. The choice usually comes down to Term Life vs. Permanent Life insurance.
Term Life Insurance
Term insurance is the most common choice for securing child support or alimony. It provides coverage for a specific period (10, 15, 20, or 30 years). It is significantly cheaper than permanent insurance and can be timed to expire when the financial obligation ends—for instance, when child support payments cease or when a mortgage is paid off.
Permanent Life Insurance
Whole life or Universal life insurance stays in effect for the insured’s entire life, as long as premiums are paid. This might be appropriate if there is a lifelong alimony agreement or if there is a child with special needs who will require financial support long into adulthood. However, the higher cost of these policies often makes them less practical for most divorce situations.
| Feature | Term Life Insurance | Permanent Life (Whole/Universal) |
|---|---|---|
| Duration | Fixed period (e.g., 20 years) | Lifelong |
| Cost | Lower/Affordable | Higher |
| Cash Value | None | Builds over time |
| Best For | Child support, Alimony, Mortgages | Special needs trusts, Estate planning |
| 2026 Market Availability | High (Highly competitive rates) | Moderate (Complex structures) |
Financial and Tax Implications
The Internal Revenue Service (IRS) and other tax authorities have specific rules regarding life insurance proceeds. Generally, death benefits paid to a beneficiary are not considered taxable income. However, there are nuances when it relates to divorce.
If the premiums are paid by the person receiving alimony, they are not tax-deductible. If the court orders the payer to pay the premiums and the recipient owns the policy, those premium payments were historically sometimes treated as alimony (and thus deductible for the payer and taxable for the recipient), but tax law changes (such as the 2018 Tax Cuts and Jobs Act in the US) have largely removed the deductibility of alimony for newer divorces. It is crucial to consult with a tax professional regarding the specific treatment of premiums and proceeds in your jurisdiction.
Furthermore, if the death benefit is significantly higher than the actual financial loss (the remaining support obligation), the insurance company or the estate might challenge the payout, though this is rare if the policy was issued with proper consent and insurable interest established at the outset.
Common Obstacles and How to Overcome Them
Securing insurance on an ex-spouse is rarely a seamless process. Several hurdles can arise:
The Ex-Spouse is Uninsurable
If your ex-spouse has developed severe health issues since the divorce, they may be "uninsurable" or the premiums may be prohibitively expensive. If a court order required them to get insurance and they cannot, they may be required to set aside other assets (like a 401k or a house) in a trust to secure the support obligation.
The Ex-Spouse "Ghosts" the Medical Exam
Insurance companies in 2026 use automated scheduling, but the insured still needs to show up or answer the phone for a tele-interview. If they repeatedly miss appointments, the application will be closed. Consistent communication through legal channels is often the only way to ensure compliance.
Existing Policies
If your ex-spouse already has a policy from when you were married, check your state laws. Many states have "Revocation on Divorce" statutes that automatically remove an ex-spouse as a beneficiary upon divorce unless the divorce decree specifically states otherwise. You may need to have your ex-spouse sign a new beneficiary designation form post-divorce to ensure the policy remains valid for you.
Frequently Asked Questions
Can I take out a policy on my ex-spouse without them knowing?
No. In 2026, it is virtually impossible to take out a life insurance policy on an adult without their knowledge. They must sign the application, and the underwriting process requires their personal health data or a medical examination. Attempting to do so without consent is considered fraud.
Does remarrying affect my ability to insure my ex?
Usually, no. Your insurable interest is based on the financial obligations (like child support) that exist regardless of your marital status. If your ex-spouse remarries, they may want to take out additional insurance for their new family, but that does not invalidate your right to maintain a policy to protect your court-ordered support.
What happens if the child support ends?
If the insurable interest was based solely on child support, and that support obligation ends (e.g., the child reaches adulthood), you may no longer have a legal justification to maintain the policy in some jurisdictions. However, if you own the policy, many insurers will allow you to keep it as long as you continue paying the premiums, though you should verify this with your carrier.
Who should pay the premiums?
Ideally, the person receiving the support (the beneficiary) should pay the premiums. This ensures that you have full control over the policy's status. If you are worried about the cost, you can negotiate an increase in alimony or child support to cover the premium expenses.
Can I use an old policy we had during the marriage?
Yes, but you must update the paperwork. Most insurance companies require a post-divorce beneficiary confirmation to override state laws that might automatically disqualify an ex-spouse. Ensure the ownership is also transferred to the party who needs the protection.
Steps to Take Now
If you are currently navigating a divorce or have a finalized decree that mentions life insurance, follow these steps to secure your financial future:
- Review Your Decree: Ensure the legal language specifically names the amount, duration, and owner of the policy.
- Verify Existing Coverage: If your ex says they have a policy, demand a "Certificate of Insurance" or a copy of the policy to verify that you are actually the named beneficiary and that the policy is active.
- Apply for New Coverage Early: Don't wait until the divorce is final to start the application process, as underwriting can take several weeks.
- Consider Ownership: If possible, be the owner of the policy so you receive all billing and status updates directly from the insurance company.
- Consult Experts: Work with an insurance broker who understands divorce-related policies and a family law attorney to ensure the policy aligns with your legal rights.
Taking out life insurance on an ex-spouse is a standard and prudent financial move in 2026. By focusing on the requirements of insurable interest and securing the necessary consent, you can create a vital safety net for yourself and your children, ensuring that a tragedy does not result in financial ruin.
Image Gallery
Select an image to open it in a new tab.


Declan O'Connor
Higher Education and Campus Culture Reporter
