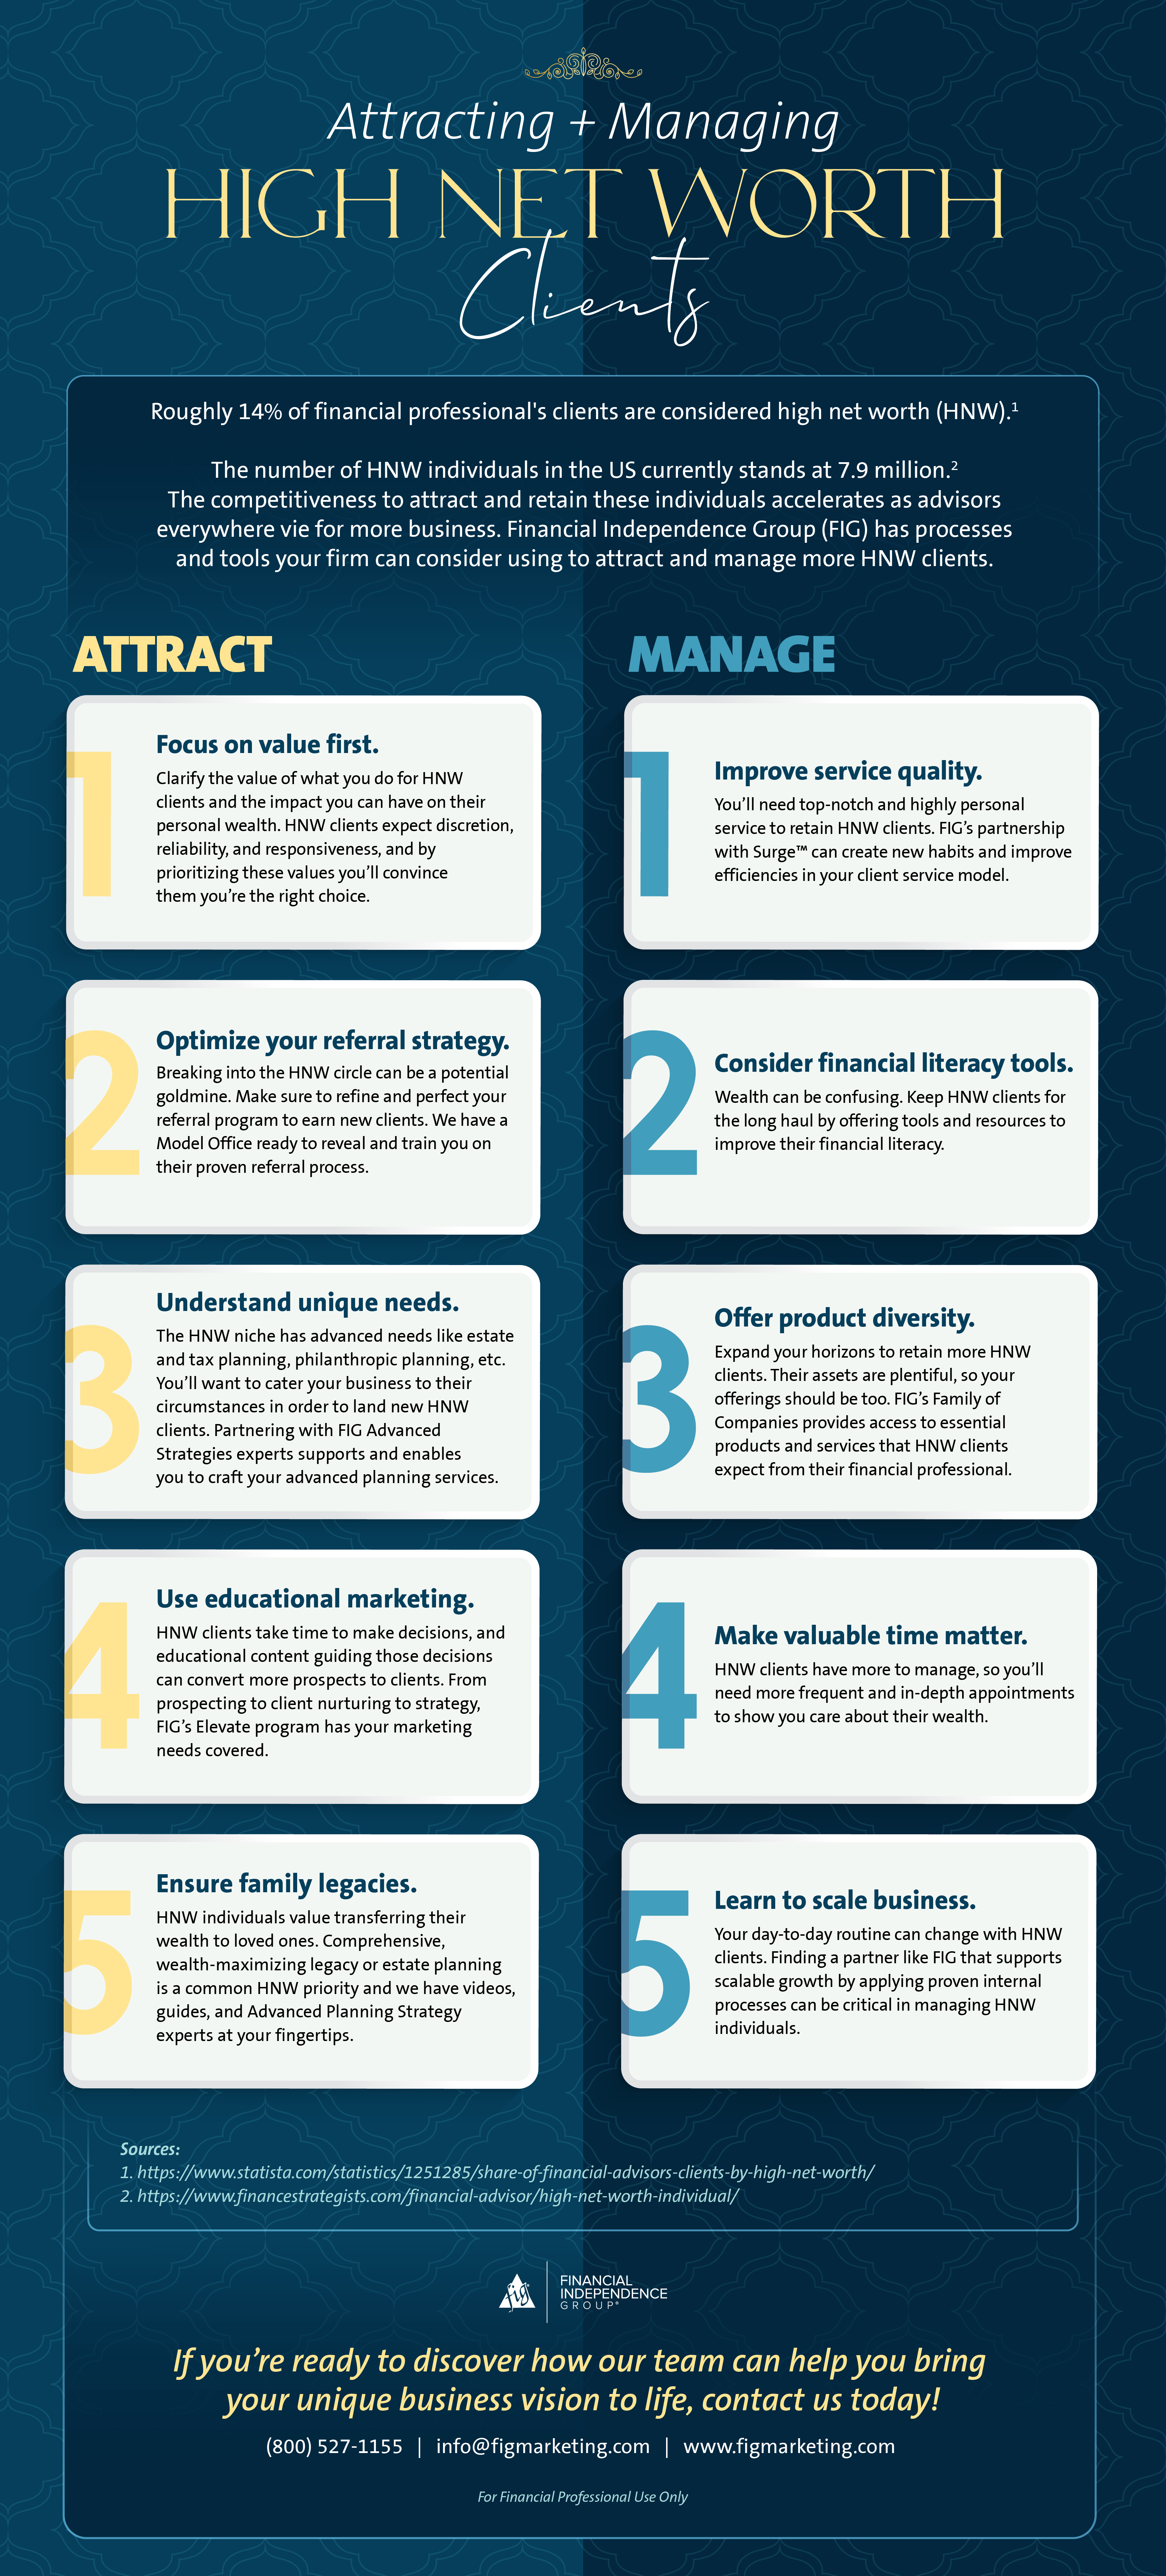
PNC Wealth Management, currently operating under the PNC Private Bank and Hawthorn brands, typically employs an Assets Under Management (AUM) fee structure for high-net-worth clients. As of 2026, these fees generally range from 0.50% to 1.25% annually, depending on the total value of investable assets, with lower percentage rates applied as portfolio values cross specific million-dollar breakpoints.
Understanding PNC’s Wealth Management Tiers
High-net-worth (HNW) and ultra-high-net-worth (UHNW) individuals have financial needs that extend far beyond standard retail banking. PNC addresses these through two primary service tiers. Understanding which tier you fall into is the first step in determining your fee schedule, as the complexity of the service dictates the cost.
PNC Private Bank
This tier is designed for individuals and families with investable assets typically starting at $1 million. The focus here is on integrated wealth management, which combines investment advice, tax-efficient strategies, and estate planning. In 2026, PNC Private Bank remains the primary vehicle for high-net-worth individuals who require a dedicated wealth advisor but may not yet need a full family office structure.
PNC Private Bank Hawthorn
Hawthorn is PNC’s boutique segment for ultra-high-net-worth clients, generally requiring a minimum of $20 million to $25 million in investable assets. Because the needs of these families involve multi-generational planning, complex philanthropic goals, and specialized alternative investments, the fee structures at the Hawthorn level are often more bespoke. While they still utilize AUM-based pricing, they may also incorporate flat annual retainers for comprehensive family office services.
Detailed Breakdown of AUM Fee Structures
The most common way PNC Wealth Management charges for its services is the Assets Under Management (AUM) model. This model aligns the advisor’s interests with the client’s; as the portfolio grows, the advisor earns more, and conversely, fees drop if the portfolio value declines.
For high-net-worth individuals in 2026, the fee is calculated as a percentage of the total assets the bank manages. This is usually a "tiered" or "graduated" fee. For example, you might pay one rate on the first million dollars and a lower rate on the subsequent four million.
Typical Fee Breakpoints for 2026
While exact fees can vary based on the specific investment products chosen (such as discretionary vs. non-discretionary accounts), the following table illustrates the standard graduated fee expectations for PNC Private Bank clients:
| Asset Level | Estimated Annual Fee Percentage | Annual Cost (at Tier Midpoint) |
|---|---|---|
| First $2,000,000 | 1.00% – 1.25% | $20,000 – $25,000 |
| Next $3,000,000 ($2M–$5M) | 0.75% – 0.85% | $15,000 – $17,000 (per $2M) |
| Next $5,000,000 ($5M–$10M) | 0.60% – 0.70% | $30,000 – $35,000 |
| Over $10,000,000 | 0.40% – 0.55% | Custom/Negotiable |
Note: These figures represent the advisory fee and may not include the underlying expenses of specific investment vehicles.

Beyond the AUM: Trust and Fiduciary Fees
For high-net-worth clients, PNC often serves as a corporate trustee or co-trustee. These services are vital for estate preservation but come with a separate set of fee considerations. Trust administration involves significant legal and fiduciary responsibility, which PNC prices based on the complexity of the trust document and the types of assets held within the trust.
Fiduciary Administration Fees
When PNC acts as a trustee, the fee covers the professional management of trust assets, the distribution of income to beneficiaries, and the filing of necessary tax returns (Form 1041). In 2026, fiduciary fees often mirror the AUM schedule but may include a "base fee" ranging from $2,500 to $5,000 annually to cover the administrative overhead of maintaining the trust account.
Specialized Asset Management
If your high-net-worth portfolio includes "hard assets" such as commercial real estate, oil and gas interests, or closely-held business interests, PNC may charge additional management fees for these specific holdings. These assets require specialized appraisal, environmental monitoring, and property management oversight that standard liquid stocks and bonds do not.
Identifying Indirect and Hidden Costs
When evaluating PNC Wealth Management high net worth fees, it is critical to distinguish between the advisory fee paid to PNC and the internal costs of the investments themselves. A transparent look at your total "all-in" cost is necessary to determine the true impact on your net returns.
- Expense Ratios: If your advisor builds a portfolio using Mutual Funds or Exchange-Traded Funds (ETFs), those funds have their own internal management fees. Even if PNC’s advisory fee is 1.00%, the underlying fund expenses could add another 0.10% to 0.50% to your total cost.
- Platform and Custodial Fees: While often bundled into the AUM fee for HNW clients, some specialized accounts may incur separate custodial fees for holding assets at a third-party institution.
- Transaction Costs: Although the industry has largely moved toward "wrap" accounts—where commissions are replaced by the single AUM fee—certain foreign securities or specialized alternative investments may still carry trade-specific costs.
- Alternative Investment Fees: High-net-worth portfolios often include private equity, hedge funds, or private credit. These vehicles typically have their own "2 and 20" structures (2% management fee and 20% performance fee) which are separate from PNC's wealth management fee.
Comparing PNC to Industry Competitors
PNC Private Bank operates in a competitive landscape alongside firms like J.P. Morgan Private Bank, Bank of America Private Bank (formerly U.S. Trust), and independent Registered Investment Advisors (RIAs).
- PNC vs. Large National Banks: PNC's fees are generally competitive with other "Big Four" banks. However, PNC is often cited for its regional strength and a more "personal" approach compared to the massive scale of J.P. Morgan.
- PNC vs. Independent RIAs: Many independent RIAs offer a flat 1.00% fee for the first $5 million. PNC’s advantage often lies in its integrated banking services (lending, specialized mortgages, and treasury management) which an independent firm cannot provide directly.
- PNC vs. Discount Brokerages: Firms like Charles Schwab or Vanguard offer "Personal Advisor" services for as low as 0.30%. However, these services rarely include the high-touch estate planning, trust administration, and private banking perks that a HNW individual receives at PNC Private Bank.
The Value Proposition: Is the Fee Justified?
Evaluating a fee of 1.00% on a $5 million portfolio means paying $50,000 annually. For many high-net-worth families, the justification for this expense in 2026 rests on three pillars:
Holistic Wealth Integration
PNC advisors do not just pick stocks. They coordinate with your CPA and attorney to ensure that your investment strategy aligns with your tax liability and your long-term estate goals. For a HNW client, a single well-executed tax-loss harvesting strategy or a trust restructure can save more in a single year than the cost of the advisory fee.
Access to Private Credit and Banking
High-net-worth status at PNC grants access to specialized lending products. This includes securities-based lines of credit (SBLOCs), which allow clients to borrow against their portfolio at preferred rates without triggering a taxable capital gains event. In a volatile 2026 interest rate environment, these private banking perks are a significant component of the overall value.
Fiduciary Standard of Care
As a wealth management client, PNC acts as a fiduciary. This is a legal requirement to act in the best interest of the client at all times. This contrasts with the "suitability standard" used by some broker-dealers, providing an extra layer of protection and transparency regarding how fees are earned and reported.
How to Verify and Negotiate Your Fees
While banks have standard fee schedules, high-net-worth clients often have some room for negotiation, especially at the $10 million+ level.
- Request the ADV Part 2A: This is a mandatory SEC filing that every investment advisor must provide. It contains a detailed, plain-English description of their fee schedules, potential conflicts of interest, and the services provided. You can find this through the SEC Investment Adviser Public Disclosure (IAPD) website.
- Ask for a "Total Cost of Ownership" (TCO) Analysis: Before signing an agreement, ask your PNC advisor to provide a written estimate of the all-in costs, including the advisory fee, estimated internal fund expenses, and any potential trust or administrative fees.
- Consolidate Assets: Because of the breakpoint system, you will pay a lower effective rate by consolidating your assets at one institution rather than spreading $5 million across three different banks.
Frequently Asked Questions
1. What is the minimum asset requirement for PNC Wealth Management in 2026? While PNC Private Bank generally looks for clients with at least $1 million in investable assets, they may accept lower amounts for individuals with high earnings potential or specific complex needs. For Hawthorn, the ultra-high-net-worth division, the threshold is typically $20 million.
2. Does PNC charge a performance-based fee? For standard PNC Private Bank accounts, the answer is generally no. Fees are based on a percentage of assets, not a percentage of the profits. However, if your portfolio includes third-party alternative investments (like private equity), those specific funds likely charge performance fees within their own structures.
3. Are wealth management fees tax-deductible? Under current tax laws in 2026, the deduction for investment advisory fees is restricted for most individual taxpayers. However, if the fees are associated with the management of a trust or certain business entities, parts of the fee may be deductible. You should consult with a tax professional regarding your specific situation.
4. How often are the AUM fees deducted? PNC typically calculates and deducts fees on a quarterly basis in arrears. The fee is based on the average daily balance or the ending balance of the account during that quarter, depending on the specific terms of your investment management agreement.
5. Can I opt for a flat fee instead of a percentage-based fee? In the Hawthorn tier (UHNW), flat-fee arrangements or annual retainers are more common due to the administrative complexity of family office services. For standard Private Bank HNW clients, the AUM percentage remains the default model, though fixed fees for one-time financial plans are sometimes available.
6. Do these fees include tax preparation? Standard investment management fees usually do not include the actual filing of your personal income tax returns (Form 1040). However, the wealth management team will provide all necessary 1099s and cost-basis reporting, and they will work closely with your external CPA to optimize your tax strategy.
Practical Recommendation
If you are evaluating PNC Wealth Management high net worth fees in 2026, your first action should be to request a formal proposal that includes a "Fee Comparison Worksheet." Compare the proposed AUM fee against the services you actually need. If you require complex estate planning and trust services, a 1.00% fee at a full-service institution like PNC may be more cost-effective than hiring a separate investment advisor, estate attorney, and trust company. However, if you only require simple asset allocation, you should verify that the private banking perks justify the premium over a low-cost digital advisor.
Image Gallery
Select an image to open it in a new tab.


Zara El-Hashem
Sociocultural Dynamics and Academics Writer
