Navigating auto insurance in Lakeway, Texas, requires understanding the state’s mandatory financial responsibility laws, specific regional risks like severe weather, and the importance of selecting coverage limits that exceed state minimums. By prioritizing comprehensive protection, Lakeway drivers can safeguard their assets against local traffic density and environmental hazards unique to the Texas Hill Country.
The Foundation of Texas Financial Responsibility Laws
In Texas, all drivers are legally required to maintain a minimum level of liability insurance to operate a vehicle on public roadways. As of 2026, the Texas Department of Insurance (TDI) mandates that every driver must carry a policy that meets the "30/60/25" standard. These figures represent the maximum amount an insurance company will pay per incident for specific categories of damage.
Specifically, the 30/60/25 requirement breaks down as follows:
- $30,000 for bodily injury per person: This covers medical expenses, rehabilitation, and lost wages for a single person injured in an accident where you are at fault.
- $60,000 for total bodily injury per accident: This is the maximum total amount paid for all injuries sustained by all parties in a single accident you cause.
- $25,000 for property damage per accident: This covers the repair or replacement costs for another person’s vehicle, property, or infrastructure (such as fences or utility poles) damaged in the accident.
While these minimums satisfy the state’s legal mandate, they are often insufficient in modern economic conditions. Given the rising cost of vehicle repairs and the high expense of medical care, an accident resulting in major injuries or the destruction of a luxury vehicle can easily exceed these limits. When your coverage is exhausted, you remain personally liable for any remaining balance, which could put your personal savings and property at significant risk.
Evaluating Risk Factors Specific to Lakeway
Lakeway presents a unique environment for vehicle owners. Situated along the southern shore of Lake Travis, the geography features winding roads, steep inclines, and heavy seasonal tourism. Understanding how these factors influence your insurance needs is essential for effective risk management.
Roadway Infrastructure and Traffic
Lakeway’s infrastructure, including segments of RM 620, serves as a high-traffic corridor for both local commuters and visitors traveling to the nearby recreation areas. Increased traffic density leads to a statistically higher probability of fender-benders and multi-car accidents. When selecting your coverage, consider adding "Collision" and "Comprehensive" protection. Collision insurance pays for your vehicle's repairs regardless of who is at fault, while Comprehensive covers non-collision events such as theft, vandalism, or damage caused by falling objects.
Environmental Hazards
Texas is prone to severe weather, including convective storms, flash flooding, and occasional hail. Because Lakeway is located in the Texas Hill Country, vehicle owners must be mindful of hail damage, which is a frequent cause of insurance claims in this region. Comprehensive coverage is the specific component of your policy that addresses weather-related damage. Failure to include this in your policy means you would be forced to pay for windshield replacements or bodywork out-of-pocket after a storm.
Essential Coverage Components Beyond the Minimum
To properly protect your household, you should look beyond the state-mandated liability limits and consider supplementary coverage options. These additions often prove to be the most vital when an unforeseen incident occurs.
- Uninsured/Underinsured Motorist Coverage (UM/UIM): This is one of the most critical additions for any Texas driver. If you are hit by a driver who carries no insurance, or whose insurance limits are too low to cover the total damage, UM/UIM coverage protects you. Given that a significant percentage of drivers on the road remain uninsured, this coverage prevents you from bearing the financial burden of another person's negligence.
- Personal Injury Protection (PIP): Unlike liability insurance, which covers the other party, PIP covers your own medical expenses and lost wages, regardless of who caused the accident. This is an "no-fault" addition that can provide immediate financial relief when medical bills begin to accrue following a collision.
- Gap Insurance: If you are currently financing a newer vehicle, your loan balance may exceed the actual cash value (ACV) of the car. In the event of a total loss, standard insurance only pays the ACV. Gap insurance bridges the difference, ensuring you are not left paying off a loan for a vehicle you no longer possess.
Comparison Table: Understanding Coverage Types
The following table summarizes the purpose and necessity of common auto insurance components available to Lakeway residents.
| Coverage Type | What It Covers | Is It Required in TX? | Why It Matters |
|---|---|---|---|
| Bodily Injury Liability | Injuries to others in an accident you cause. | Yes | Legally required for compliance. |
| Property Damage Liability | Damage to another person's property. | Yes | Legally required for compliance. |
| Collision | Damage to your own car from an accident. | No | Vital if your vehicle is financed or valuable. |
| Comprehensive | Theft, fire, weather, and vandalism. | No | Essential for protection against hail/floods. |
| PIP | Your medical bills and lost wages. | No (unless rejected in writing) | Provides immediate help for your own health. |
| UM/UIM | Damages from uninsured/underinsured drivers. | No (unless rejected in writing) | Protects you from other drivers' lack of funds. |
The Process of Verification and Maintenance
In Texas, law enforcement uses the TexasSure Vehicle Insurance Verification system to confirm compliance during traffic stops or registration renewals. It is vital to ensure your insurance information is correctly linked to your vehicle registration.
- Documentation: Always keep a copy of your current insurance card in your vehicle. In 2026, most carriers allow for digital copies, which are legally recognized in Texas. Ensure that your mobile device has access to this document, or keep a hard copy in the glove compartment for instances where a phone battery may be depleted.
- Annual Review: Your insurance needs can shift as your life circumstances change. Did you move closer to work? Did you add a teenage driver to your policy? Did you purchase a new, higher-value vehicle? An annual review with your agent ensures that your policy limits accurately reflect your current risk profile.
- Avoiding Lapses: Never allow your policy to lapse. A gap in coverage, even for a few days, can result in higher premiums upon reinstatement and the potential for legal consequences, including fines and the suspension of your driver's license or vehicle registration.
Navigating Claims and Dispute Resolution
If you are involved in an accident, the steps you take immediately following the incident will significantly influence the outcome of your insurance claim. First, prioritize safety by moving to a secure location if possible and contacting local emergency services. Collect the contact information, insurance details, and license plate numbers of all involved parties.
If the accident occurs in Lakeway, be prepared to provide a statement to the local police department for the official accident report. This report is a crucial piece of evidence that insurance companies use to determine fault.
If you encounter a dispute with your insurer, begin by reviewing your policy declarations page to confirm what is covered. If you remain dissatisfied with the handling of your claim, the Texas Department of Insurance provides resources for consumers to file complaints. They can mediate disputes regarding claim denials or slow payment processes. Always keep a detailed log of every conversation, including the name of the representative, the date, and the specific details discussed.
Frequently Asked Questions
1. Does my homeowners insurance cover items stolen from my car in Lakeway? Generally, no. Items stolen from your vehicle—such as electronics, tools, or personal belongings—are typically covered under your renters or homeowners insurance policy, not your auto policy. However, your auto insurance's "Comprehensive" coverage would cover damage to the vehicle itself, such as a broken window from an attempted break-in.
2. Can I lower my premiums while keeping good coverage? Yes. You can often reduce premiums by increasing your deductible, though this means you pay more out-of-pocket if you file a claim. Additionally, many providers offer discounts for defensive driving courses, bundling home and auto policies, or maintaining a clean driving record.
3. Is "Full Coverage" a real insurance term? "Full coverage" is not a formal industry term. It is a colloquial expression that usually refers to a policy combining Liability, Collision, and Comprehensive coverage. Always clarify the specific limits and deductibles with your agent rather than assuming "full coverage" provides blanket protection.
4. How does the age of my car affect my coverage decisions? As a vehicle ages, its actual cash value decreases. Once the value drops significantly, you may decide to drop Collision and Comprehensive coverage to save on premiums. A good rule of thumb is to weigh the annual cost of these premiums against 10% of the vehicle’s current market value.
5. What should I do if the other driver is uninsured? If you have Uninsured Motorist (UM) coverage, contact your insurance provider immediately. They will initiate the claims process under your policy. If you lack this coverage, you may have to pursue legal action against the individual driver, which is often a lengthy and costly process with no guarantee of recovery.
Final Recommendation
Protecting yourself on Lakeway roads is not simply about meeting the minimum legal requirements; it is about establishing a financial safety net. Review your current policy documents today. If you find your liability limits are at the 30/60/25 floor, request a quote for higher limits and ensure you have sufficient Uninsured/Underinsured Motorist coverage. In the event of a significant accident, these relatively small increases in monthly premiums will be significantly less expensive than the potential out-of-pocket costs of a major liability claim.
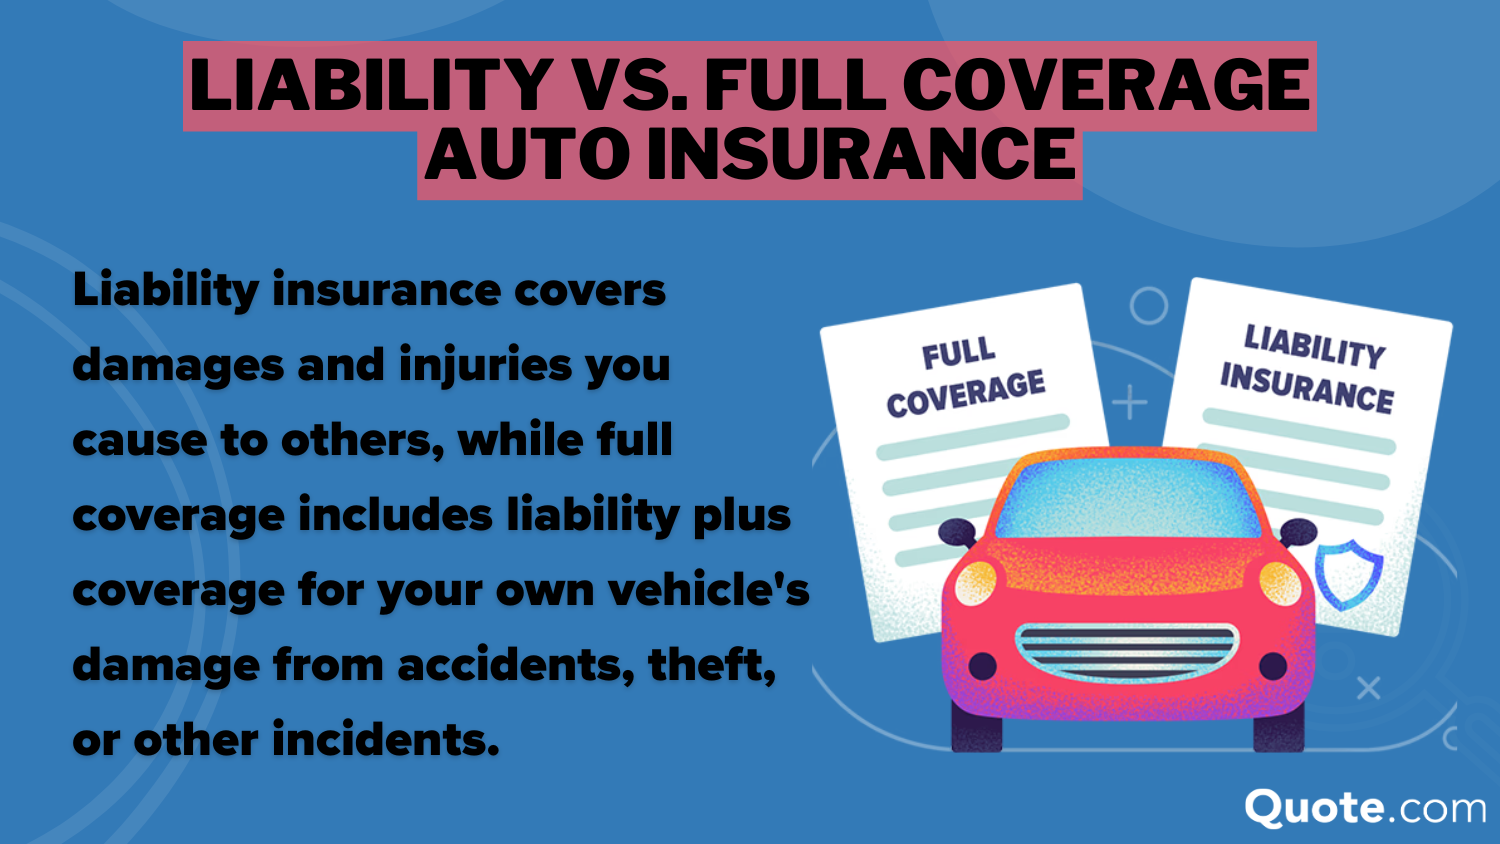
Image Gallery
Select an image to open it in a new tab.

Simon Caldwell
Enterprise Technology and Systems Editor
