
Securing discount auto insurance in Washington DC requires navigating mandatory coverage minimums, unique urban driving risk factors, and district-specific insurer incentives designed to lower high urban premiums. By understanding local regulatory requirements, maintaining a clean driving record, qualifying for specific demographic or vehicle safety reductions, and strategically bundling policies, drivers can successfully minimize their annual insurance expenditures in the District of Columbia.
Navigating the auto insurance market in the District of Columbia presents unique challenges for vehicle owners. Because Washington DC is a dense urban environment characterized by heavy traffic congestion, high pedestrian foot traffic, and a distinct mix of commuter and local vehicles, insurance companies generally price their policies higher to account for increased risks of fender-benders, theft, and property damage. However, state-regulated mandates and competitive pressures among regional and national carriers mean that numerous opportunities exist to reduce these costs.
For residents looking to protect their vehicles while keeping household budgets manageable, identifying available discounts is only half the battle. Drivers must also understand how DC's unique legal framework—specifically its status as a pure comparative fault jurisdiction with distinct minimum liability requirements—interacts with discount structures. This guide examines the mechanics of auto insurance in the nation's capital, details the most common and lucrative discounts available, outlines eligibility criteria, and provides actionable steps to lower your monthly premium without sacrificing essential protection.
Understanding Washington DC Auto Insurance Requirements
Before evaluating discounts, every vehicle owner in the District of Columbia must understand the legal baseline established by the District of Columbia Department of Insurance, Securities and Banking (DISB) and the Department of Motor Vehicles (DMV). Driving without insurance in the District carries severe penalties, including steep fines, suspension of vehicle registration, and potential points on your driver's license.
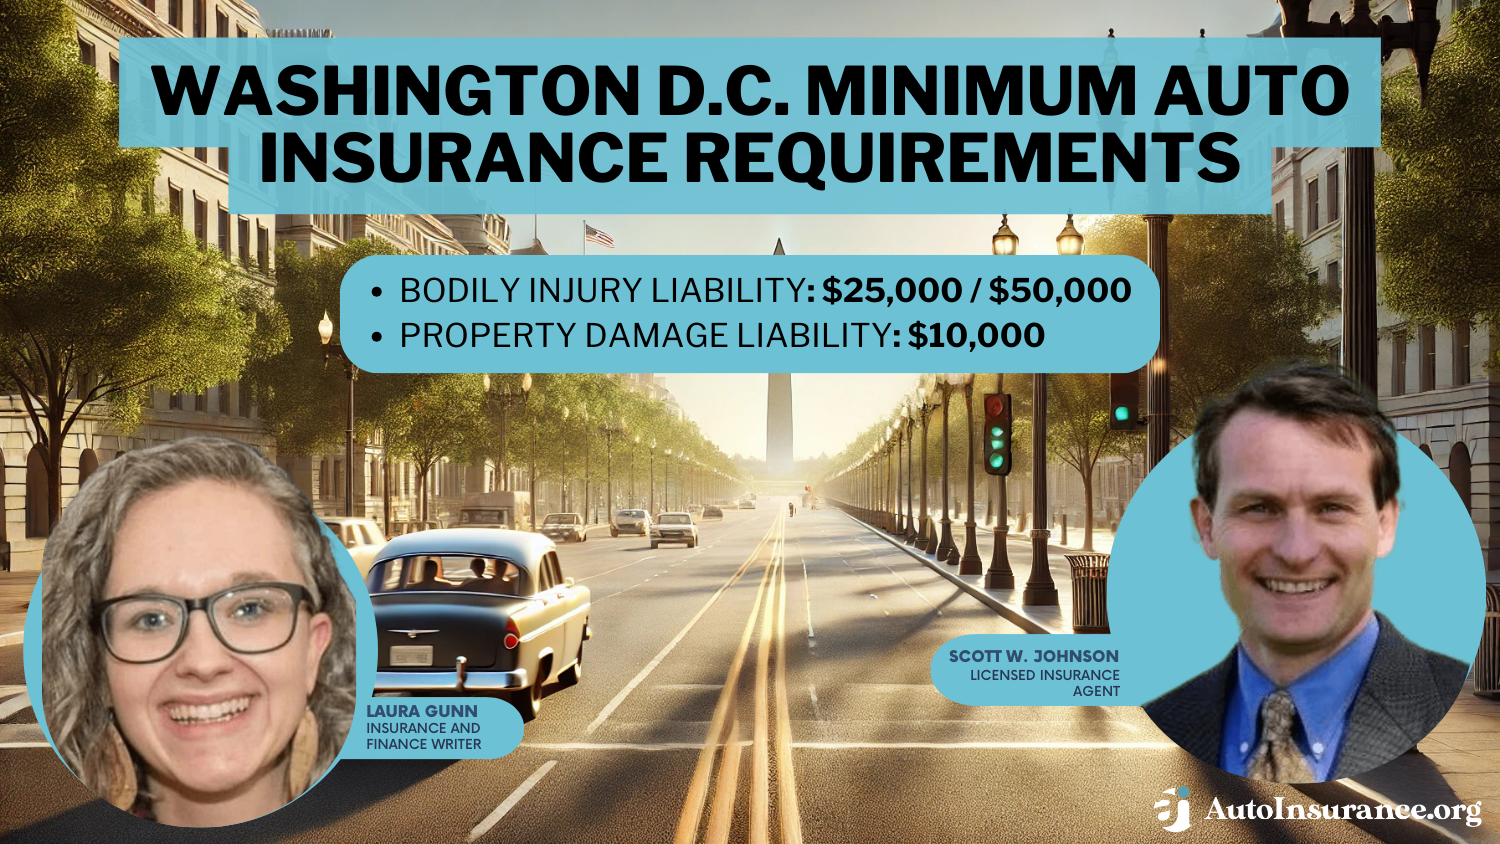
Washington DC operates under a mandatory liability insurance system. Every registered vehicle must maintain continuous coverage that meets or exceeds the District's statutory minimum limits. As of 2026, these minimum coverage limits include:
- Bodily Injury Liability: $25,000 per person and $50,000 per accident. This pays for injuries or death you cause to other drivers, pedestrians, or passengers when you are at fault.
- Property Damage Liability: $10,000 per accident. This covers damage you cause to another person’s property, such as their vehicle, guardrails, or public infrastructure.
- Uninsured Motorist Coverage: $25,000 per person and $50,000 for bodily injury, plus $10,000 for property damage (with a $200 deductible for property damage). This protects you if you are hit by a driver who carries no insurance or flees the scene in a hit-and-run accident.
It is vital to recognize that these mandatory minimums are often insufficient for complete financial protection. If you cause a severe multi-car collision on busy arteries like Connecticut Avenue or the Southeast/Southwest Freeway, damages can quickly exceed these limits, leaving your personal assets vulnerable to lawsuits. Therefore, when seeking discount auto insurance in Washington DC, the goal should not be simply buying the cheapest legally compliant policy, but rather maximizing discounts on a robust, comprehensive policy that includes higher liability limits, collision coverage, and comprehensive coverage.
Primary Types of Auto Insurance Discounts in Washington DC
Insurance carriers operating in the District offer a wide variety of discounts. While individual company offerings vary, most discounts fall into distinct categories based on driver behavior, vehicle safety features, policy management habits, and demographic qualifications.
Driver-Based Discounts
Insurers reward drivers who demonstrate a history of safety and responsibility behind the wheel. Because driver behavior is the single greatest predictor of claims frequency, these discounts can yield substantial savings.
- Good Driver Discount: Offered to motorists who have maintained a clean driving record free of at-fault accidents, moving violations, and speeding tickets for a specified period, typically three to five years.
- Defensive Driving Course Discount: Completing a state-approved defensive driving course can earn you a policy discount. In the DC area, these courses can often be taken online or through local organizations and are particularly useful for wiping minor infractions or lowering rates for younger or older drivers.
- Good Student Discount: High school, college, and university students who maintain a "B" average or higher (typically a 3.0 GPA or equivalent) can qualify for significant reductions. Insurers view academic diligence as a proxy for maturity and risk aversion.
Vehicle-Based Discounts
The make, model, and safety equipment of your automobile directly influence your risk profile. Modern vehicles equipped with advanced technology help insurance companies mitigate payout risks, and they pass those savings on to the policyholder.
- Safety Features Discount: Vehicles equipped with factory-installed safety features such as anti-lock braking systems (ABS), dual front airbags, electronic stability control, and daytime running lights qualify for baseline discounts.
- Anti-Theft Device Discount: Given urban vehicle theft rates, having active or passive anti-theft systems—ranging from standard alarm systems to GPS tracking units and ignition kill switches—can lower comprehensive insurance premiums.
- New Vehicle Discount: Driving a car that is less than three years old often qualifies for a discount, as newer vehicles are less likely to suffer mechanical breakdowns that lead to accidents and feature updated structural safety engineering.
Policy and Administrative Discounts
How you manage your account, pay your bills, and structure your coverage can unlock effortless savings.
- Bundle and Save (Multi-Policy): Combining your auto insurance with renters insurance, homeowners insurance, or condo insurance through the same carrier is one of the most effective ways to lower your total insurance outlay. This is especially relevant in DC, where high rental and housing costs make multi-policy bundling very popular.
- Multi-Car Discount: If your household insures two or more vehicles under the same policy, almost every major carrier offers a percentage reduction on each vehicle.
- Paperless and Automatic Payment (Autopay) Discounts: Enrolling in automatic monthly deductions and opting out of physical paper billing statements provides small, immediate percentage reductions on your premium.
- Paid-in-Full Discount: Paying your annual or semi-annual premium upfront in a single lump sum rather than making monthly installments allows you to bypass installment fees and earn a direct discount.
| Discount Category | Common Types | Average Potential Savings | Primary Eligibility Criteria |
|---|---|---|---|
| Driver Behavior | Good Driver, Defensive Driving, Good Student | 5% to 25% | Clean record for 3–5 years; GPA of 3.0+; certified course completion. |
| Vehicle Safety | Anti-theft, Advanced Safety Features, New Car | 5% to 15% | Factory-installed safety tech, tracking systems, vehicle age under 3 years. |
| Policy Structure | Multi-Policy (Bundling), Multi-Car | 10% to 25% | Holding 2+ policies with one insurer or insuring multiple household vehicles. |
| Administrative | Autopay, Paperless, Paid-in-Full | 3% to 10% | Enrolled in electronic billing, automatic deductions, or annual upfront payment. |

Usage-Based Insurance and Telematics in the District
One of the most rapidly growing segments of discount auto insurance in Washington DC is Usage-Based Insurance (UBI), often powered by telematics. Programs such as Progressive's Snapshot, State Farm's Drive Safe & Save, Allstate's Drivewise, and GEICO's DriveEasy monitor your driving habits via a mobile application or a plug-in device installed in your vehicle's OBD-II port.
These programs evaluate specific driving metrics in real time:
- Mileage: How many total miles you drive. This is exceptionally beneficial for Washington DC residents who rely heavily on the Metrorail, buses, walking, or ridesharing, and drive their personal vehicles infrequently.
- Speed: Whether you consistently adhere to posted speed limits, particularly on highways like I-695 or Rock Creek Parkway.
- Hard Braking and Rapid Acceleration: Measuring how smoothly you operate the vehicle, avoiding sudden stops that indicate tailgating or distracted driving.
- Time of Day: Tracking whether you drive during high-risk late-night hours.
- Distracted Driving: Monitoring whether you handle your mobile phone while the vehicle is in motion (tracked by app-based telematics).
For urban drivers who park their cars during the week and only use them for weekend errands or occasional trips out of the city, telematics programs can result in deep discounts—sometimes up to 30% or more. However, drivers should review program terms carefully; certain telematics programs can actually raise your rates if they record frequent harsh braking or high-speed driving in congested urban traffic.
Comparing Auto Insurance Options in Washington DC
When shopping for discount auto insurance in Washington DC, consumers must look beyond the initial headline discount percentage and evaluate the carrier's overall financial strength, customer service reputation, and claims handling efficiency.
National carriers operating in the District—including GEICO, State Farm, Progressive, Allstate, and Liberty Mutual—offer robust digital tools, widespread name recognition, and complex automated discount engines. These companies excel at providing multi-policy bundles and advanced telematics programs. Conversely, regional mutual insurers and specialized writers may offer personalized service and specialized underwriting that can benefit drivers with unique profiles, such as those with minor historical infractions or drivers of specialty vehicles.
To secure the best value, insurance experts recommend obtaining quotes from at least three different carriers while ensuring that each quote matches the exact same coverage limits and deductibles. Comparing mismatched policies—such as comparing a bare-bones liability quote from one company against a full-coverage quote with roadside assistance from another—creates a false economy.
Common Mistakes to Avoid When Seeking Insurance Discounts
Policyholders frequently leave money on the table or inadvertently invalidate their savings due to common oversights during the quote and renewal process.
- Failing to Update Life Changes: Significant life events can unlock new discounts. If you recently married, moved closer to your workplace, bought a home, or your child graduated college and left your household policy, inform your insurer immediately. Failing to update your profile means you may be missing out on automated rate reductions.
- Overlooking Professional or Organizational Affiliations: Many insurance companies partner with alumni associations, professional organizations, labor unions, and federal employee credit unions (such as Navy Federal or PenFed) to offer exclusive group discounts. Always ask your agent if your employer or organizational memberships qualify you for a special rate.
- Choosing Insufficient Coverage for Maximum Savings: While lowering your coverage limits will reduce your premium, doing so to dangerous levels leaves you financially exposed. Never drop down to the strict DC minimums just to secure a lower price without evaluating your personal net worth and risk tolerance.
- Ignoring Credit History Impact: While some states restrict the use of credit scores in setting insurance rates, credit-based insurance scores remain a rating factor utilized by many major insurers operating in the District of Columbia. Maintaining healthy credit habits directly supports lower insurance premiums over time.
Practical Steps to Lower Your DC Auto Insurance Bill
Taking control of your auto insurance costs requires a methodical approach. Follow these structured steps to audit your current policy and capture every available discount:
- Review Your Current Declarations Page: Pull your current policy and examine your coverage limits, deductibles, and active discounts. Note what safety features, bundling options, or driver classifications are currently applied to your account.
- Audit Your Annual Mileage: Calculate your actual driving mileage over the past year. If your daily commute has shortened or you now work remotely part of the week, report this reduction to your insurer or switch to a low-mileage or telematics-based program.
- Shop and Compare Quotes: Utilize online quoting tools or independent insurance brokers to gather quotes from multiple licensed carriers operating in Washington DC.
- Inquire About Unlisted Discounts: Call your current or prospective insurance agent directly and ask point-blank: "What additional discounts do you offer that I am not currently receiving?" Agents often have access to niche discounts that do not appear automatically in online quoting engines.
- Adjust Deductibles Strategically: If you have adequate emergency savings set aside, consider raising your comprehensive and collision deductibles from $500 to $1,000. This shift can instantly lower your monthly premium, allowing you to bank the savings while retaining protection against catastrophic losses.
By combining thorough market research, proactive communication with insurance providers, and careful management of your driving and policy habits, you can successfully secure optimal discount auto insurance in Washington DC that balances comprehensive protection with long-term financial efficiency.
Image Gallery
Select an image to open it in a new tab.
Ingrid Bjornson
Global Cyber Policy and Regulation Analyst
