What Credit Unions in Nampa, Idaho Offer: A Complete Guide to Services, Rates, and Membership

Credit unions in Nampa, Idaho offer a comprehensive suite of consumer and commercial financial services, including high-yield savings accounts, low-interest auto and home loans, rewards credit cards, and business financing. Operating as non-profit financial cooperatives, Nampa credit unions return profits to members through lower loan interest rates, higher deposit yields, and reduced account maintenance fees compared to traditional commercial banks.
Understanding the Credit Union Model in Nampa, Idaho
Financial institutions in Nampa, Idaho, generally fall into two distinct categories: investor-owned commercial banks and member-owned credit unions. Understanding how a credit union operates reveals why these institutions often deliver more competitive pricing and personalized service across Canyon County and the broader Treasure Valley.
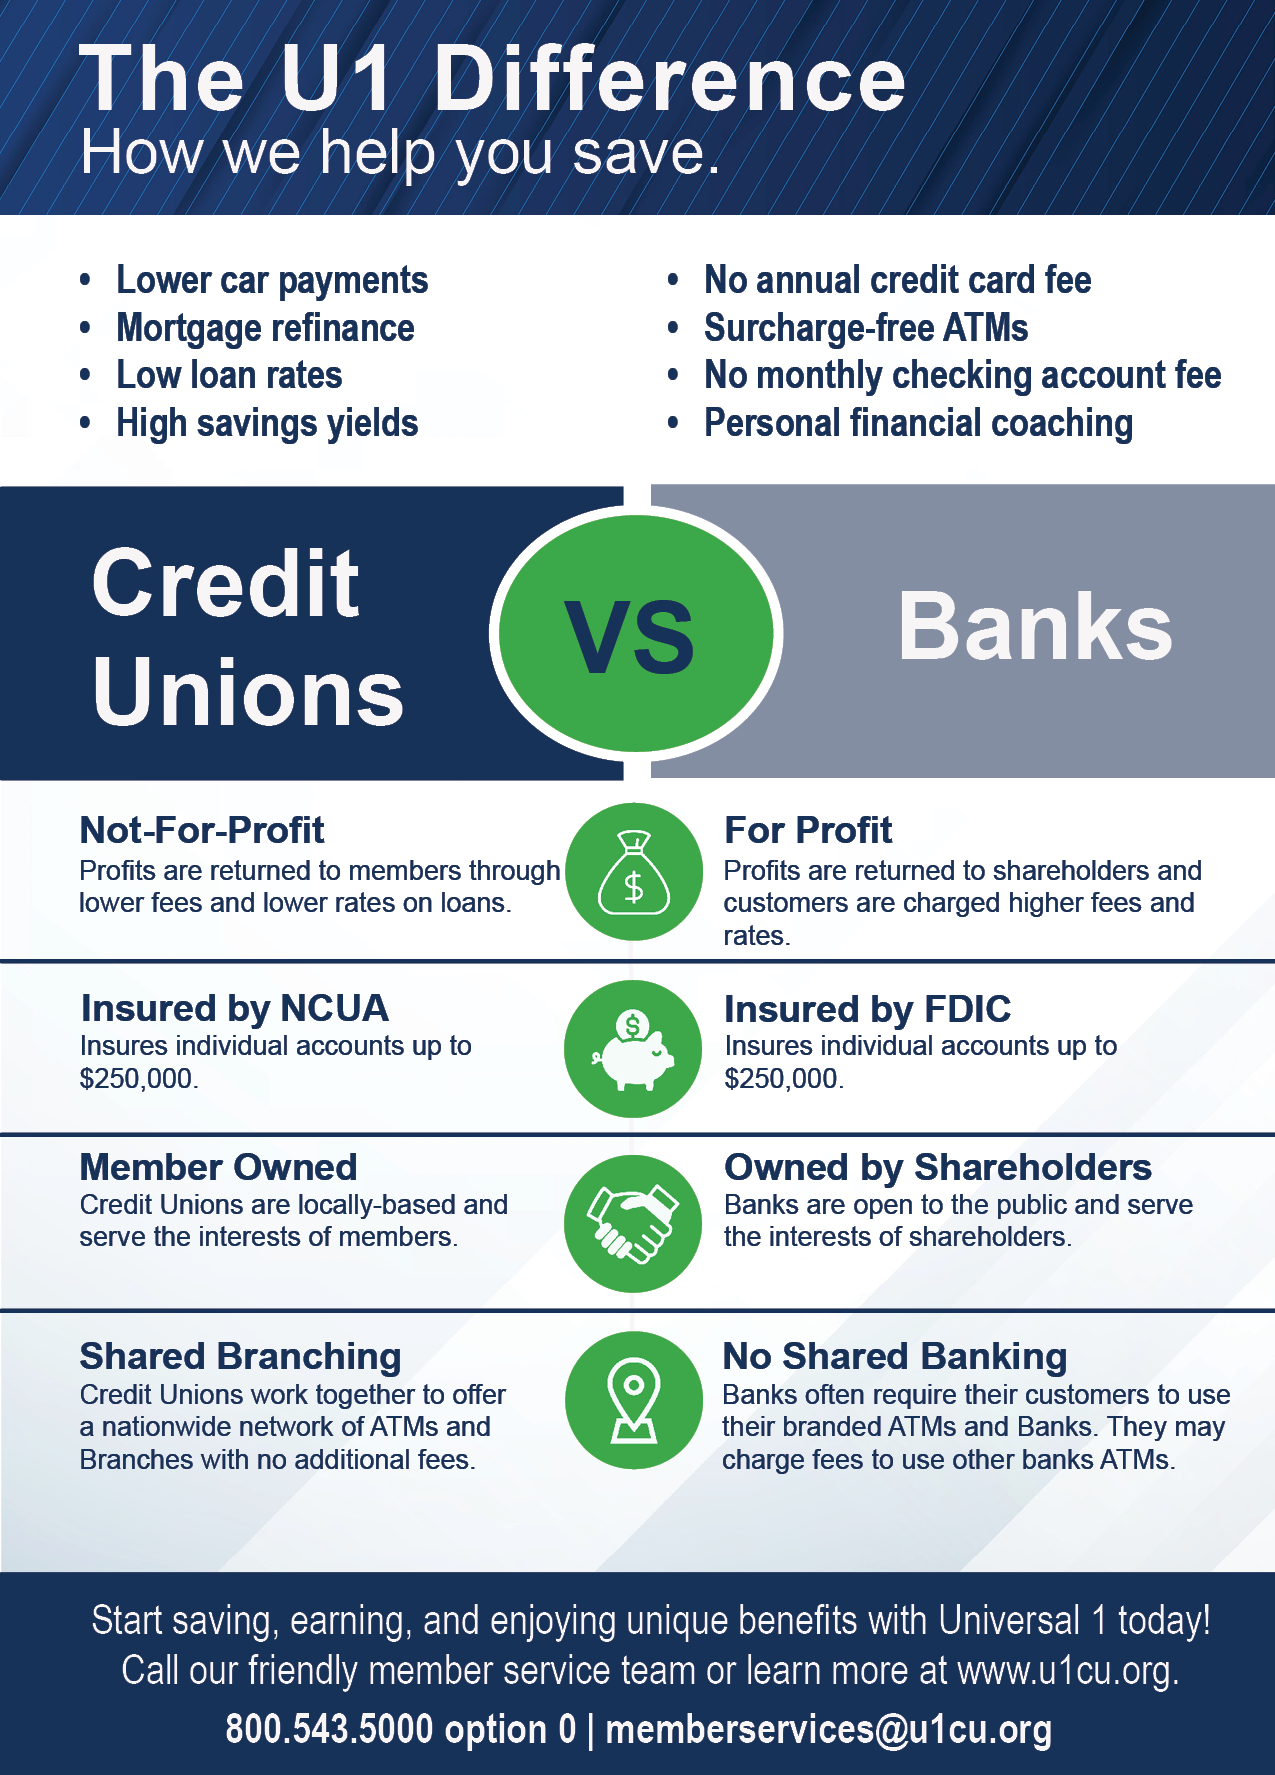
Unlike commercial banks, which focus on generating profits for corporate shareholders, credit unions operate as tax-exempt financial cooperatives. Every member who opens an account holds a single share in the organization, giving each member an equal vote in selecting the volunteer board of directors. Earnings generated by a credit union are not distributed to external investors; instead, they are returned to the membership in the form of higher dividend rates on savings, lower interest rates on loans, reduced fee structures, and investments in local branch infrastructure and digital technology.
- Earnings / Revenue Generated
- Retained & Returned to Members As:
- Higher Dividend Yields on Savings/Certificates
- Lower Loan & Mortgage Interest Rates
- Reduced Service & Maintenance Fees
- Expanded Branch & Digital Services
- Retained & Returned to Members As:
Credit unions serving Nampa operate under either a federal charter managed by the National Credit Union Administration (NCUA) or a state charter regulated by the Idaho Department of Finance. Regardless of the specific chartering structure, member deposits at federally insured credit unions are protected up to $250,000 per individual owner by the National Credit Union Share Insurance Fund (NCUSIF). This deposit insurance provides the exact same backing level as the Federal Deposit Insurance Corporation (FDIC) coverage offered by traditional commercial banks.
Eligibility and Membership Requirements in Canyon County
To access the financial products and services offered by a credit union in Nampa, individuals must meet specific field-of-membership criteria established in the credit union’s charter. Field-of-membership rules ensure that credit unions serve a defined community or group with a common bond.
Common Pathways to Membership
- Geographic Qualification: Most community-chartered credit unions operating in Nampa permit anyone who lives, works, worships, or attends school in Canyon County, Ada County, or surrounding Treasure Valley regions to join.
- Employment & Organization Affiliation: Certain credit unions originally founded for specific employee groups—such as school district staff, healthcare workers, municipal employees, or utility workers—continue to serve those specific employer groups alongside broader community memberships.
- Family Relationships: Immediate family members of existing credit union members (including spouses, children, parents, siblings, grandparents, and grandchildren) are almost universally eligible to join, regardless of where the family member resides.
- Association Memberships: Some institutions allow individuals to qualify by joining an affiliated non-profit organization or alumni association operating within Idaho.
To establish membership, applicants must open a basic savings account, commonly referred to as a Share Savings Account. The member deposits a nominal sum—typically between $5 and $25—which serves as their ownership share in the cooperative. This share must remain on deposit for the duration of the account lifetime to maintain active membership and retain access to loan products, specialized checking accounts, and commercial services.

Core Deposit Accounts Offered by Nampa Credit Unions
Credit unions in Nampa provide a broad spectrum of deposit products designed to support daily financial management, short-term budgeting, and long-term wealth preservation.
1. High-Yield & Free Checking Accounts
Nampa credit unions emphasize low-cost, high-value transaction accounts. Unlike national banks that often impose monthly service fees unless high balance thresholds are met, credit union checking accounts frequently feature:
- No Monthly Service Charges: Routine checking accounts with zero monthly maintenance fees and no minimum balance mandates.
- Reward Checking Options: Accounts that pay premium interest rates or cash-back rewards when members meet basic monthly activity benchmarks (such as making a set number of debit card transactions, enrolling in electronic statements, and maintaining direct deposit).
- Debit Card Security Controls: Integrated mobile app features that allow members to lock cards, limit spending categories, and set instant transaction alerts.
2. Share Savings & Money Market Accounts
Share savings accounts form the foundational foundation of credit union membership. For higher liquid balances, credit unions offer Money Market Accounts (MMAs), which combine tiered, variable interest rates with limited check-writing capabilities. Money market rates at local credit unions historically outperform regional bank savings yields, allowing Canyon County depositors to earn higher returns while keeping their liquidity intact.
3. Share Certificates (CDs)
For savers seeking guaranteed returns over fixed timeframes, credit unions offer Share Certificates (the credit union equivalent of bank Certificates of Deposit). Features typically include:
- Terms ranging from 3 months to 60 months (5 years).
- Fixed annual percentage yields (APYs) that remain locked for the entire term.
- Specialty terms such as "add-on" certificates (allowing periodic deposits) or "bump-up" certificates (permitting a one-time rate increase if market yields rise).
4. Individual Retirement Accounts (IRAs)
Members preparing for retirement can open Traditional and Roth IRAs structured as tax-advantaged share savings or share certificates. These accounts help local residents accumulate funds for retirement within a safe, NCUA-insured framework.
Consumer Borrowing & Lending Solutions
Lending represents one of the primary areas where Nampa credit unions deliver measurable financial value. Because credit unions operate with lower overhead margins and prioritize member satisfaction over profit optimization, borrowing rates across personal, vehicle, and residential mortgage categories are frequently among the most competitive in Idaho.
- Auto & Outdoor Recreation Loans
- New & Used Vehicles
- RVs, Boats, Campers & ATVs/UTVs
- Residential Mortgages
- Conventional, FHA, VA & USDA
- Idaho Housing & Finance (IHFA) Programs
- Home Equity Financing
- Home Equity Lines of Credit (HELOCs)
- Fixed-Rate Home Equity Loans
- Personal Lines & Rewards Credit Cards
- Low Fixed/Variable APR Cards
- Cash-Back & Travel Rewards Programs
Auto and Recreational Vehicle Financing
Outdoor recreation is an integral part of life in the Treasure Valley. Consequently, Nampa credit unions provide specialized vehicle financing options tailored to local lifestyle needs:
- New and Used Auto Loans: Flexible financing terms extending up to 72 or 84 months, often featuring streamlined online pre-approval processes and direct dealer integration across Nampa and Caldwell auto dealerships.
- Recreational Vehicle (RV) and Boat Loans: Specialized long-term loans designed for travel trailers, motorhomes, pontoon boats, and speedboats.
- ATV, UTV, and Dirt Bike Loans: Financing tailored for off-road vehicles, snowmobiles, and personal watercraft popular in southwestern Idaho's public land access areas.
Residential Mortgages & Home Equity Solutions
Navigating the Treasure Valley real estate market requires accessible home financing. Nampa credit unions work closely with buyers by offering localized processing, underwriting, and loan servicing:
- Conventional Mortgages: Fixed-rate and adjustable-rate mortgages (ARMs) for primary residences, second homes, and investment properties.
- Government-Backed Loans: FHA loans with low down-payment requirements, VA loans with zero down-payment requirements for military veterans, and USDA Rural Development loans for qualifying properties on the outskirts of Canyon and Owyhee counties.
- Down Payment Assistance: Participation in specialized state programs run by the Idaho Housing and Finance Association, which assist first-time homebuyers with down payment grants and low-interest second mortgages.
- Home Equity Lines of Credit (HELOCs) & Fixed Equity Loans: Tools allowing homeowners to tap accrued home equity to fund residential renovations, consolidate higher-interest debt, or pay educational expenses.
Credit Cards and Personal Loans
Credit unions in Nampa offer personal credit lines and credit cards with consumer-friendly terms governed by federal caps. Key offerings include:
- Low-APR Credit Cards: Cards built for balance transfers or ongoing purchases, avoiding penalty APR spikes or hidden annual fees.
- Rewards Cards: Options providing cash-back, points, or travel perks without inflated interest structures.
- Personal & Debt Consolidation Loans: Unsecured fixed-rate loans that help members combine high-interest commercial bank or store credit card balances into a single manageable monthly payment.
Business Banking and Commercial Services
As Nampa has grown into a major commercial and industrial hub within Canyon County, local credit unions have expanded their business banking divisions to support entrepreneurs, local agriculture, and small-to-medium enterprises (SMEs).
1. Commercial Checking & Cash Management
Nampa credit unions offer tailored business checking accounts that accommodate varying monthly transaction volumes. Business services include:
- Merchant services for processing credit and debit card payments.
- Remote deposit capture, allowing businesses to deposit checks via desktop scanners or mobile devices.
- Payroll services and Automated Clearing House (ACH) origination for employee payments and vendor disbursements.
2. Commercial Real Estate (CRE) & Equipment Loans
Local business owners can access capital to purchase operating facilities, expand warehouses, or procure equipment:
- Owner-Occupied Real Estate Financing: Competitive long-term loans for commercial buildings, retail space, and industrial facilities in Nampa's business corridors (such as Caldwell Boulevard, Garrity Boulevard, and Idaho Center Boulevard).
- Equipment & Fleet Financing: Loans structured to acquire machinery, heavy equipment, delivery vehicles, and agricultural implements.
3. SBA Lending Options
Many Nampa credit unions hold preferred lender status with the U.S. Small Business Administration (SBA). Programs like SBA 7(a) and SBA 504 loans provide government-backed guarantees that allow credit unions to extend long-term, low-down-payment financing to startups and expanding small businesses that might not qualify under traditional commercial lending guidelines. Detailed guidance on federal borrowing safeguards can be reviewed through the Consumer Financial Protection Bureau.
Digital Banking and Branch Access Features
While credit unions emphasize local, face-to-face member service, they also provide digital capabilities comparable to large national banking institutions.
| Feature Category | Member Benefit |
|---|---|
| Mobile Banking Applications | Remote check deposit, P2P transfers, real-time alerts. |
| Shared Branching (CO-OP Network) | Perform in-branch transactions at over 5,600 locations. |
| Surcharge-Free ATM Access | Access 30,000+ ATMs nationally via CO-OP / MoneyPass networks |
| Electronic Document & Signature Integration | Apply for loans and sign paperwork fully online. |
Mobile and Online Banking Architecture
Modern Nampa credit unions provide mobile apps for iOS and Android platforms, featuring:
- Remote Mobile Check Deposit.
- Person-to-Person (P2P) payment integrations (such as Zelle or integrated credit union transfer platforms).
- Comprehensive credit score monitoring and financial wellness tracking.
- Digital wallet integration with Apple Pay, Google Pay, and Samsung Pay.
Shared Branching and Surcharge-Free ATM Networks
A common concern for prospective members is whether a local credit union can match the national footprint of mega-banks. Nampa credit unions solve this through participation in cooperative networks:
- CO-OP Shared Branching: Participating credit unions allow members to walk into any other participating credit union branch nationwide—over 5,600 locations—and perform deposits, withdrawals, loan payments, and account transfers as if they were in their home branch in Nampa.
- CO-OP and MoneyPass ATM Networks: Members gain surcharge-free access to over 30,000 ATMs across North America, located inside participating credit union branches, retail stores, and convenience chains.
Comparison: Nampa Credit Unions vs. Traditional Commercial Banks
Evaluating whether to manage your finances through a local credit union or a commercial bank depends on your specific priorities regarding interest yields, technology, local service, and fee structures.
| Feature / Metric | Nampa Credit Unions | Traditional Commercial Banks |
|---|---|---|
| Ownership Structure | Member-owned cooperative (1 member = 1 vote) | Investor-owned corporation (votes linked to shares) |
| Primary Mandate | Maximize member value and local benefits | Maximize shareholder profits |
| Deposit Insurance | NCUA (NCUSIF) up to $250,000 | FDIC up to $250,000 |
| Average Deposit Rates | Generally higher yields on savings & CDs | Generally lower yields on basic savings |
| Average Loan Rates | Typically lower APRs across auto/mortgages | Typically higher APRs across consumer loans |
| Fee Structures | Lower fee frequency; easier fee waiver thresholds | Higher fee frequency (monthly maintenance, overdraft) |
| Branch Footprint | Local/regional branches + CO-OP Shared Network | Proprietary national branch networks |
| Community Impact | Reinvests capital into Canyon County / Treasure Valley | Capital allocated globally across corporate priorities |
How to Select and Apply to a Nampa Credit Union
Transitioning your financial services to a credit union in Nampa involves a straightforward, step-by-step process.
- Step 1: Verify Membership Eligibility
- Live, work, or worship in Canyon/Ada County
- Step 2: Select Financial Institution & Account Types
- Compare checking, yields, & branch locations
- Step 3: Gather Verification Documentation
- Government ID, SSN/ITIN, & Proof of Address
- Step 4: Open Account & Fund Share Deposit
- Complete initial $5–$25 membership deposit
- Step 5: Transition Direct Deposits & Auto-Pay Items
- Move recurring transactions to new account
Step 1: Confirm Your Eligibility
Review the field-of-membership requirements for the Nampa credit unions you are evaluating. Most residents qualify based on living or working in Canyon County or the Treasure Valley.
Step 2: Compare Rates, Fees, and Branch Convenience
Analyze the credit union's current deposit yields, loan interest rates, fee schedule, and mobile banking functionality. Consider the physical location of branches along major Nampa traffic corridors—such as 12th Avenue Road, Caldwell Boulevard, Karcher Road, or Midland Boulevard—if in-person services are important to you.
Step 3: Gather Required Documentation
To comply with federal Customer Identification Program (CIP) regulations, prepare the following documents before applying online or visiting a branch:
- Valid unexpired government-issued photo ID (Driver’s License, State ID, or Passport).
- Social Security Number (SSN) or Individual Taxpayer Identification Number (ITIN).
- Physical proof of residence in Idaho (utility bill, lease agreement, or pay stub dated within 60 days if your ID address is not current).
Step 4: Open Account and Fund Initial Share Deposit
Complete the membership application online or at a local Nampa branch. Deposit the required membership share amount (typically $5 to $25) into your main Share Savings Account using cash, a check, or a debit card transfer.
Step 5: Switch Direct Deposits and Automatic Payments
Once your account is active:
- Provide your employer’s payroll department with your new credit union routing number and account number to transfer direct deposits.
- Update recurring auto-pay schedules (utilities, insurance, subscriptions) with your new credit union debit card or checking account details.
- Keep your old bank account open with a minimal balance until all outstanding checks and automated charges clear, then close the old account.
Important Financial Considerations & Regulatory Disclosures
- Interest Rate Volatility: Dividend yields on savings, checking, and money market accounts are variable and subject to change based on market conditions established by the Federal Open Market Committee (FOMC) and regional financial metrics.
- Loan Approval Terms: All loan products (auto, home, personal, and commercial) are subject to credit approval, income verification, and underwriting guidelines. Rates offered vary based on individual credit scores, loan-to-value (LTV) ratios, and term lengths.
- Regulatory Compliance: Federal credit unions operate under regulations enforced by the NCUA, while state-chartered credit unions fall under the supervision of the Idaho Department of Finance.
Frequently Asked Questions (FAQs)
Are deposits at credit unions in Nampa as safe as those at commercial banks?
Yes. Deposits at federally insured credit unions are backed by the National Credit Union Share Insurance Fund (NCUSIF), an arm of the federal government administered by the NCUA. It insures individual member deposits up to $250,000 per owner, per institution—providing identical safety and backing to FDIC insurance at commercial banks.
Can I still use my debit card or visit a branch if I travel outside Idaho?
Yes. Most Nampa credit unions belong to the CO-OP ATM and Shared Branching Networks. This allows members to perform free ATM transactions at tens of thousands of locations nationwide and conduct in-person branch transactions at participating partner credit union branches across all 50 states.
What is the difference between a share savings account and a regular savings account?
A share savings account is functionally identical to a traditional bank savings account, but with a different legal structure. Your deposit represents an ownership share in the cooperative. Earnings paid on these accounts are called "dividends" rather than "interest," though they are calculated and taxed similarly.
Do Nampa credit unions offer home loans for first-time buyers?
Yes. Local credit unions specialize in home buyer programs, including conventional fixed-rate mortgages, FHA, VA, and USDA loans. They also participate in Idaho Housing and Finance Association (IHFA) programs, which provide down payment and closing cost assistance to qualifying first-time home buyers in Canyon County.
Can I open a business account at a local credit union if I operate a small business in Nampa?
Yes. Credit unions offer comprehensive business services, including business checking, commercial real estate loans, equipment financing, lines of credit, and SBA loan options for businesses operating in Nampa and the wider Treasure Valley.
Next Steps for Securing Local Credit Union Services in Nampa
Choosing a local credit union in Nampa, Idaho allows you to manage personal and business finances through a member-owned cooperative focused on returning value to the Canyon County community.
To get started, evaluate your current financial priorities:
- If you are seeking lower financing costs on a vehicle or home purchase, request pre-approval quotes from local credit unions operating in Nampa.
- If you are paying monthly maintenance fees on a bank checking account, compare no-fee checking and high-yield savings options at nearby credit union branches along 12th Avenue, Caldwell Boulevard, or the Idaho Center corridor.
- Verify your field-of-membership eligibility online, gather your identification documents, and open your initial share savings account to unlock full cooperative membership benefits.
Image Gallery
Select an image to open it in a new tab.

Simon Caldwell
Enterprise Technology and Systems Editor
