
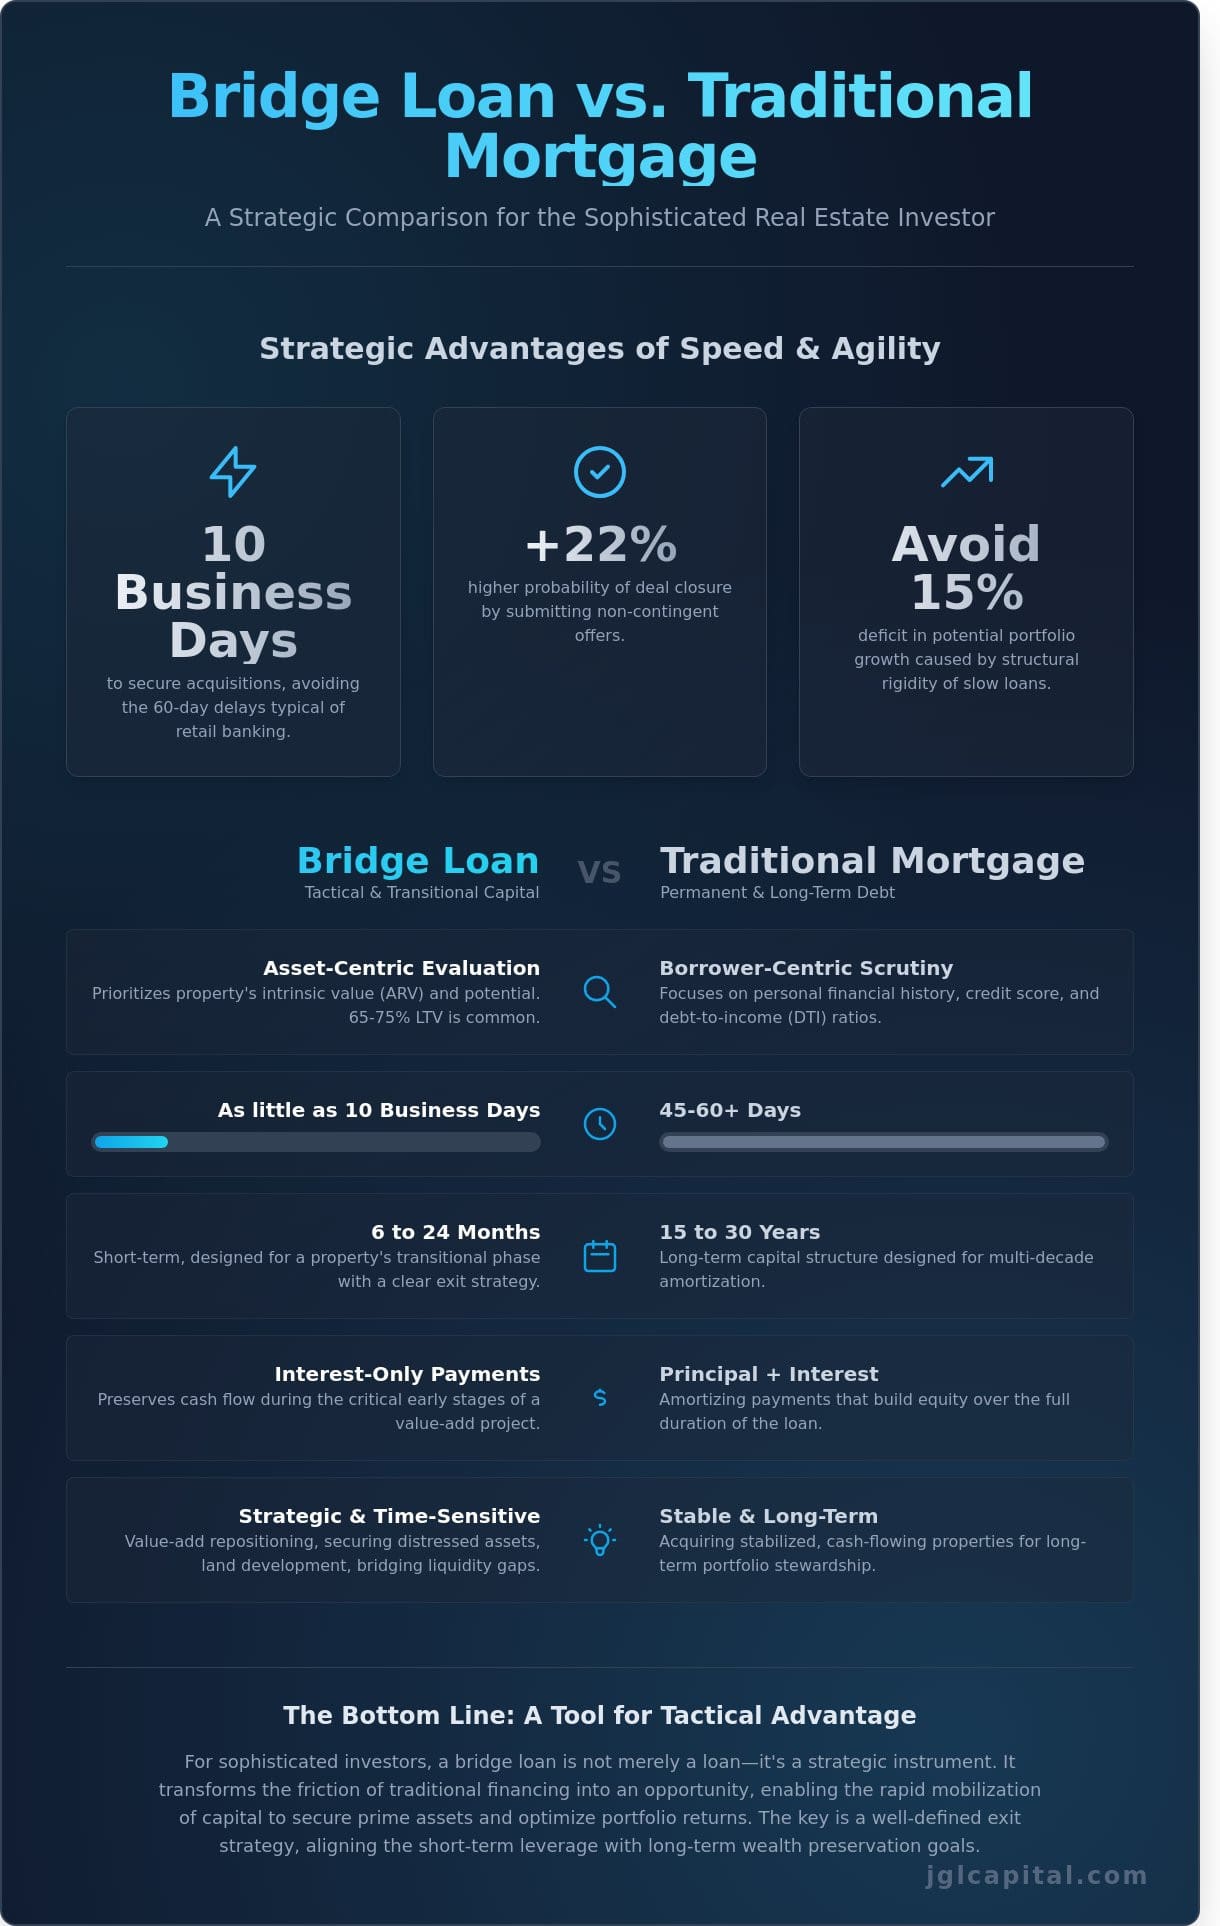
A mortgage bridge loan is a short-term financing tool designed to provide immediate liquidity, allowing homeowners to purchase a new property before their existing residence is sold. By "bridging" the financial gap between the purchase of a new asset and the liquidation of a current one, these loans eliminate the need for home sale contingencies in competitive real estate markets.
The Strategic Function of Bridge Loans in 2026
In the current 2026 real estate landscape, the speed of transactions often dictates the success of a buyer’s offer. A mortgage bridge loan serves as a temporary capital infusion, typically lasting between six months and one year. Its primary role is to unlock the equity tied up in a borrower’s current home so it can be used as a down payment on a subsequent property.
For many years, the standard real estate transaction involved a "chain" of sales: Buyer A buys Home B only after Home A sells. However, in low-inventory or high-demand environments, sellers are increasingly reluctant to accept offers contingent upon the buyer selling their own home. A bridge loan effectively turns a "contingent buyer" into a "non-contingent buyer," significantly strengthening their negotiating position. This shift in status is often the deciding factor in multi-offer scenarios where sellers prioritize certainty and speed.
The role of the bridge loan extends beyond mere convenience. It serves as a risk management tool for those who have found their "forever home" but haven't yet listed their current property. Instead of rushing a sale and potentially accepting a lower price to meet a closing deadline, the borrower uses the bridge loan to secure the new property first, then takes the necessary time to market and sell their old home at its maximum valuation.
How Mortgage Bridge Loans Operate
The mechanics of a bridge loan are distinct from traditional 30-year fixed mortgages or even standard home equity lines of credit (HELOCs). Lenders generally structure these loans in one of two ways:
- The Integrated Lien: The lender provides a single loan that pays off the existing mortgage on the first home and provides the down payment for the second. The remaining balance is then used to bridge the period until the first home sells.
- The Second Lien: The bridge loan acts as a secondary mortgage against the current home. The borrower keeps their original mortgage in place and uses the bridge loan funds specifically for the down payment and closing costs of the new property.
Payment Structures and Timelines
Bridge loans are not intended for long-term debt management. Most agreements feature interest-only payments or even deferred interest, where the borrower makes no payments until the loan is paid off in full upon the sale of the original home. This is particularly useful for borrowers who may struggle to carry two full mortgage payments simultaneously (the old mortgage and the new mortgage).
The "balloon payment" is a hallmark of this product. Since the term is short, the entire principal balance is due at the end of the term—usually 6 to 12 months. This requires the borrower to have a firm exit strategy, which is almost always the successful sale of the primary residence.
Eligibility and Technical Requirements
Securing a bridge loan in 2026 requires a high degree of financial stability. Because these loans carry higher risks for the lender—namely the possibility that the first home will not sell before the loan matures—the underwriting criteria are often more stringent than standard residential mortgages.
Equity and Loan-to-Value (LTV) Ratios
The most critical factor is the amount of equity in the "departure residence." Lenders typically limit the combined loan-to-value (CLTV) ratio to 80%. This means that if you add your existing mortgage balance to the requested bridge loan amount, the total cannot exceed 80% of your current home’s appraised value. This 20% cushion protects the lender if the property sells for less than expected or if market values dip.
Debt-to-Income (DTI) Considerations
While some bridge loan programs allow for "asset-based" underwriting, most traditional lenders still look closely at the borrower’s Debt-to-Income (DTI) ratio. The lender must be confident that the borrower can theoretically manage the debt load of both properties if the sale of the first home is delayed. In 2026, many lenders look for a DTI of 43% or lower, though some private lenders may offer more flexibility for a higher interest rate.
Credit Score and Liquidity
A credit score of 700 or higher is generally expected. Furthermore, lenders may require proof of "cash reserves"—usually six months of carrying costs for both properties—to ensure the borrower can handle unexpected delays in the real estate market.
The Costs Associated with Bridging Finance
Bridge loans are more expensive than traditional financing. Borrowers must weigh the high cost against the strategic advantage of securing a property without a contingency.
- Interest Rates: In 2026, bridge loan rates typically sit 2% to 4% higher than the prevailing 30-year fixed mortgage rate. This reflects the short-term nature of the loan and the administrative costs of processing a loan that will only be on the books for a few months.
- Origination Fees: Expect to pay "points" (1% to 2% of the loan amount) as an upfront fee to the lender.
- Appraisal and Closing Costs: Since the bridge loan is a separate legal mortgage, it requires a full appraisal of the current home, title search fees, and recording fees. These can add several thousand dollars to the total cost.
- Administration Fees: Some lenders charge "draw fees" or "document preparation" fees specifically for short-term products.
| Feature | Mortgage Bridge Loan | Home Equity Line of Credit (HELOC) | Contingent Offer |
|---|---|---|---|
| Typical Term | 6–12 Months | 10–30 Years | N/A |
| Interest Rate | High (Prime + 2-4%) | Moderate (Variable) | N/A |
| Payment Type | Interest-only or Balloon | Interest-only or P+I | No Loan Needed |
| Approval Speed | Fast (2–3 weeks) | Moderate (4–6 weeks) | N/A |
| Main Advantage | No contingency needed | Lower interest rates | No debt risk |
| Main Risk | Balloon payment due | Long-term debt | Offer may be rejected |
Risks and Mitigation Strategies
The most significant risk of a bridge loan is the failure to sell the original property before the loan term expires. If the house remains on the market after 12 months, the borrower faces a balloon payment they may not be able to afford.
Market Stagnation
If interest rates rise or local demand shifts, a property that was expected to sell in 30 days might sit for six months. Borrowers should have a "Plan B." This might include a pre-arranged agreement with the lender to extend the bridge loan for a fee or the ability to convert the bridge loan into a traditional second mortgage or a rental property loan if the home is moved to the lease market instead.
Under-Appraisal
If the departure residence appraises for less than anticipated, the bridge loan amount may be reduced, leaving the borrower short of the necessary funds for the new purchase. To mitigate this, borrowers should obtain a professional "pre-appraisal" or a highly conservative Comparative Market Analysis (CMA) from a qualified Realtor before applying for the loan.
Comparing Alternatives to Bridge Loans
Before committing to the high costs of a bridge loan, savvy real estate participants in 2026 explore several alternatives that may achieve similar goals with less risk or lower fees.
1. HELOC (Home Equity Line of Credit)
If a homeowner plans their move well in advance, they can open a HELOC while their current home is not yet listed for sale. HELOCs generally have lower interest rates and lower closing costs than bridge loans. However, most lenders will not approve a HELOC on a home that is already on the market. Therefore, the HELOC must be secured before the listing process begins.
2. 401(k) Loans
For borrowers with significant retirement savings, taking a loan against a 401(k) can provide a quick source of down-payment cash. The interest is paid back to the borrower's own account, and there is no impact on the DTI ratio. However, these loans are usually capped at $50,000, which may not be sufficient for a down payment in many 2026 housing markets.
3. Sale-Leaseback Agreements
Modern fintech companies and some private investors offer "buy-before-you-sell" programs. In these arrangements, the company buys the new home for you or buys your current home and leases it back to you until you move. While convenient, these services often charge service fees ranging from 1% to 3% of the home value.
4. Cross-Collateralization
Some private banks and portfolio lenders allow borrowers to use both the old and new properties as collateral for a single large loan. This avoids the "bridge" structure entirely but requires significant total equity and is usually reserved for high-net-worth individuals.
Steps to Secure a Bridge Loan
If you determine that a bridge loan is the right path, follow these steps to ensure a smooth transition:
- Assess Your Equity: Ensure you have at least 20-30% equity in your current home.
- Consult a Specialized Lender: Not all banks offer bridge loans. You may need to look at regional banks, credit unions, or private "hard money" lenders.
- Get a Realistic Valuation: Have your current home valued by a professional to determine exactly how much you can borrow.
- Coordinate the Closings: Your loan officer will need to work closely with the title companies for both the purchase of the new home and the eventual sale of the old one.
- List the Property Immediately: To minimize interest costs, the "departure residence" should be ready for the market the moment the bridge loan is funded.
Frequently Asked Questions
Can I get a bridge loan if my house is already under contract?
Yes. In fact, having a house under contract with a verified buyer makes bridge loan approval much easier and potentially less expensive. Lenders view this as a lower risk because the "exit strategy" is already in motion. This is often called a "closed-bridge" loan.
What happens if I can't sell my house within the bridge loan term?
If the term expires and the house hasn't sold, you must pay back the principal. Most lenders will offer a short extension (1–3 months) in exchange for an extension fee. If you still cannot pay, the lender could technically initiate foreclosure, though they usually prefer to work out a loan modification or allow you to convert the debt into a different product.
Are bridge loans available for first-time buyers?
Generally, no. By definition, a bridge loan requires an existing property with equity to serve as the "bridge." First-time buyers do not have a departure residence to leverage.
How long does the approval process take?
Bridge loans are designed for speed. While a traditional mortgage can take 30 to 45 days, a bridge loan can often be processed in 10 to 21 days, depending on the speed of the appraisal.
Is the interest on a bridge loan tax-deductible?
Tax laws in 2026 generally allow for the deduction of mortgage interest on up to $750,000 of qualified residence debt. However, because bridge loans are often used for "acquisition" of a new home, the rules can be complex. You should consult a tax professional to determine if the specific structure of your bridge loan qualifies for a deduction.
Final Recommendation
A mortgage bridge loan is a powerful, high-leverage tool best used by homeowners with significant equity and a high degree of confidence in their current property's marketability. It is an ideal solution for those who need to act quickly on a new property without the "chains" of a contingent offer. However, due to the higher interest rates and the risk of the balloon payment, it should only be utilized when a clear exit strategy—the sale of the original home—is imminent. For those with more time, a HELOC or a sale-leaseback may provide a more cost-effective alternative.
Image Gallery
Select an image to open it in a new tab.


Simon Caldwell
Enterprise Technology and Systems Editor
