Securing the Best Auto Insurance Rates in Texas for New Drivers: A Comprehensive Guide

For new drivers in Texas, finding affordable auto insurance involves balancing state-mandated coverage requirements with strategies like maintaining a clean driving record, selecting higher deductibles, and leveraging driver education discounts. Because insurance premiums for new motorists are significantly higher due to perceived risk, comparing quotes from multiple carriers is the most effective way to identify the best available rates.
Navigating the landscape of auto insurance as a new driver in Texas requires an understanding of both the state’s unique regulatory environment and the actuarial factors that influence your premium. As of 2026, the Texas Department of Insurance (TDI) oversees a competitive market where private carriers determine rates based on a complex array of personal and vehicle data. While insurance premiums for new drivers are inherently higher than those for experienced motorists—often due to a lack of driving history—strategic planning can substantially mitigate these costs.
Understanding Texas Auto Insurance Requirements
Before searching for the lowest premiums, it is essential to understand what you are required to purchase. Texas operates under an "at-fault" insurance system, meaning the person responsible for an accident is liable for the damages. To comply with the law, all drivers must carry at least the state-mandated minimum liability coverage, known as "30/60/25" coverage:
- $30,000 for bodily injury or death to one person in an accident.
- $60,000 for total bodily injury or death to multiple people in an accident.
- $25,000 for property damage per accident.
While these minimums satisfy the legal requirement for vehicle registration, they are rarely sufficient to protect a driver’s assets in the event of a significant collision. For new drivers, who may be at higher risk for minor fender benders, opting for higher liability limits—often referred to as "full coverage"—is a common recommendation to prevent out-of-pocket financial ruin.
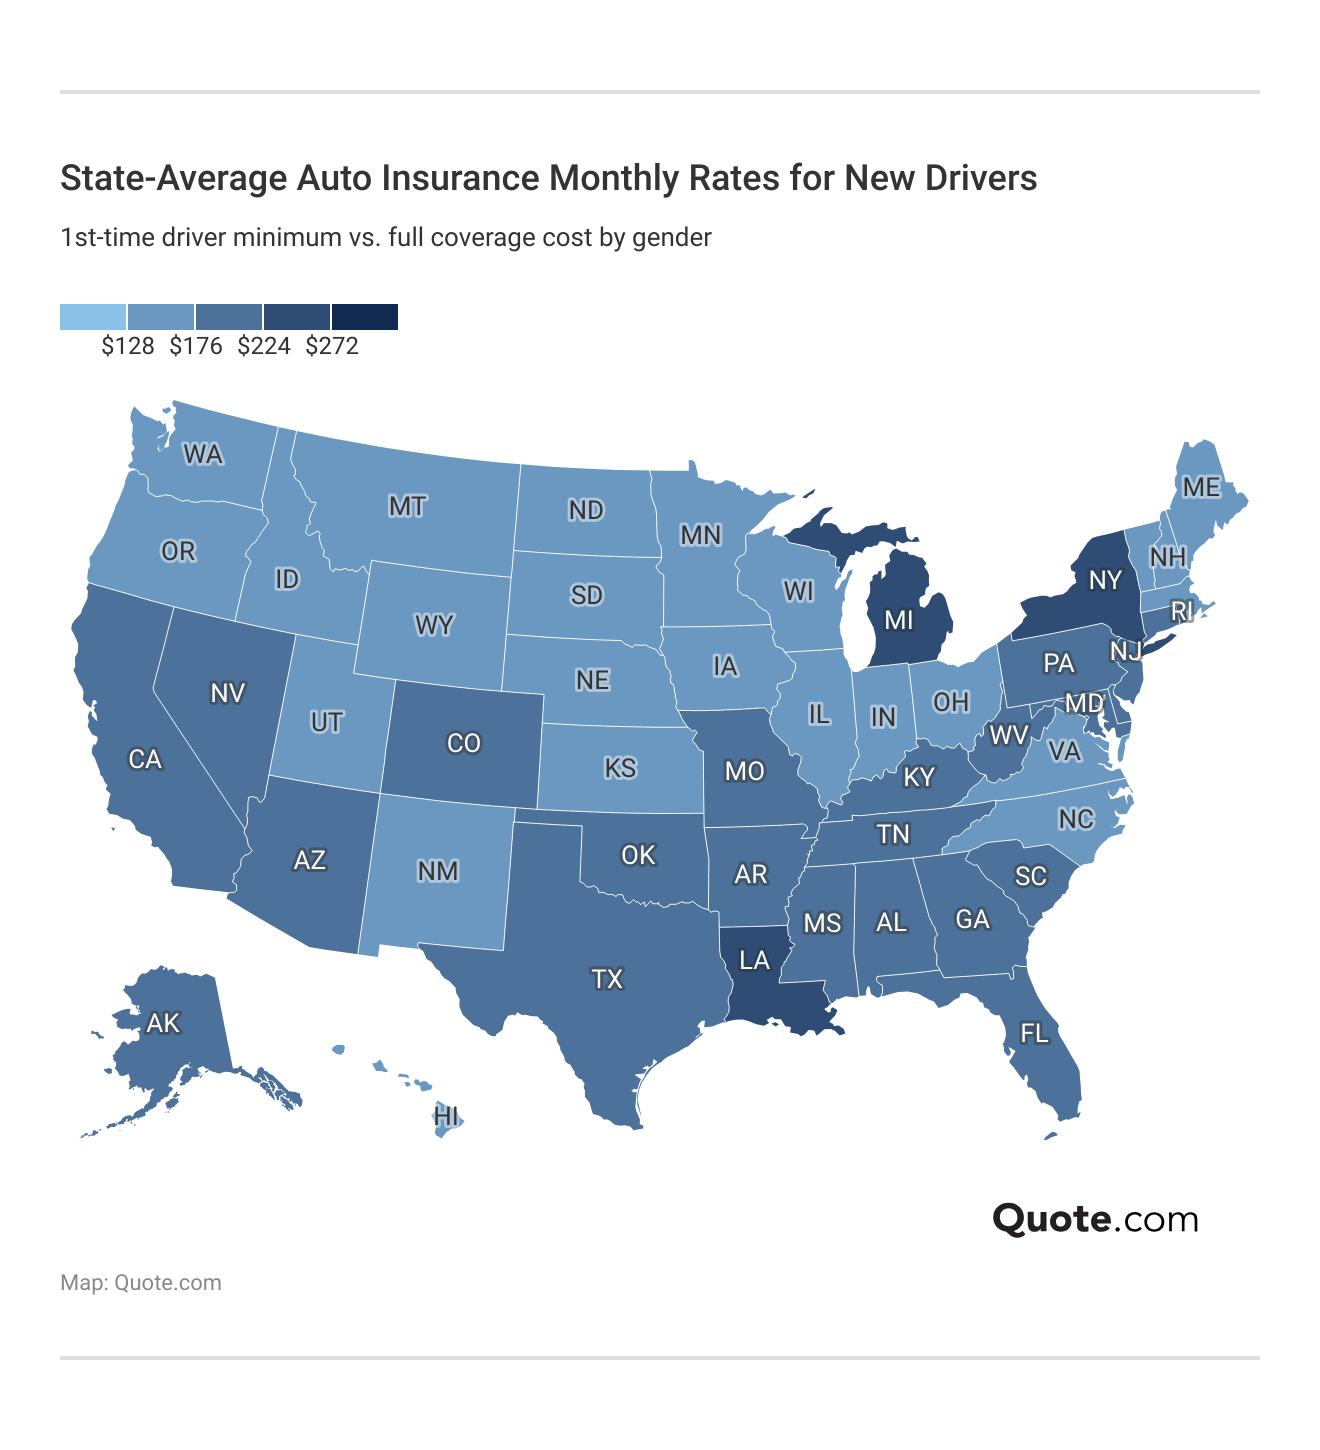
Why Rates Are Higher for New Drivers
Insurance companies use actuarial data to predict the likelihood of a claim. For new drivers, two primary variables drive costs upward: lack of experience and statistical risk.
Younger or newly licensed drivers lack the thousands of hours of road experience that allow an operator to anticipate hazards and respond effectively to shifting traffic conditions. Consequently, insurance carriers treat these drivers as "high-risk" until they reach a certain age—typically 25—or until they establish a multi-year history of incident-free driving. Because the risk profile is higher, the premium—the price paid for the policy—is adjusted upward to offset the anticipated cost of potential claims.
Strategies to Lower Premiums in Texas
While you cannot immediately change your age or years of experience, you can influence other rating factors that carriers use to calculate your quote.
1. The Role of Driver Education
In Texas, completing an approved driver education course is mandatory for many younger drivers to obtain a license. However, even if not strictly required, many insurance companies offer "good student" or "driver safety" discounts. Providing proof of completion for advanced defensive driving courses can often trigger a percentage-based discount on your premium.
2. Vehicle Selection
The type of vehicle you drive significantly impacts your insurance rate. Insurers look at the cost of parts, safety ratings, and the likelihood of theft for specific models. Sports cars, luxury vehicles, and models with expensive electronic sensors are significantly more expensive to insure than reliable, mid-range sedans with high safety ratings. If you are a new driver, selecting a vehicle with a lower insurance risk profile can lead to substantial long-term savings.
3. Deductibles and Coverage Limits
The deductible is the amount you pay out-of-pocket before your insurance kicks in. By opting for a higher deductible (e.g., raising it from $500 to $1,000), you can lower your monthly premium. However, you must ensure you have the funds available in your savings to cover that higher deductible if an accident occurs.
4. Bundling and Multi-Policy Discounts
If you live with family, inquire about the "multi-car" or "household" discount. Adding a new driver to an existing parent’s policy is almost always cheaper than the new driver purchasing a separate, individual policy. Most carriers in Texas provide significant discounts for insuring multiple vehicles under one household umbrella.
Comparing Insurance Providers in Texas
The Texas insurance market is highly fragmented, with national providers (such as State Farm, Allstate, and Geico) competing alongside regional players. No single company offers the "best" rate for every driver, as each company uses its own proprietary algorithm to weight different risks.
| Factor | Impact on Premium | Recommendation |
|---|---|---|
| Driving Record | Very High | Maintain a clean record to avoid surcharges. |
| Credit Score | Moderate | Monitor credit health; it affects insurance scores in Texas. |
| Vehicle Type | Moderate | Choose vehicles with lower repair costs and high safety ratings. |
| Annual Mileage | Low to Moderate | Inquire about "low-mileage" discounts if you drive less. |
| Deductible | Moderate | Raise your deductible if you can afford the out-of-pocket cost. |
The Impact of Credit-Based Insurance Scores
In Texas, insurance companies are permitted to use credit-based insurance scores as one of many factors to determine your rate. This is distinct from a credit score used for a loan, though the two are correlated. An insurance score helps companies predict how likely a person is to file a claim. Maintaining a strong credit profile—by paying bills on time and keeping credit utilization low—can indirectly lead to lower auto insurance rates over time.
Common Mistakes to Avoid
When shopping for insurance as a new driver, avoid these common pitfalls that can lead to unnecessary expenses:
- Choosing Minimum Coverage to Save Money: While this lowers your immediate monthly bill, it exposes you to massive financial liability if you cause an accident with significant damages or injuries.
- Allowing Coverage to Lapse: Even a one-day gap in coverage can lead to higher rates when you eventually re-apply, as insurers view lapses as a sign of financial instability or irresponsibility.
- Failing to Update Information: Always inform your insurer of life changes, such as moving to a different ZIP code or purchasing a newer vehicle, as these can positively or negatively impact your rate.
- Not Shopping Around: Insurance rates fluctuate. You should request new quotes every renewal period (typically every six months) to ensure your current carrier is still providing the most competitive rate.
FAQ: Frequently Asked Questions
Does the ZIP code in Texas affect my insurance rate? Yes. Texas insurers use location-based data to calculate risk. Areas with higher rates of accidents, vehicle theft, or severe weather (such as hail-prone regions) typically have higher average premiums than rural areas with lower traffic density.
Will my rate automatically decrease when I turn 25? It is a common misconception that rates drop automatically at 25. While many insurers do reduce rates at this age, the decrease is generally gradual. The most significant drop in premiums occurs as you gain years of "incident-free" driving history.
Are there specific discounts for students? Yes. Most major insurers offer a "Good Student" discount for drivers under 25 who maintain a B average (3.0 GPA) or better. You will typically need to provide a recent report card or transcript to verify your eligibility for this discount.
What should I do if I am involved in an accident? First, ensure your safety and that of others. Contact law enforcement to file an official report, which is crucial for the insurance claims process. Exchange information with the other driver and take photos of the damage. Contact your insurance agent or use the carrier’s mobile application to report the claim as soon as possible.
Can I get a discount for taking a defensive driving course? Many Texas insurance providers offer discounts for state-approved defensive driving courses. These courses are often required for ticket dismissal, but voluntarily completing one can sometimes lead to a 5% to 10% reduction in your premium.
Should I choose a national carrier or a local Texas insurer? Both have advantages. National carriers often have robust mobile apps and 24/7 customer service. Local or regional insurers may offer more personalized service and sometimes have deeper knowledge of local market conditions. The best approach is to obtain quotes from both types of companies to see who offers the better value for your specific situation.
Next Actions for New Drivers
To secure the best rates, follow this systematic approach:
- Gather Documents: Have your driver’s license, vehicle registration (or the VIN of the car you intend to purchase), and your current driving history ready.
- Request Multiple Quotes: Use at least three different carriers—including one major national brand, one regional company, and one independent broker.
- Compare "Apples to Apples": Ensure that each quote uses the same coverage limits and deductibles. If one quote appears significantly cheaper, double-check that it isn't missing critical coverages like collision or comprehensive.
- Inquire About Discounts: Ask specifically about student discounts, safe driver discounts, and bundling opportunities.
- Finalize and Review: Once you choose a policy, review the declaration page to ensure all information is accurate. Set a calendar reminder to re-shop your policy six months before it expires to confirm you are still receiving a competitive rate.
By approaching your search for auto insurance with diligence and a clear understanding of the factors that influence your costs, you can secure protection that fits your budget and keeps you safe on Texas roads.
Image Gallery
Select an image to open it in a new tab.

Akira Tanaka
International Academic Trends Correspondent
