Understanding SSI Unearned Income Limits: Rules, Calculations, and Impact on Benefits
Supplemental Security Income (SSI) unearned income limits dictate how much financial assistance an individual can receive from sources other than traditional employment, such as Social Security benefits, pensions, or gifts, before their monthly federal benefit is reduced dollar-for-dollar. Managing these limits requires careful attention to the exclusions, exclusions calculations, and reporting requirements mandated by the Social Security Administration (SSA).
Introduction to Supplemental Security Income and Income Rules
Supplemental Security Income is a federal income supplement program funded by general tax revenues—not Social Security trust funds. Designed to help aged, blind, and disabled people who have little or no income, SSI provides cash to meet basic needs for food, clothing, and shelter. Because the program targets individuals with limited resources, the Social Security Administration enforces strict rules regarding how much money a recipient can take in each month.
To maintain financial eligibility, recipients must navigate two distinct income categories: earned income (money earned from a job or self-employment) and unearned income (money received from all other sources where no labor is performed). Understanding unearned income limits is vital because the SSA applies a much stricter lens to non-labor income. While the program encourages work by allowing various deductions on earned income, unearned income is generally counted dollar-for-dollar after a modest initial exclusion, directly shrinking the monthly SSI check.
Navigating these regulations requires an understanding of how the SSA defines unearned income, how standard exclusions apply, and what happens when those limits are exceeded. This comprehensive guide breaks down the core concepts, calculation methods, and strategic considerations required to protect benefits while maintaining financial stability.
Defining Unearned Income Under SSA Guidelines
Unearned income encompasses all receipts and cash inflows that do not stem from active employment or labor. For the purpose of SSI eligibility, the SSA categorizes virtually any financial transfer into an individual's household or personal account as either income or a resource.
Common examples of unearned income include:
- Social Security retirement, survivors, or disability benefits (SSDI)
- Veterans Administration (VA) benefits and pensions
- Railroad Retirement benefits
- Private pensions and retirement annuities
- Unemployment compensation
- Workers' compensation payments
- Dividends, interest, and royalties from investments
- Cash gifts from family members, friends, or charitable organizations
- Inheritances
- Prizes and winnings
- Support payments made by absent parents or family members
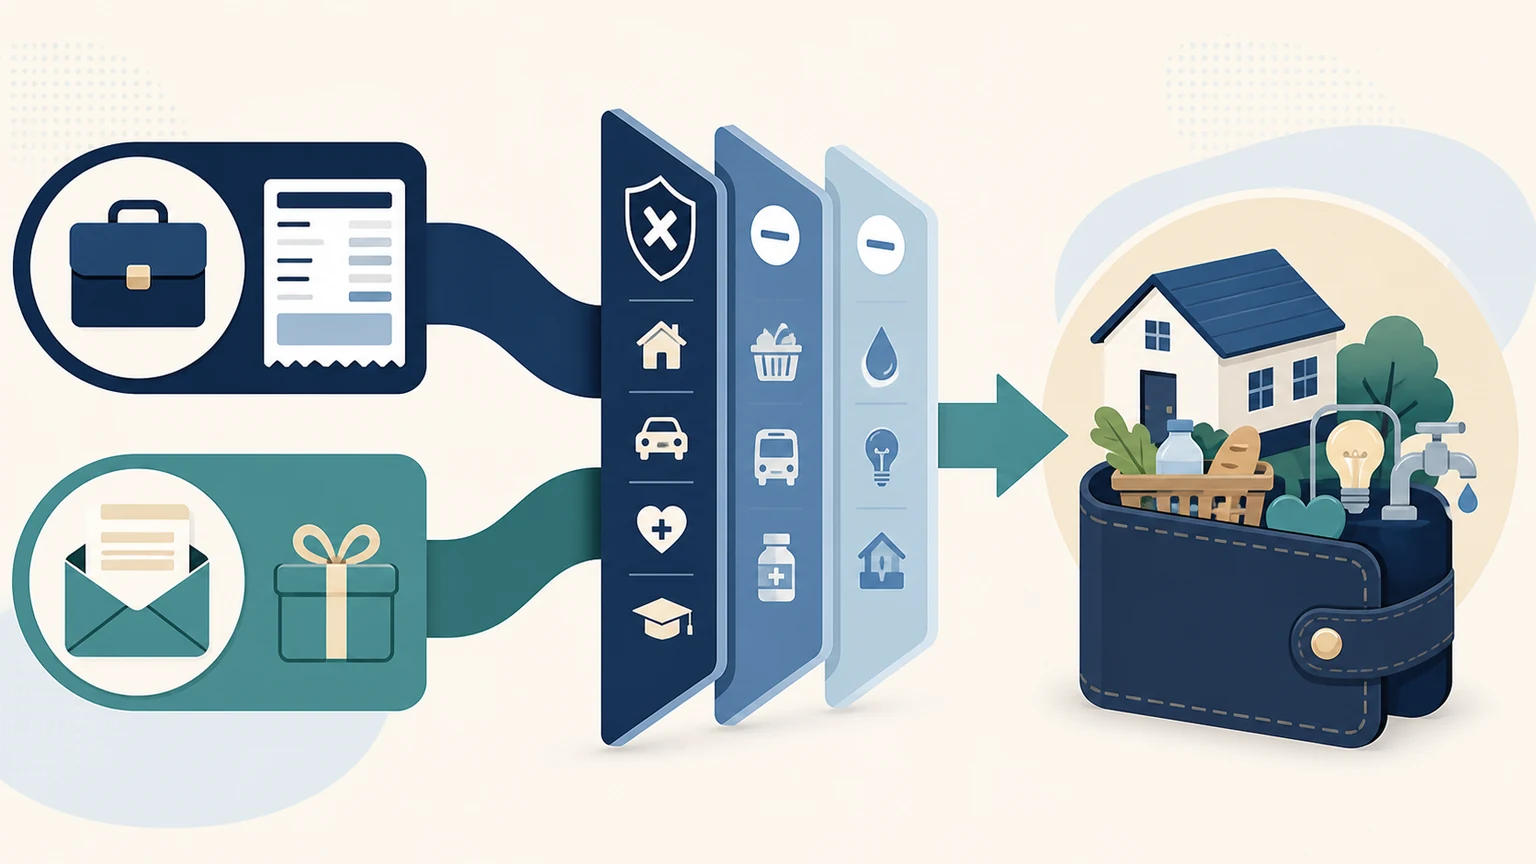
A critical distinction within SSI rules separates actual cash from In-Kind Support and Maintenance (ISM). ISM refers to food or shelter that someone else provides to the SSI recipient for free or at a reduced cost. For instance, if a family member allows an SSI recipient to live in a house rent-free or pays their utility bills, the SSA values that assistance as unearned income in the form of ISM, which can significantly reduce the monthly SSI payment.
The Federal Benefit Rate and the Basic Unearned Income Exclusion
The baseline for all SSI calculations is the Federal Benefit Rate (FBR), which sets the maximum monthly federal payment an eligible individual or couple can receive. The FBR changes periodically based on cost-of-living adjustments (COLA) determined by the federal government.
Against this baseline, the SSA applies a standard set of exclusions to determine countable income. When evaluating unearned income, the rules begin with a foundational buffer known as the General Income Exclusion.
| Exemption Type | Monthly Amount Excluded | Description and Application |
|---|---|---|
| General Income Exclusion | First $20 | Applied to the first $20 of unearned income received in a calendar month. |
| Infrequent/Irregular Income | Under $20 (earned) / Under $60 (unearned) | Money received so rarely or irregularly that it cannot be reasonably anticipated. |
| Needs-Based Assistance | Varies | Public assistance payments funded by the state or local government based on need. |
The application of the $20 General Income Exclusion is straightforward. If an individual receives no earned income, the SSA disregards the first $20 of their total unearned income per month. Any unearned income above that $20 threshold is considered "countable unearned income" and is subtracted dollar-for-dollar from the maximum federal benefit rate.
For example, if an individual's sole unearned income is a $300 monthly Social Security retirement benefit, the calculation proceeds as follows:
- Start with total unearned income: $300.
- Subtract the General Income Exclusion: $300 - $20 = $280.
- The remaining $280 is counted against the federal benefit rate. If the individual's maximum SSI federal benefit would otherwise be full, that monthly payment is reduced by $280.
How Unearned Income Directly Reduces Your SSI Payment
The mechanics of benefit reduction reveal why exceeding unearned income thresholds can rapidly erode SSI payments. Because unearned income is subjected to a direct, dollar-for-dollar reduction after the $20 exclusion, every additional dollar received from a pension, relative, or other non-work source strips away a dollar of federal support.
Consider a scenario where an individual relies on SSI and a small private pension. If the monthly pension payment increases—perhaps due to an annual cost-of-living adjustment within that private plan—the net result is not a larger total monthly income. Instead, the increase in unearned income triggers an immediate, proportional reduction in the SSI payment. The total combined income remains essentially static, but the administrative burden of reporting shifts to the recipient.
Furthermore, if total unearned income rises to a point where the countable portion exceeds the maximum Federal Benefit Rate (after accounting for the $20 exclusion and any other applicable special exclusions), the individual loses SSI eligibility entirely. When SSI eligibility terminates due to excess income, recipients often risk losing concurrent state-level benefits, such as Medicaid coverage, unless specific poverty-reduction or disability-continuation provisions apply.
Special Rules and Exceptions for Unearned Income
While the general rule enforces a strict dollar-for-dollar reduction, the Social Security Act includes several specific exceptions and specialized exclusions designed to protect vulnerable recipients from complete destitution under unique circumstances.
Infrequent or Irregular Income
The SSA recognizes that life includes unexpected, non-recurring financial events. Income that is received either infrequently or irregularly is excluded from calculations under specific dollar thresholds. Unearned income that is received infrequently or irregularly—meaning it cannot be reasonably anticipated or is received only once from a single source—is excluded up to $60 per calendar quarter. If a relative unexpectedly sends a $50 check for a holiday, that money may be entirely disregarded if it falls within this statutory exemption window.
Needs-Based Assistance and Disaster Relief
Assistance based on need, furnished by a state or local government or a political subdivision of a state, is generally excluded from unearned income calculations. Additionally, disaster assistance provided under the Disaster Relief and Emergency Assistance Act, or other federal assistance provided in response to a declared disaster, is excluded as unearned income and is not counted as a resource for a specified post-disaster period.
Student Earned Income Exclusion
Though primarily focused on earned income, students under the age of 22 who regularly attend school can benefit from exclusions that occasionally intersect with how educational grants, scholarships, and fellowships are treated. Most grants, scholarships, or fellowships used to pay tuition and educational fees are excluded from both income and resource calculations entirely, preventing educational funding from accidentally disqualifying a young adult from SSI support.
In-Kind Support and Maintenance (ISM) Calculations
No discussion of SSI unearned income limits is complete without a detailed examination of In-Kind Support and Maintenance. ISM is one of the most common pitfalls leading to unexpected SSI reductions or overpayments because recipients frequently fail to realize that non-cash help has a quantifiable dollar value in the eyes of the federal government.
When someone provides free food, free shelter, or both, the SSA must calculate the value of that support and treat it as unearned income. The agency generally applies one of two primary rules to calculate ISM:
- The One-Third Reduction Rule (VTR): If an SSI recipient lives in another person's household throughout a full calendar month and receives both food and shelter from that person, the SSA does not investigate the actual economic value of the room and board. Instead, the agency automatically reduces the maximum Federal Benefit Rate by exactly one-third. This is a flat-rate reduction regardless of whether the actual market value of the room and board is higher or lower than the one-third calculation.
- The Presumed Maximum Value Rule (PMV): If a recipient lives in their own household (renting or owning) but receives food or shelter from an outside source—or if they live in another household and do not receive both food and shelter—the PMV rule applies. Under PMV, the SSA presumes that the in-kind support has a maximum value equal to one-third of the FBR plus the $20 general exclusion, unless the recipient can prove that the actual economic value is lower.
Understanding ISM is critical for individuals living with family members or sharing housing arrangements. Informal living arrangements where rent is waived or groceries are consistently provided without reimbursement can trigger severe reductions in monthly SSI disbursements.
Reporting Requirements and Preventing Overpayments
The Social Security Administration places the legal burden of reporting income changes squarely on the SSI recipient, their representative payee, or their legal guardian. Failing to report unearned income in a timely manner is the leading cause of SSI overpayments, which the government aggressively recovers by withholding future benefit checks or demanding direct lump-sum repayments.
Timelines and Methods for Reporting
Recipients must report any change in income—including the start of a new pension, receipt of an inheritance, a change in monetary gifts, or a shift in living arrangements that alters ISM—by the 10th day of the month following the month in which the change occurred. For example, if a recipient receives an unexpected financial gift on May 15th, that change must be reported to the local Social Security office no later than June 10th.
Reporting can be conducted through several authorized channels:
- Contacting the local Social Security field office directly via phone or in-person appointment.
- Submitting documentation through the official online portals provided by the SSA, where available.
- mailing written notices containing complete details of the income source, amount, and date received.
Consequences of Failing to Report
When unearned income goes unreported, the SSA continues paying full monthly benefits based on outdated information. Once the discrepancy is discovered—often through automated cross-matching with internal revenue data, state databases, or banking records—the agency calculates an overpayment. The recipient receives a formal overpayment notice detailing the exact debt owed to the federal government. While waivers can be requested if the overpayment was not the recipient's fault and repayment would cause financial hardship, navigating overpayment disputes is time-consuming and emotionally taxing. Accurate, proactive reporting remains the safest defense.
Strategies for Managing Income and Protecting Benefits
For individuals navigating tight financial margins under SSI, proactive management of unearned income streams is essential to prevent unexpected benefit cuts or complete disqualification.
First, recipients and their caregivers should carefully evaluate the timing and structuring of financial assistance from family members. Rather than providing direct cash gifts or paying for household utility bills—which register directly as countable unearned income or ISM—families often explore authorized resource-building vehicles or formal legal trusts that comply with SSA regulations.
Second, maintaining meticulous records of every financial transaction is non-negotiable. Keeping a dedicated ledger or digital folder containing bank statements, gift letters, award letters from pension administrators, and receipts for shared living expenses ensures that if the SSA requests verification during a periodic review or redetermination, the data is readily accessible.
Finally, individuals should utilize official resources to stay informed about annual cost-of-living adjustments. Because the Federal Benefit Rate shifts annually, understanding how an FBR increase interacts with fixed unearned income sources prevents surprises when monthly deposits land in bank accounts. When in doubt regarding how an upcoming financial change—such as a small inheritance or a transition in living arrangements—will impact SSI eligibility, consulting directly with a specialized disability advocate or contacting the Social Security Administration before the transaction occurs can preserve financial stability.
Frequently Asked Questions
What happens if my unearned income exceeds the SSI limit in a single month?
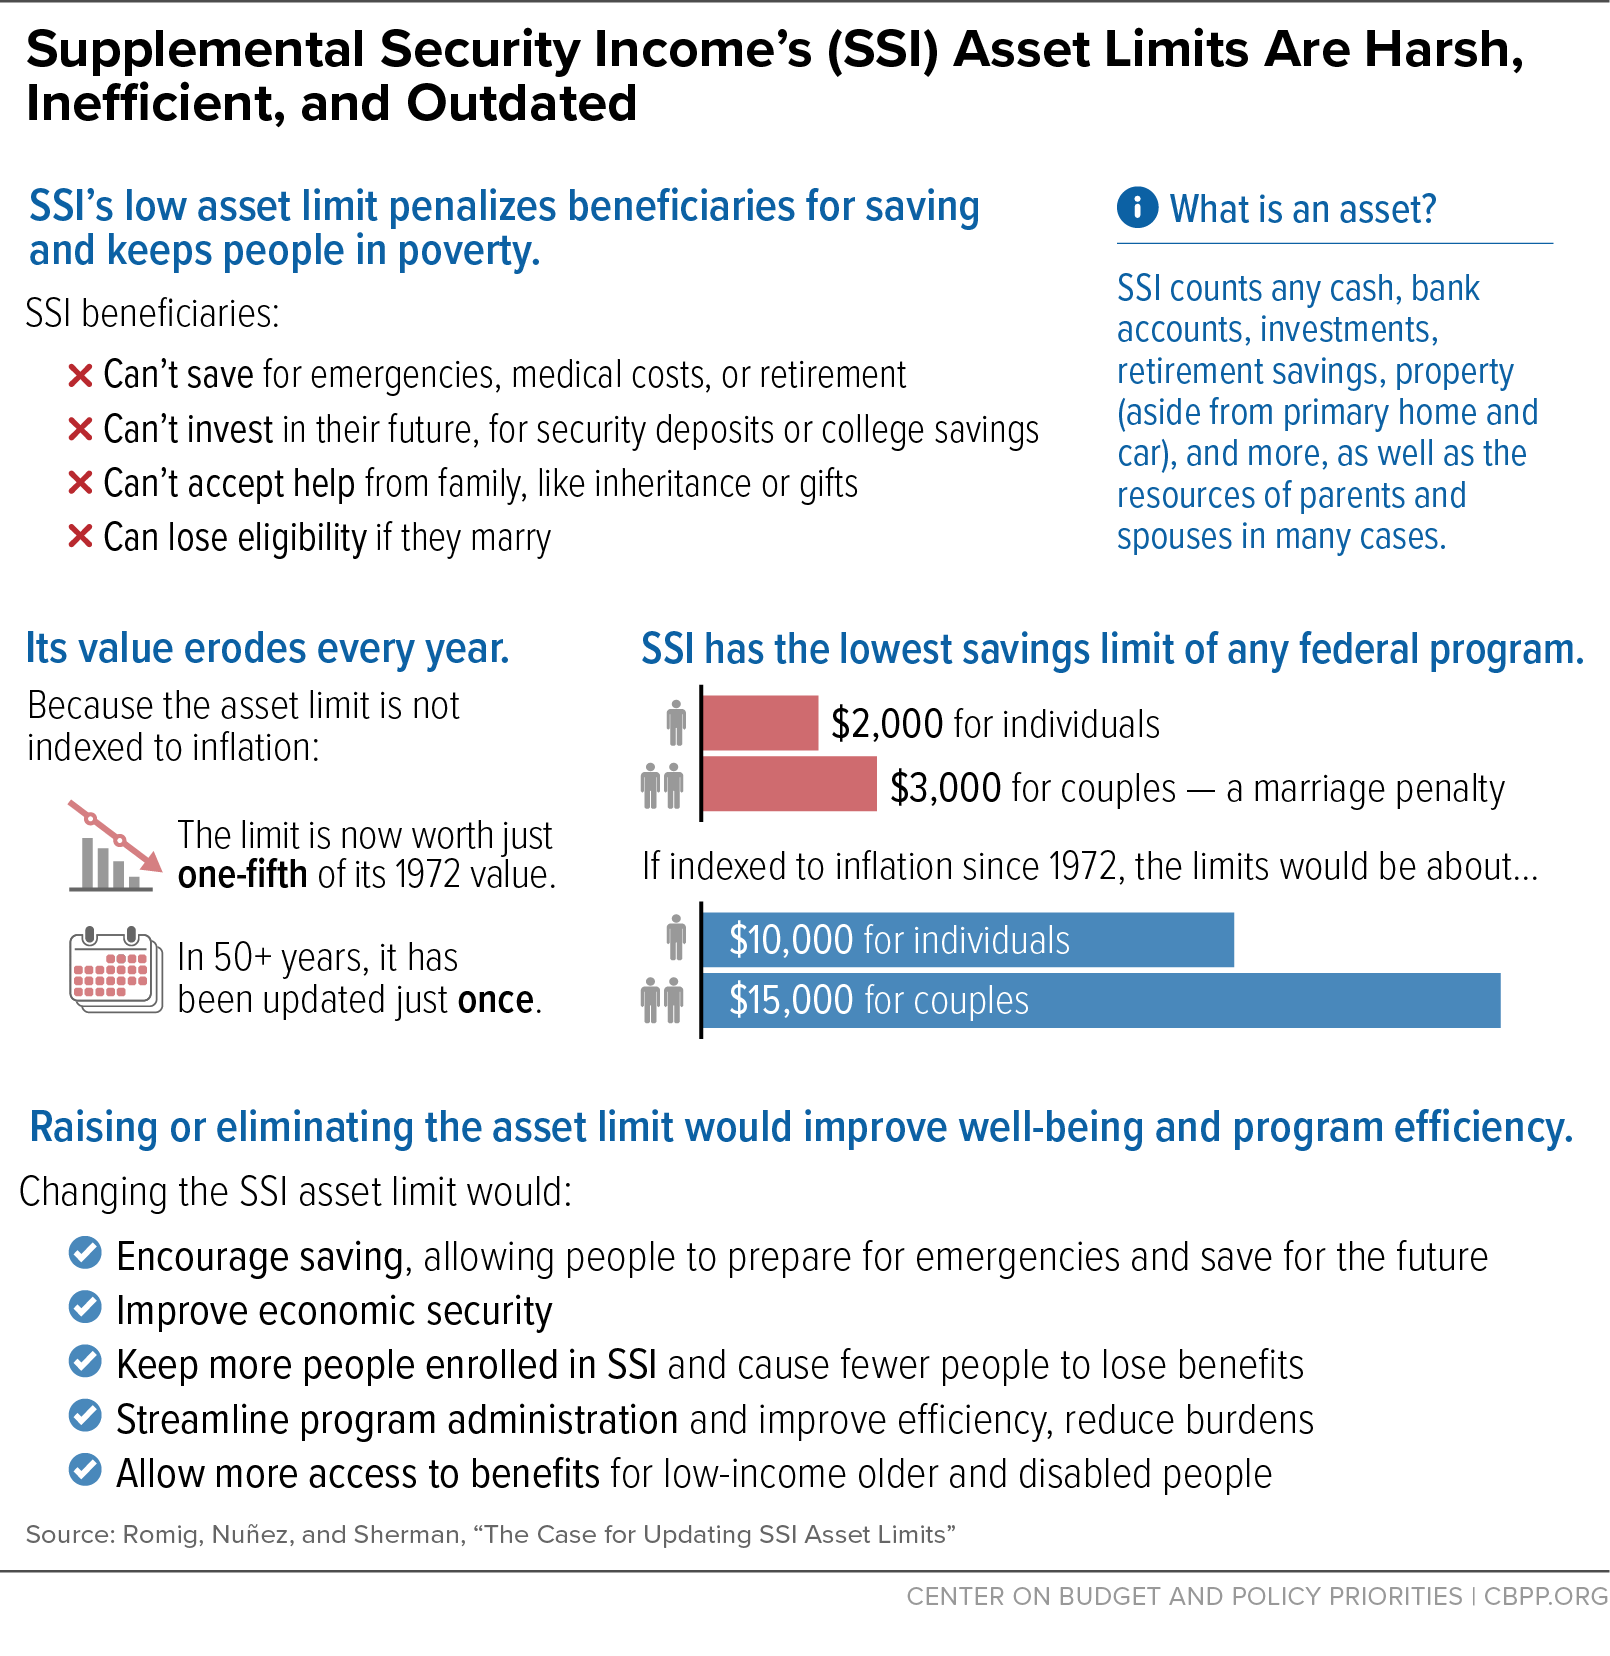
If unearned income spikes in a specific month—such as receiving a one-time cash award or inheritance—that income is counted for that specific month. If the total countable unearned income exceeds the Federal Benefit Rate for that month, you will not be eligible for an SSI payment for that month. However, if your income returns to normal the following month, your SSI benefits typically restart automatically without requiring a brand-new application, provided your resources do not exceed the $2,000 individual resource limit (or $3,000 for couples).
Are gifts from family members considered unearned income?
Yes. Cash gifts from family members, friends, or organizations are treated as unearned income in the month they are received. If the total unearned income for that month, combined with any other income, exceeds the $20 general exclusion, it will reduce your SSI payment dollar-for-dollar. Furthermore, if a gift is kept into the following calendar month, it transitions from being counted as income to being counted as a resource, which can threaten your eligibility if your total accumulated resources cross the statutory limit.
How does the SSA value free rent when calculating unearned income?
When someone provides free or subsidized shelter, the SSA values that assistance as In-Kind Support and Maintenance (ISM). If you live in someone else's household and receive both food and shelter, the SSA typically applies the One-Third Reduction Rule, automatically cutting your maximum federal benefit by one-third. If you live in your own home but someone else pays your rent or mortgage, the SSA applies the Presumed Maximum Value rule, capping the ISM value at one-third of the FBR plus $20, unless you can prove the actual economic value is lower.
Do child support payments count as unearned income for a child receiving SSI?
Yes. Child support payments received on behalf of a child with a disability are counted as the child's unearned income. However, the SSA applies specific rules to child support: one-third of child support payments made by an absent parent is excluded from income calculations. The remaining two-thirds, after applying the standard $20 general exclusion (if not already used against other income), is counted against the child's SSI benefit.
Where can I officially verify current SSI unearned income thresholds and limits?
The most accurate, up-to-date figures regarding Federal Benefit Rates and income exclusions are published directly by the federal government. You can review official policy manuals, spotlight on SSI rules, and update notices by visiting the Social Security Administration Official Website.
Conclusion
Managing SSI unearned income limits requires constant vigilance, precise record-keeping, and a thorough understanding of how non-labor funds interact with federal benefit calculations. Because the SSA enforces a strict dollar-for-dollar reduction policy for unearned income exceeding the baseline exclusions, even minor financial shifts can alter monthly disbursements. By proactively reporting changes, understanding complex rules like In-Kind Support and Maintenance, and utilizing official SSA guidance, recipients can safeguard their financial security and avoid the severe complications associated with unexpected overpayments.
Image Gallery
Select an image to open it in a new tab.

Akira Tanaka
International Academic Trends Correspondent
