IRS and Life Insurance Benefits: Tax Rules, Inclusions, and Reporting Requirements
Generally, life insurance death benefits paid to a beneficiary are received income tax-free, but specific rules apply depending on how the policy is structured, whether cash value is withdrawn, and if the policy is transferred for value. Understanding how the Internal Revenue Service (IRS) treats these financial instruments helps policyholders and beneficiaries avoid unexpected tax liabilities, penalties, and reporting oversights.
Navigating the intersection of tax law and life insurance requires a clear understanding of federal regulations, Internal Revenue Code (IRC) sections, and the distinction between term, whole life, and universal policies. While standard death benefits bypass income tax, various exceptions—such as interest-option payouts, employer-provided group term policies exceeding statutory limits, and modified endowment contracts—introduce complex compliance obligations.
Core Tax Principles of Life Insurance Death Benefits
The foundational rule governing life insurance taxation is found in Section 101(a) of the Internal Revenue Code. Under this statute, gross income does not include amounts received under a life insurance contract, if such amounts are paid by reason of the death of the insured. This exclusion applies whether the payment is made to a single beneficiary or to multiple beneficiaries, and it typically covers individual policies purchased directly from an insurance carrier.
However, this tax-free treatment is not absolute. The method of payout can alter the tax landscape, particularly when the beneficiary chooses to receive the death benefit in installments rather than as a lump sum.
Lump-Sum Payouts vs. Installment Options
When a beneficiary elects to receive the death benefit as a single lump sum, the entire amount is exempt from federal income taxation.
Conversely, if the beneficiary chooses an installment payment option, the principal amount (the face value of the policy) remains tax-free, but any interest earned on that principal after the insured’s death is treated as taxable ordinary income.
Insurance companies issue Form 1099-INT to report the interest portion of these installment payments, which the beneficiary must report on their federal income tax return.
The Transfer-for-Value Rule
An important exception to the tax-free death benefit rule is the transfer-for-value rule under IRC Section 101(a)(2). If a life insurance policy is transferred to another party for valuable consideration (such as being sold to a business partner or a third party), a portion of the death benefit may lose its tax-exempt status and become subject to ordinary income tax.
The taxable amount is generally calculated as the death benefit minus the sum of the consideration paid for the transfer and any subsequent premiums paid by the transferee.
There are statutory exceptions to this rule, including transfers to:
- The insured person
- A partner of the insured
- A partnership in which the insured is a partner
- A corporation in which the insured is a shareholder or officer
- A transferee whose basis in the policy is determined by reference to the transferor’s basis
Employer-Provided Group Term Life Insurance
Many workers receive life insurance coverage as an employee benefit. While this provides vital financial security, the tax treatment of employer-sponsored group term life insurance differs significantly from individually owned policies.
Under IRC Section 79, an employee can exclude the cost of up to $50,000 of group term life insurance coverage provided under a policy carried directly or indirectly by an employer. This benefit is tax-free and does not need to be reported as taxable income.
Taxation of Coverage Exceeding $50,000
When an employer provides group term life insurance coverage that exceeds $50,000, the cost of the coverage over that threshold must be included in the employee’s gross income. This imputed income is calculated using the IRS Uniform Premiums table (often referred to as Table I rates), which varies by the employee’s age.
| Age Group | Cost per $1,000 of Protection per Month |
|---|---|
| Under 25 | $0.05 |
| 25 to 29 | $0.06 |
| 30 to 34 | $0.08 |
| 35 to 39 | $0.09 |
| 40 to 44 | $0.10 |
| 45 to 49 | $0.15 |
| 50 to 54 | $0.23 |
| 55 to 59 | $0.43 |
| 65 and older | $1.27 |
Employers calculate this amount and include it in the employee’s Form W-2 (typically in Box 12, using code C). This imputed income is subject to Social Security and Medicare (FICA) taxes, even though federal income tax withholding may or may not be applied depending on company payroll practices.
Cash Value Growth and Policy Withdrawals
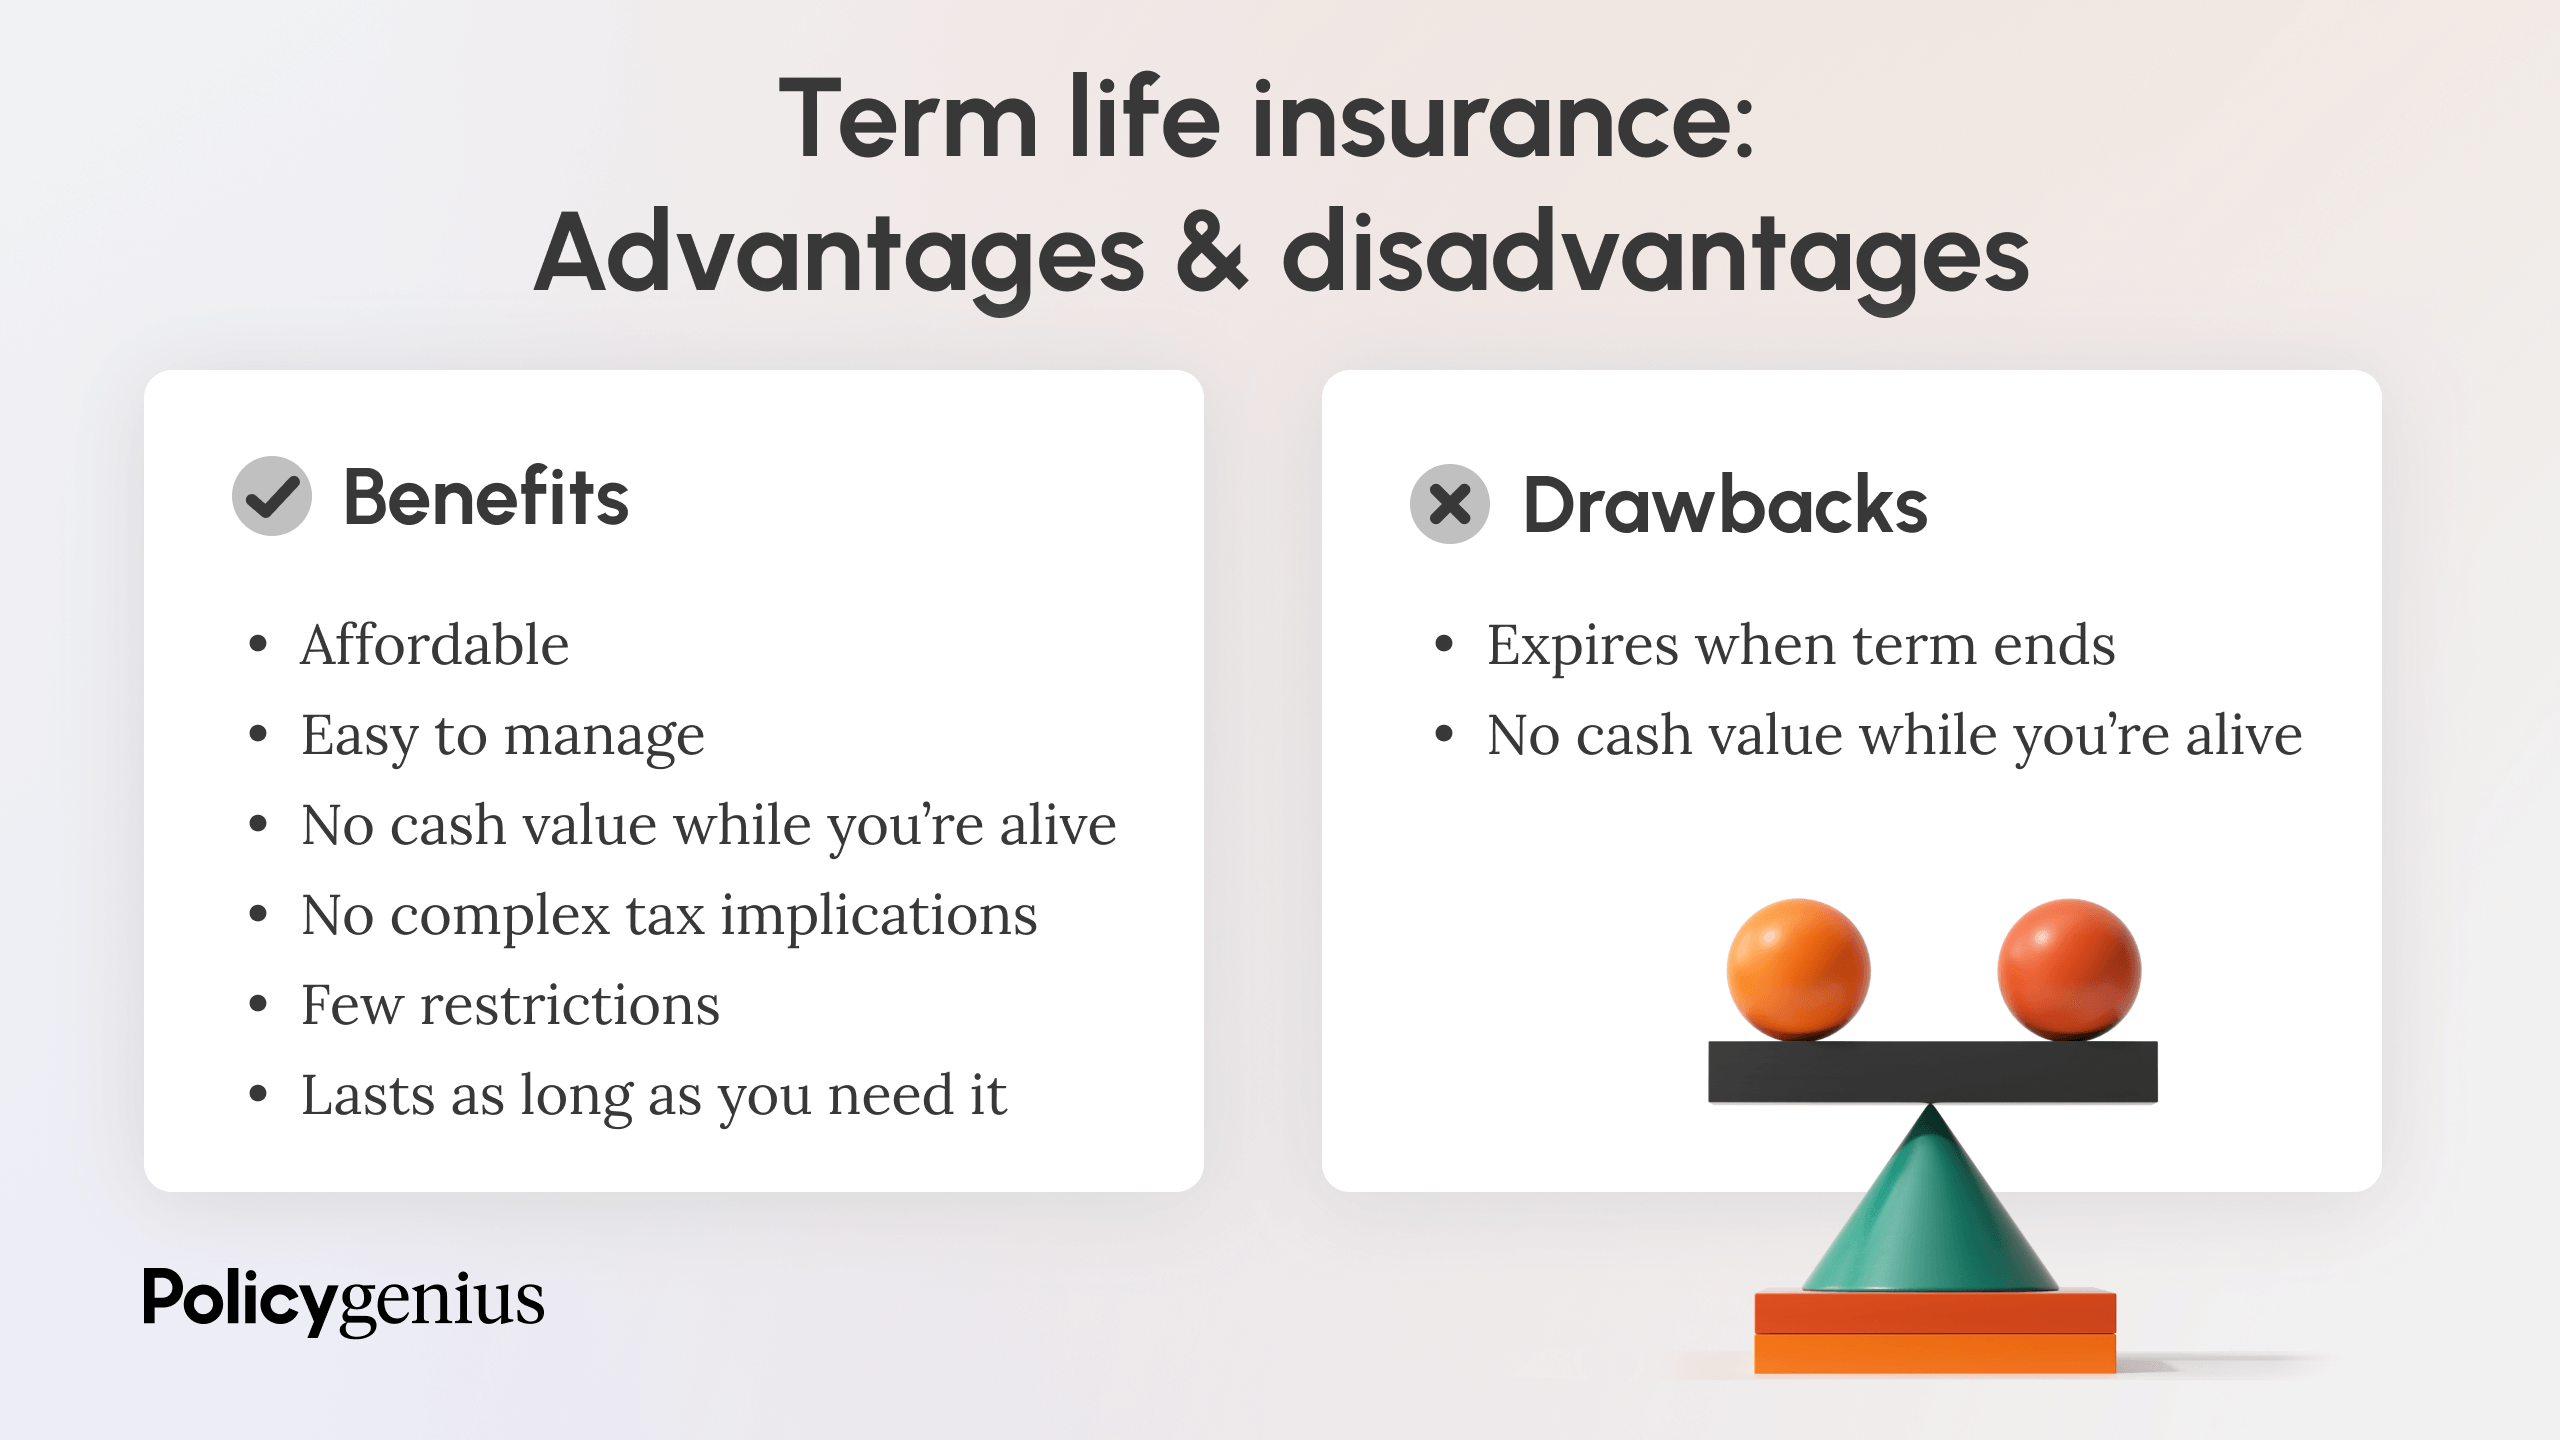
Permanent life insurance policies, such as whole life, universal life, and variable life, build cash value over time. The tax treatment of this internal buildup and any distributions taken during the insured’s lifetime is governed by strict statutory guidelines.
Tax-Deferred Growth
During the life of the policy, the cash value grows on a tax-deferred basis. As long as the earnings remain inside the policy and are not withdrawn, the policyholder does not report the growth as taxable income on their annual federal tax return. This allows the cash value to compound more rapidly than taxable investment accounts.
Cost Recovery Rule (FIFO)
When a policyholder withdraws funds from a permanent life insurance policy during their lifetime, the IRS applies the First-In, First-Out (FIFO) rule.
- Premiums Paid (Basis): Withdrawals are first treated as a return of the policy’s cost basis (the total premiums paid minus any prior non-taxable distributions). These withdrawals are entirely tax-free because the premiums were paid with after-tax dollars.
- Policy Earnings: Once the cumulative withdrawals exceed the total cost basis, any subsequent withdrawals are treated as earnings and are taxed as ordinary income.
Loans taken against the policy’s cash value are generally not treated as taxable distributions, provided the policy remains in force. However, if the policy lapses or is surrendered while a loan balance is outstanding, the outstanding loan amount is treated as a distribution and can trigger a significant tax liability if it exceeds the remaining cost basis.
Modified Endowment Contracts (MECs)
To prevent individuals from using life insurance primarily as a tax-sheltered investment vehicle rather than a death-benefit protection tool, Congress enacted the 7-pay test under IRC Section 7702A.
If the cumulative premiums paid into a life insurance policy during the first seven years exceed the net level premiums required to provide a paid-up policy, the contract is classified as a Modified Endowment Contract (MEC).
Tax Consequences of an MEC
Once a policy becomes an MEC, its favorable tax treatment for lifetime distributions is permanently lost. The tax rules shift from FIFO to Last-In, First-Out (LIFO):
- All withdrawals, policy loans, and pledges of cash value are treated first as taxable income (earnings) rather than a return of premium.
- Distributions taken before the policyholder reaches age 59½ are subject to a 10% IRS penalty tax on the taxable portion of the distribution, similar to penalties imposed on early withdrawals from traditional IRAs or 401(k) plans.
- Death benefits paid under an MEC remain income tax-free under Section 101(a).
Estate Tax and Ownership Considerations
While life insurance death benefits are generally exempt from income tax, they are not automatically exempt from federal estate tax. The inclusion of life insurance proceeds in a decedent's gross estate depends on who owned the policy at the time of death.
The Incidents of Ownership Test
Under IRC Section 2042, life insurance proceeds are included in the insured’s gross estate for federal estate tax purposes if:
- The proceeds are payable to the insured’s estate or executor.
- The insured possessed any incidents of ownership in the policy at the time of death.
Incidents of ownership include the power to change beneficiaries, surrender or cancel the policy, assign the policy, revoke an assignment, pledge the policy for a loan, or borrow against its cash value.
Using an Irrevocable Life Insurance Trust (ILIT)
To remove life insurance proceeds from a taxable estate, high-net-worth individuals often utilize an Irrevocable Life Insurance Trust (ILIT).
When properly established and funded, the ILIT purchases and owns the life insurance policy. Because the trust—not the insured individual—holds the incidents of ownership, the death benefit is paid directly to the trust for the benefit of the beneficiaries and is excluded from the insured’s gross estate upon death.
Frequently Asked Questions
Are life insurance death benefits subject to federal income tax?
No. Under IRC Section 101(a), death benefits paid out in a lump sum upon the death of the insured are generally received completely free of federal income tax by the named beneficiaries.
When does a life insurance payout become taxable?
A payout becomes subject to income tax if the beneficiary chooses to receive the death benefit in installments, as any interest earned on the principal after the insured's death is taxable. Additionally, policies subject to the transfer-for-value rule or employer group term policies exceeding $50,000 carry tax implications.
How does the IRS treat policy loans?
Policy loans are generally not considered taxable income while the policy remains active, because they are treated as debt secured by the cash value. However, if the policy lapses or is surrendered while a loan is outstanding, the unpaid loan amount is treated as a distribution and can trigger taxable income.
What is a Modified Endowment Contract (MEC)?
An MEC is a life insurance policy that has failed the IRS 7-pay test because too much money was funded into the contract too quickly. Withdrawals and loans from an MEC are taxed on a LIFO basis and may incur a 10% early withdrawal penalty if taken before age 59½.
Do I need to report life insurance on my annual tax return?
Standard life insurance death benefits and cash value growth do not need to be reported on your personal federal income tax return unless you received a Form 1099-INT for interest earned on installment payments or Form W-2 reflecting taxable group term life insurance coverage over $50,000.
Conclusion and Next Actions
Managing the tax implications of life insurance requires careful attention to policy design, ownership structure, and distribution methods. To ensure compliance with IRS regulations and optimize your financial strategy, review your current policies, verify beneficiary designations, and consult a qualified tax professional or estate planning attorney before making major adjustments, such as surrendering a policy, transferring ownership, or taking large cash-value withdrawals.
Image Gallery
Select an image to open it in a new tab.

Vivian Cho
Executive IT and Emerging Technologies Reporter
