
Securing car insurance after a Driving While Impaired (DWI) conviction is a critical, albeit challenging, step toward regaining driving privileges. You will likely face higher premiums and the requirement to file an SR-22 or FR-44 form with your state’s motor vehicle department. While the process involves significant financial and administrative hurdles, coverage remains attainable through specialized high-risk insurance providers.
Understanding the Immediate Impact of a DWI on Insurance
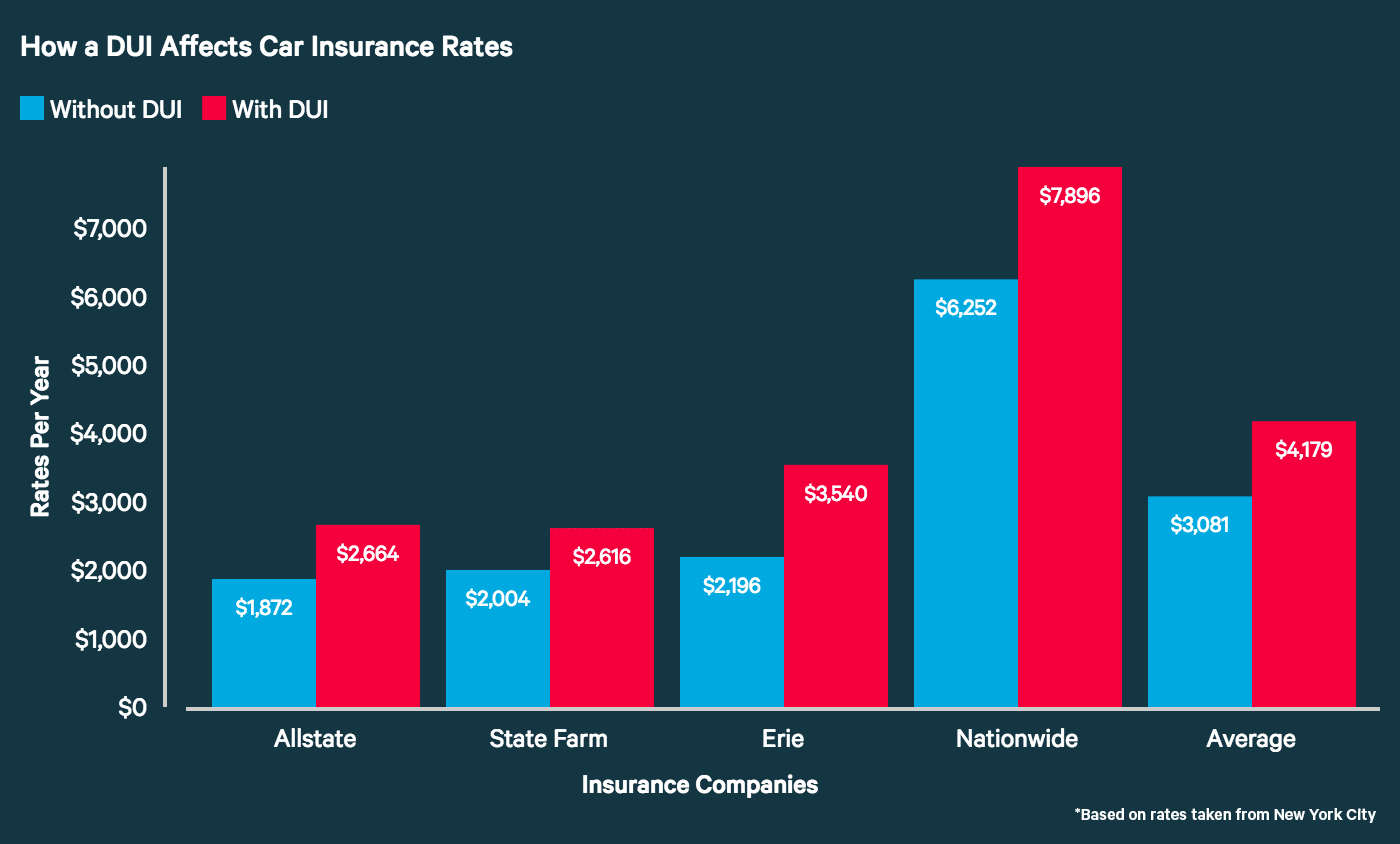
A DWI conviction is categorized by insurance carriers as a "major violation." Unlike a minor speeding ticket, which might only result in a modest premium increase or a "good driver" discount removal, a DWI signals a high risk of future liability to underwriters.
When your insurance carrier discovers a DWI conviction—which often happens at the time of policy renewal or through state motor vehicle report (MVR) monitoring—several things occur simultaneously. First, your policy may be non-renewed. In many states, insurance companies are legally permitted to drop high-risk drivers at the end of their current policy term. Second, if you are permitted to stay with your current carrier, you will likely see a substantial premium surge. Third, you become subject to state-mandated financial responsibility filings, such as the SR-22 or FR-44, which serve as proof to the government that you are carrying the state-required minimum liability insurance.
The Role of SR-22 and FR-44 Filings
An SR-22 is not an insurance policy itself; rather, it is a certificate of financial responsibility that your insurance company files with the state’s Department of Motor Vehicles (DMV) on your behalf. It essentially acts as a guarantee that you are maintaining the mandatory liability coverage required by your jurisdiction.
- SR-22: This is the most common form required for driving-related offenses, including DWIs, reckless driving, or driving without insurance.
- FR-44: Primarily utilized in states like Florida and Virginia, this form is more stringent. It requires you to carry liability limits significantly higher than the state’s minimum requirements, reflecting a higher degree of perceived risk.
Once you are required to have an SR-22 or FR-44, you cannot allow your policy to lapse. If you cancel your insurance or stop paying your premiums, the insurance company is legally obligated to notify the state, which will result in the immediate suspension of your driver’s license.
Financial Consequences: Why Premiums Rise
The increase in your insurance costs is driven by actuarial science. Insurance companies use historical data to calculate risk; drivers with a DWI conviction are statistically more likely to be involved in future accidents. Consequently, carriers compensate for this increased risk by charging higher premiums.
The "DWI surcharge" is not a standard fee across the industry. It varies wildly based on:
- State Regulations: Some states strictly regulate how much an insurer can increase rates for a specific conviction.
- Carrier Internal Policy: Some major, "preferred" insurance carriers will flatly refuse to insure drivers with a DWI record, while others specialize in "non-standard" or high-risk auto insurance.
- Driving History: A first-time offense is viewed differently than a repeat offense. If you have other points on your license, such as prior speeding tickets or at-fault accidents, your rates will increase exponentially.
Comparing Standard vs. Non-Standard Insurance
When searching for coverage, you must distinguish between standard and non-standard insurers. Standard insurers focus on low-risk drivers with clean records. If you approach a standard carrier after a DWI, they will often provide a quote that is prohibitively expensive, which is a common tactic to discourage high-risk applicants without explicitly denying them coverage.
Non-standard carriers specialize in insuring drivers with spotty records. They have specific underwriting guidelines for high-risk profiles and are more accustomed to processing SR-22 filings. While their base rates are higher than those of standard carriers, they are often the only viable option for someone navigating the post-DWI landscape.
| Feature | Standard Insurance | Non-Standard (High-Risk) Insurance |
|---|---|---|
| Risk Profile | Low (Clean driving history) | High (DWI, accidents, poor credit) |
| SR-22 Filing | Generally unavailable | Readily available |
| Premium Cost | Competitive/Market Average | Significantly higher than average |
| Underwriting | Strictly automated | Manual review common |
| Policy Flexibility | Standardized packages | Highly customizable to state mandates |
Steps to Secure Coverage After a Conviction
If you find yourself in need of insurance following a DWI, follow this systematic approach to minimize costs and ensure compliance:
1. Obtain a Copy of Your Driving Record Before speaking to any insurance agent, obtain an official copy of your MVR from your state’s DMV. Insurance companies will pull this report, and it is vital that you know exactly what they see. Ensure there are no clerical errors that could unfairly inflate your risk profile.
2. Contact Your Current Carrier (With Caution) Check your existing policy language. Some insurers will cancel a policy mid-term for a major violation, while others will wait until renewal. If they offer to keep you, ask for a written quote. Do not assume your current carrier will be the cheapest option, but keeping them may avoid a lapse in coverage.
3. Shop the Non-Standard Market Focus your search on companies that market themselves toward high-risk drivers. Use independent insurance agents—these professionals represent multiple companies and can shop your profile across several carriers, which saves you from calling dozens of agencies yourself.
4. Review Deductible Options If your premium is too high, consider raising your deductible (the amount you pay out-of-pocket before insurance kicks in). While this does not reduce the impact of the DWI surcharge, it can help lower the overall monthly premium to a more manageable level. However, ensure you have the cash saved for the higher deductible in case of an accident.
5. Confirm the SR-22 Filing When you decide on a carrier, explicitly confirm they are authorized to file the SR-22 in your specific state. Provide them with the exact case number and documentation provided by the court or the DMV to ensure the filing is processed correctly.
Common Pitfalls to Avoid
- Lying on Your Application: Never omit a DWI conviction when applying for insurance. If you lie, the insurance company will discover the truth when they run your MVR. They will then either cancel your policy for material misrepresentation or adjust your rates upward retroactively. Furthermore, you could face fraud allegations.
- Letting Your Policy Lapse: An insurance lapse is viewed by the state as being uninsured, which often triggers an automatic license suspension. If your policy is cancelled, secure a new one immediately.
- Ignoring State Minimums: When trying to save money, it is tempting to go for the lowest liability limits. However, given your status as a high-risk driver, you are more vulnerable to lawsuits if you are involved in an accident. Maintaining adequate liability coverage is a protective measure for your personal assets.
Frequently Asked Questions
How long does a DWI affect my car insurance rates? Generally, a DWI conviction will impact your insurance premiums for three to five years, depending on your state’s laws and the insurance company’s internal policies. Most carriers look at your MVR for the last three years to determine your current risk level.
Can I get insurance without an SR-22? If your state requires an SR-22 as a condition of restoring your license, you cannot obtain or maintain legal driving privileges without it. If you do not own a vehicle, you may be required to purchase a "non-owner" SR-22 policy, which provides the necessary financial responsibility filing without covering a specific car.
Does a DWI affect my credit score? A DWI conviction itself does not appear on your credit report. However, if you fail to pay court fines or insurance premiums related to the incident, those debts may be sent to collections, which will negatively impact your credit score and indirectly lead to higher insurance premiums, as many carriers use credit-based insurance scores.
Will my insurance drop me if I get a DWI? It depends on the company. Many insurance providers have specific bylaws regarding "material changes" in risk. A DWI is a major material change. Some carriers will cancel your policy at the next renewal date, while others will simply increase your premium.
Is there any way to lower my rates after a DWI? Beyond shopping around, the best ways to lower your rates are to maintain a clean driving record moving forward, complete a state-approved defensive driving course, and potentially bundle your insurance policies if you have renters or homeowners insurance.
Next Steps and Recommendations
Securing insurance after a DWI is an exercise in damage control. Start by obtaining your MVR to ensure accuracy, then immediately engage an independent agent to find a non-standard carrier that can handle your state’s SR-22 or FR-44 requirements. Prioritize stability—avoid any lapses in coverage, as these will reset your progress toward lower rates. By maintaining a clean driving record for three to five years, you will eventually transition back to standard insurance rates.
Disclaimer: Insurance laws and regulations vary by jurisdiction. This article provides general information and should not be considered legal or financial advice. Consult with a licensed insurance agent or a legal professional regarding your specific situation.

Image Gallery
Select an image to open it in a new tab.



Ingrid Bjornson
Global Cyber Policy and Regulation Analyst
