
The cash value component of an Indexed Universal Life (IUL) insurance policy serves as the financial engine of the product, providing a vehicle for potential accumulation linked to market indices while offering permanent life insurance protection. This cash value matters because it functions as a flexible asset that can be accessed through loans or withdrawals to supplement retirement income, cover emergency expenses, or manage tax liabilities, provided the policy remains properly funded and maintained.
The Mechanics of IUL Cash Value
Indexed Universal Life insurance is a type of permanent life insurance. Unlike term life insurance, which only provides a death benefit for a specific period, IUL policies are designed to remain in force throughout the insured's life, provided that sufficient premiums are paid. The "cash value" is the portion of your premium payments that is not used to cover the cost of insurance or administrative fees. This remainder is placed into a cash value account.
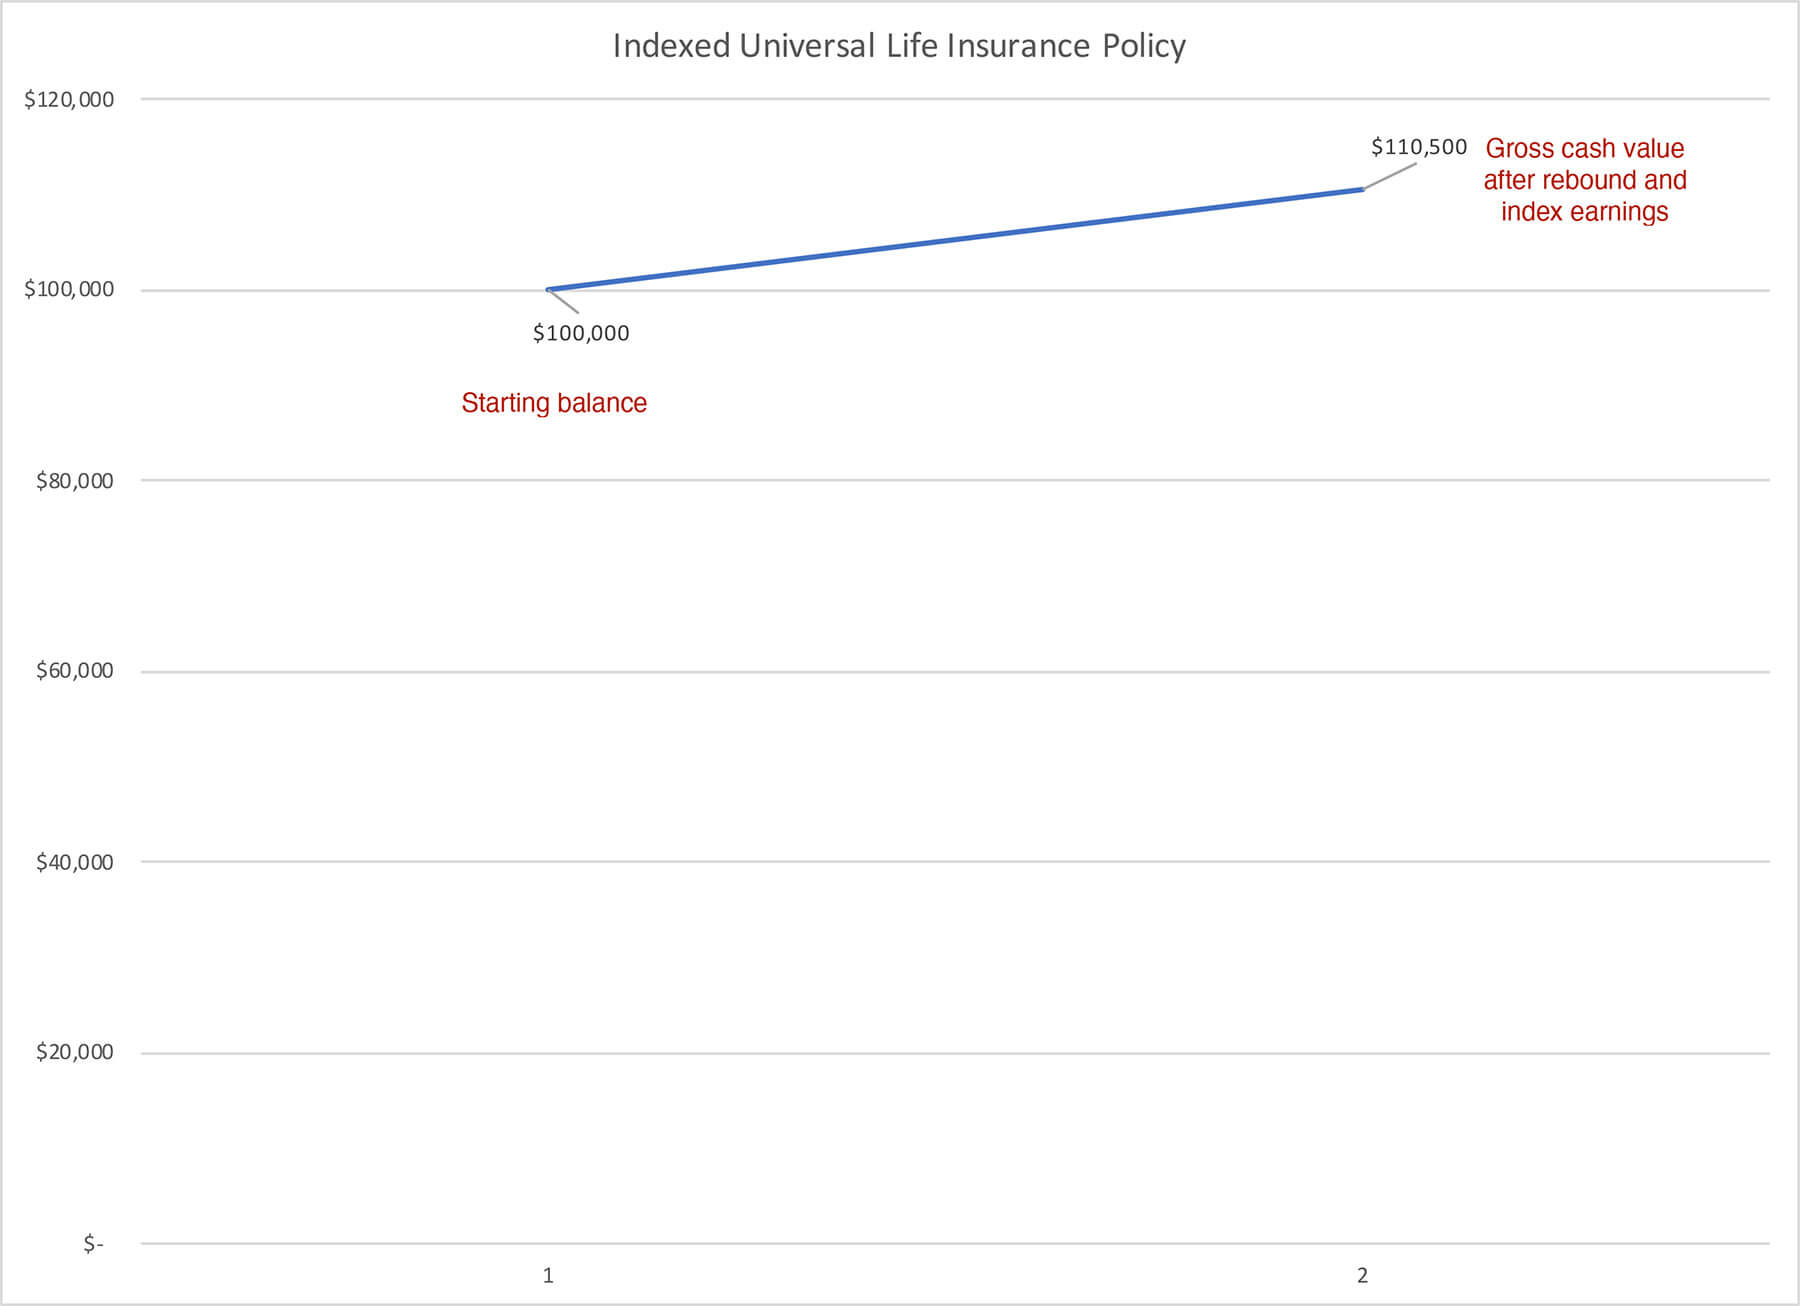
In an IUL, this account is not invested directly in the stock market. Instead, the insurer credits interest to the account based on the performance of a selected market index, such as the S&P 500. This is the defining feature of the product: you gain exposure to market-linked growth without being directly invested in equities. This mechanism typically includes a "cap"—a maximum interest rate you can earn—and a "floor," which protects your account from negative returns during market downturns.
Why the Cash Value Accumulation Matters
The importance of the cash value in an IUL policy extends beyond simple death benefit coverage. It acts as an integrated financial tool for long-term planning.
1. Tax-Advantaged Growth
One of the primary reasons cash value matters is the tax treatment associated with it. Under current tax regulations, the interest credited to your IUL cash value grows on a tax-deferred basis. You do not pay income tax on the gains as they accumulate. Furthermore, if the policy is structured correctly and remains in force, you can often access these funds via policy loans that are generally received income-tax-free, providing a potential source of tax-efficient supplemental capital.
2. Supplemental Retirement Income
As the cash value accumulates over several decades, it can serve as a secondary bucket for retirement liquidity. Many policyholders utilize the cash value to provide a supplemental income stream during retirement. By taking loans against the cash value, you can access funds without the typical penalties associated with early withdrawals from qualified retirement accounts like a 401(k) or IRA.
3. Financial Flexibility and Liquidity
Life is unpredictable. Should an emergency arise, the cash value of an IUL policy can function as a source of liquidity. Policyholders can typically borrow against their cash value for any purpose—be it medical expenses, education costs, or business opportunities. Because the policy is the collateral for the loan, these transactions are usually processed without the credit checks or lengthy approval processes associated with traditional bank loans.
Managing the Cash Value: Risks and Considerations
While the growth potential is a primary draw, the cash value in an IUL is subject to specific constraints that owners must monitor to ensure the policy remains active.
The Cost of Insurance (COI)
The "cost of insurance" is a fee deducted from your cash value to pay for the death benefit. As you age, the cost of insurance increases. If the cash value growth does not keep pace with the rising COI—due to poor index performance, underfunding the policy, or taking excessive loans—the policy may lapse. A lapsed policy can trigger significant tax consequences and result in the loss of both the death benefit and the accumulated cash value.
Index Caps and Participation Rates
The growth of your cash value is not unlimited. Insurers apply a "participation rate" (the percentage of the index gain you are credited) and a "cap rate" (the absolute maximum interest you can earn in a period). If the market experiences a significant bull run, your gains will be limited by these caps. Conversely, during market crashes, the floor protects you from losing money, but you will still be charged the COI and other policy fees.
Comparative Table: Permanent Life Insurance Features
| Feature | Indexed Universal Life (IUL) | Whole Life Insurance | Universal Life (Fixed) |
|---|---|---|---|
| Cash Value Growth | Index-linked (with caps/floors) | Guaranteed fixed interest | Fixed interest rate |
| Premium Flexibility | High | Low (Fixed) | Moderate |
| Risk Profile | Moderate (Market-linked) | Low (Guaranteed) | Low (Interest rate risk) |
| Primary Goal | Growth potential & Protection | Long-term stability | Flexibility |
Monitoring Your Policy Performance
Because IUL policies are not "set-it-and-forget-it" products, regular monitoring is essential. Every year, your insurer will provide an annual statement. It is critical to review:
- The Crediting Rate: Did the index perform well, and did the insurer credit interest as expected?
- The Surrender Value: This is the actual amount you would receive if you terminated the policy today, which may be lower than the total cash value due to surrender charges.
- The Projected Lapse Date: Most annual reports will calculate how long the policy is expected to last based on current funding levels. If this date is approaching, you must adjust your premium payments immediately.
Common Pitfalls to Avoid
Many policyholders run into issues by misunderstanding the nature of IUL cash value.
- Underfunding the Policy: If you pay only the minimum required premium, you may not build enough cash value to cover the rising cost of insurance in your later years.
- Over-leveraging: Taking out large loans early in the life of the policy can stifle compounding. If you borrow too much, too soon, the remaining cash value may not be enough to sustain the policy.
- Ignoring Fees: Management fees, premium loads, and administrative expenses are deducted from your cash value. It is vital to understand the internal cost structure before purchasing the policy.
Frequently Asked Questions
Can I lose my cash value if the market crashes?
No. An IUL policy includes a floor, typically at 0%. If the market index performs negatively, your cash value is protected from loss due to that market performance. However, you will still be charged the cost of insurance and administrative fees, which will reduce your cash value over time regardless of market performance.
Is the cash value the same as the death benefit?
No. The death benefit is the amount paid to your beneficiaries upon your passing. The cash value is an account you can access during your lifetime. In many policies, the cash value eventually becomes a portion of the total death benefit, but they are separate financial concepts.
Are there taxes on the cash value?
Growth within the policy is tax-deferred. When you take a loan against your cash value, it is generally tax-free. However, if you surrender the policy for more than the "basis" (the total premiums you have paid), the gain may be subject to income tax. Always consult with a tax professional regarding your specific financial situation.
Can I use the cash value for any purpose?
Yes. Unlike a 529 plan for education or an HSA for medical expenses, the cash value in an IUL can be used for any purpose you choose. There are no restrictions on how you spend the proceeds of a policy loan.
Final Recommendation
The cash value in an Indexed Universal Life insurance policy is a powerful tool for those who prioritize flexibility and potential growth alongside permanent death benefit coverage. However, its effectiveness depends entirely on proactive management. You should review your annual policy statement with your financial advisor to ensure that your premium payments are aligned with your goals. If you are not prepared to monitor the policy's performance or if you prioritize guaranteed, low-maintenance returns, you may find that other financial instruments better suit your needs. Before proceeding, request a "life insurance illustration" from your provider that shows various market scenarios, as this will provide a clearer picture of how your cash value might behave under different economic conditions.
Image Gallery
Select an image to open it in a new tab.

Celine Dubois
Contemporary Living and Global Arts Columnist
