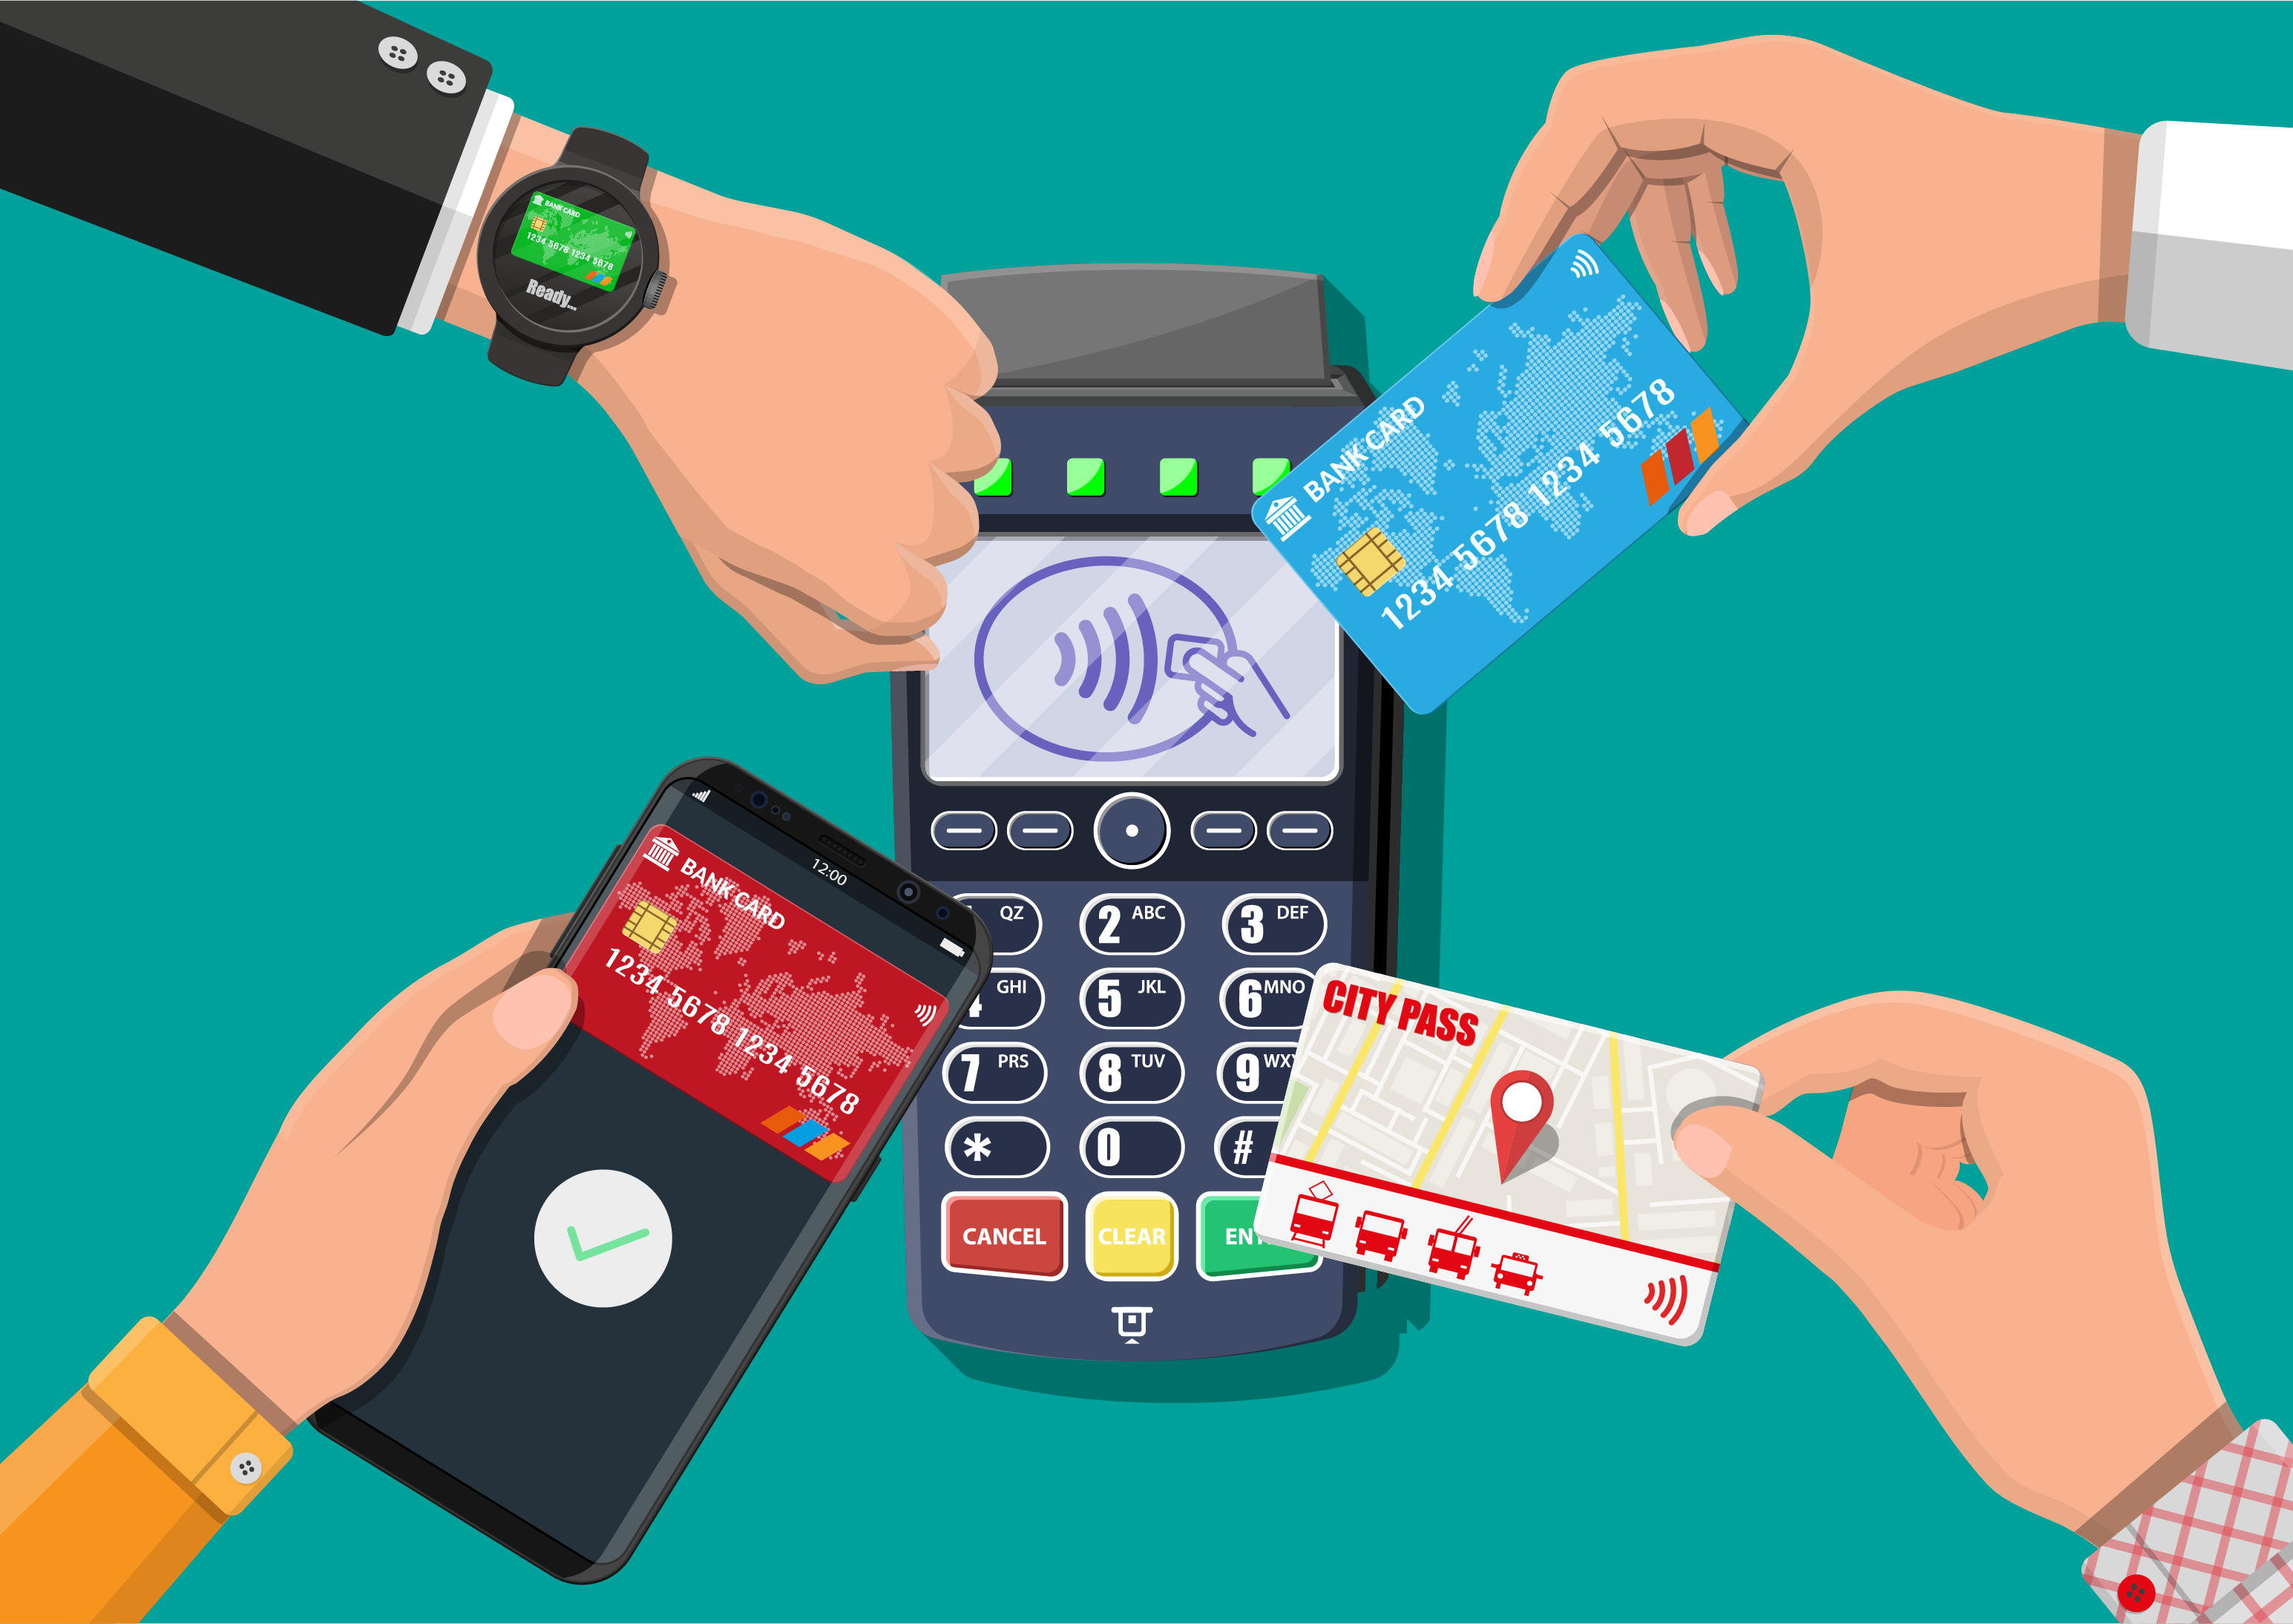
Pay by phone is a versatile payment method that allows consumers to charge purchases directly to their mobile service provider's bill or use a mobile application to facilitate transactions. This system is primarily used for parking, digital subscriptions, and small-scale online purchases, offering a secure, card-free alternative to traditional banking.
Understanding the "Pay by Phone" Ecosystem
The phrase "pay by phone" often describes two distinct but related financial technologies. To fully understand how this ecosystem functions in 2026, it is essential to distinguish between the billing method and the application-based service.
The first interpretation refers to Direct Carrier Billing (DCB). This is a pure fintech solution where your mobile network operator (MNO) acts as the intermediary for the payment. Instead of entering a 16-digit credit card number, you authorize a charge that appears on your next monthly phone statement or is deducted from your prepaid balance.
The second interpretation refers to proprietary payment applications, most notably the "PayByPhone" parking service. This global platform allows users to pay for vehicle parking via a mobile app, SMS, or a phone call, linking a credit card or digital wallet to a specific vehicle registration and parking zone.
As we move further into 2026, these two streams have begun to merge, with many parking and transit apps now offering carrier billing as an alternative to credit card storage. This convergence prioritizes user privacy and reduces the "friction" of digital checkouts.
How Direct Carrier Billing (DCB) Works
Direct Carrier Billing is a technical integration between a merchant’s checkout system and a mobile carrier’s billing platform. In 2026, this technology has matured to support high-speed, 5G-enabled micro-transactions with significant security protocols.
The Transaction Flow
When you select "Pay by Phone" or "Mobile Billing" at an online checkout, the following technical sequence occurs:
- Identification: The merchant’s platform detects your mobile network through your SIM card or requires you to enter your phone number.
- Authentication: A "Header Enrichment" process or a One-Time Password (OTP) sent via SMS verifies that you are the owner of the device.
- Authorization: The request is sent to your carrier (e.g., AT&T, Verizon, Vodafone, or O2). The carrier checks your account status—ensuring you have sufficient credit or a standing contract in good stead.
- Confirmation: Once the carrier approves the transaction, the merchant provides the digital good or service.
- Settlement: The carrier pays the merchant (minus a commission), and the amount is added to your mobile bill.
Technical Prerequisites for DCB
To use carrier billing in 2026, certain conditions must be met. Not every mobile user is eligible for this service.
- Active SIM and Network Connection: You must have a valid, active SIM card. While some services work over Wi-Fi via SMS verification, the most seamless experiences occur over cellular data.
- Account Standing: Carriers typically block billing services for accounts with a history of late payments or those currently in a "soft-disconnected" state.
- Spending Limits: Most jurisdictions and carriers impose daily and monthly limits on DCB to prevent fraud and overspending. In many regions, a single transaction is capped at $50 or €50.
- Plan Compatibility: Some corporate or business mobile plans restrict third-party billing to prevent employees from charging personal expenses to a company account.

Pay by Phone for Parking: A Global Standard
One of the most frequent uses of "pay by phone" is in the context of urban mobility and parking management. Services like the PayByPhone app have largely replaced physical coin meters and even some "pay and display" kiosks.
How Parking Apps Function
These services operate on a cloud-based platform that connects local municipalities and private parking lot operators with drivers. When you "pay by phone" for parking, you are not necessarily using your phone bill; you are using your phone as the interface to manage your parking session.
- Zone Identification: Each parking area is assigned a unique 4-to-6-digit code.
- Session Initiation: You enter the zone number and your desired duration into the app.
- Dynamic Updates: One of the primary advantages of this system is the ability to extend your parking duration remotely. If your meeting runs long, you can add time through your phone without returning to your vehicle.
- Enforcement: Traffic wardens use handheld devices to scan license plates. Their system queries the PayByPhone database in real-time to see if a specific plate has an active, paid session.
Integration with Modern Vehicles
By 2026, pay-by-phone parking has been integrated directly into vehicle infotainment systems. Through platforms like Apple CarPlay and Android Auto, the "pay by phone" experience is triggered automatically when the vehicle's GPS detects it has stopped in a recognized parking zone, prompting the driver to start a session with a single tap on the dashboard screen.
Benefits of Using Pay by Phone Methods
The adoption of pay-by-phone technology has accelerated because it addresses several pain points inherent in traditional payment systems.
Enhanced Security and Privacy
When you use carrier billing, you do not share your bank account or credit card details with the merchant. The only information exchanged is your mobile number. This drastically reduces the "attack surface" for hackers. If a merchant's database is breached, your financial credentials remain safe because the merchant never had them in the first place.
Speed and Convenience
Entering card details on a mobile device is cumbersome and prone to error. Pay by phone simplifies this to a one-tap or two-step verification process. This is particularly useful for "on-the-go" purchases like public transport tickets or digital media.
Financial Inclusion
For individuals who do not have a traditional bank account or credit card—often referred to as the "underbanked"—pay by phone offers a way to participate in the digital economy. As long as they have a mobile phone with a prepaid balance, they can purchase apps, music, and services.
Comparison of Payment Methods (2026 Data)
The following table compares pay-by-phone (carrier billing) against other common digital payment methods.
| Feature | Pay by Phone (Carrier Billing) | Mobile Wallets (Apple/Google Pay) | Traditional Credit/Debit Cards |
|---|---|---|---|
| Setup Required | None (Pre-linked to SIM) | Medium (Card must be added) | Low |
| Transaction Limit | Low ($50 - $100 typical) | High (Varies by card) | High |
| Privacy Level | High (No card info shared) | Medium (Tokenized info) | Low (Full info shared) |
| Device Required | Any Mobile Phone | Smartphone with NFC | Physical Card/Device |
| Primary Use Case | Small Digital Goods, Parking | Retail, Groceries, Travel | Large Purchases, General Use |
| Interest Rates | N/A (Part of phone bill) | Varies by Card Issuer | High (if not paid in full) |
Limitations and Potential Drawbacks
While convenient, pay-by-phone systems are not without their downsides. Users must be aware of these limitations to manage their finances effectively.
Lower Transaction Caps
Due to anti-money laundering (AML) regulations and carrier risk management, you cannot use pay by phone for significant purchases. You won't be able to buy a new laptop or pay for a hotel stay using your phone bill. It remains a solution for micro-transactions.
Potential for "Bill Shock"
Because pay-by-phone transactions are so easy to complete, it is possible to lose track of spending. Small $2 and $5 purchases can accumulate, leading to a much higher mobile bill at the end of the month than anticipated. Parents should be particularly cautious with children who have access to devices linked to carrier billing.
Lack of Consumer Protections
Traditional credit cards offer robust "chargeback" protections under laws like the Fair Credit Billing Act (in the US). If a merchant fails to deliver a product, you can dispute the charge with your bank. While carriers have dispute processes, they are often less comprehensive than those offered by major credit card issuers.
Security Measures in 2026
As of 2026, the security landscape for mobile payments has evolved to combat sophisticated phishing and SIM-swapping attacks.
- Biometric Step-up: Even for small carrier-billed transactions, many phones now require a FaceID or fingerprint scan to confirm the intent to pay.
- SIM-Swap Protection: Carriers have implemented stricter "cooling-off" periods. If a SIM card is recently replaced, pay-by-phone services are often suspended for 24-72 hours to prevent fraudulent use by someone who has hijacked a phone number.
- Real-Time Alerts: Most users now receive an immediate SMS or push notification for every charge made to their phone bill, allowing for the instant detection of unauthorized activity.
Troubleshooting Common Issues
Sometimes, a "pay by phone" attempt will fail. Understanding the common causes can help you resolve the issue quickly.
- Carrier Block: Many carriers allow users to opt-out of third-party billing. If your payment is declined, check your mobile account settings to ensure "Premium SMS" or "Third-Party Charges" are enabled.
- Insufficient Prepaid Balance: If you are on a "pay-as-you-go" plan, you must have enough credit to cover both the purchase price and any applicable service fees.
- Network Latency: Carrier billing requires a stable connection to the MNO's gateway. If you are in an area with poor reception, the authentication "handshake" may time out.
- Spending Limit Reached: If you have already made several small purchases during the billing cycle, you may have hit the carrier's internal fraud threshold.
Frequently Asked Questions
Is pay by phone the same as Apple Pay or Google Pay?
Not exactly. While both use a phone to pay, Apple Pay and Google Pay are "Mobile Wallets" that store your existing credit/debit cards and use NFC (Near Field Communication) at checkout. "Pay by phone" in the traditional sense usually refers to charging a purchase directly to your mobile phone bill (Carrier Billing) or using a specific app like PayByPhone for parking.
Can I get a refund for a pay-by-phone transaction?
Yes, but the process usually starts with the merchant, not the phone company. You must contact the digital service provider or the parking authority first. If they agree to a refund, they will notify the carrier to credit your mobile account. It can take one to two billing cycles for the refund to appear on your statement.
Are there extra fees for using my phone bill to pay?
For digital goods (like apps or games), the price is usually the same as using a credit card. However, for parking and certain "convenience" services, a small service fee (e.g., $0.25 to $0.50) is often added to the transaction to cover the cost of the mobile technology and the SMS reminders.
Does pay by phone work internationally?
Carrier billing is often restricted to your home country. If you are roaming, you may not be able to charge purchases to your bill due to the complexities of cross-border financial settlements between different mobile networks. However, app-based parking services usually work internationally if you link a standard credit card to the app.
How do I stop someone from using my phone to make purchases?
You can contact your mobile carrier and ask them to place a "billing block" on your account. This will prevent any third-party charges from being added to your bill. Additionally, ensuring your phone has a strong passcode and biometric lock prevents unauthorized physical use of the device for payments.
Final Recommendations
If you are looking for a way to streamline small, frequent payments—especially for parking or digital content—pay by phone is one of the most efficient methods available in 2026. It offers a high level of privacy by shielding your banking details from merchants and provides a convenient fallback when you don't have your physical wallet.
To get started, check your mobile carrier’s app to see if you have a "billing" or "third-party purchase" section. This will show you your current spending limits and allow you to track any charges in real-time. For parking, downloading the official app for your city and pre-loading your vehicle details will save you significant time and the hassle of dealing with outdated physical meters.
Image Gallery
Select an image to open it in a new tab.



Lars Thomsen
Global Labor Markets and Economic Strategy Editor
