To understand auto insurance quotes in New Brunswick in 2026, you must evaluate the province’s mandatory coverage requirements—Liability, Accident Benefits, Uninsured Automobile, and Direct Compensation Property Damage (DCPD)—against your specific risk profile. Quotes reflect a combination of government-regulated rate caps and private competition, influenced by your driving record, vehicle type, and location.
In New Brunswick’s private insurance market, obtaining a quote is more than just looking at a final monthly premium. It involves a complex calculation of risk, statutory obligations, and elective protections. As of 2026, the industry has seen shifts in how technology and inflation impact vehicle repair costs, making it essential for New Brunswick drivers to look beneath the surface of a quote to ensure they are adequately protected while remaining compliant with provincial law.
The New Brunswick Insurance Landscape: A Private but Regulated Market
Unlike provinces with crown-corporation insurance (such as British Columbia or Manitoba), New Brunswick operates on a private market system. This means drivers purchase policies from private insurance companies or through brokers and agents. However, this private market is strictly overseen by the Financial and Consumer Services Commission (FCNB) and the New Brunswick Insurance Board (NBIB).
The NBIB is responsible for regulating the rates that insurance companies can charge. Each year, insurers must file their proposed rates with the Board, providing evidence to justify any increases. This regulatory oversight ensures that while the market is competitive, rates remain relatively stable and are not subject to arbitrary spikes. When you receive a quote in 2026, that figure is the result of a proprietary algorithm that has been vetted and approved by provincial regulators to ensure fairness and solvency.
Understanding this structure is vital because it explains why quotes can vary significantly between providers. One company might prioritize insuring long-haul commuters in the Moncton area, while another might offer better rates for retirees in the Acadian Peninsula. The "best" quote is often found by matching your specific demographic profile with an insurer whose current portfolio favors your risk level.
Mandatory Coverage: The Foundation of Every Quote
In New Brunswick, every auto insurance quote must include four primary components. You cannot legally operate a motor vehicle on public roads without these. If a quote seems unusually low, the first step is to verify that these mandatory limits meet or exceed the provincial minimums.
1. Third-Party Liability
This is the most critical part of your policy. It protects you if you are found legally responsible for an accident that causes injury or death to another person or damage to their property. In 2026, the legal minimum requirement in New Brunswick remains $200,000, though insurance professionals almost universally recommend a minimum of $1,000,000 or $2,000,000. In a litigious environment, a $200,000 limit can be exhausted quickly by a single serious injury claim.
2. Section B: Accident Benefits
New Brunswick follows a "no-fault" approach for medical and rehabilitation benefits. This means that regardless of who caused the accident, your own insurance company pays for your medical expenses, loss of income, and funeral expenses. Your quote will include these benefits, which cover professional services like physiotherapy, chiropractic care, and psychological counseling necessary for recovery.
3. Uninsured Automobile Coverage
This component protects you and your passengers if you are involved in an accident with a driver who does not have insurance or a driver who flees the scene (hit-and-run). It ensures that you still have access to funds for injury claims even when the at-fault party is untraceable or uninsured.
4. Direct Compensation Property Damage (DCPD)
DCPD is a system where you deal with your own insurance company for damage to your vehicle when you are not at fault. This streamlines the claims process, as you do not have to wait for a third-party insurer to approve repairs. For DCPD to apply, the accident must happen in New Brunswick (or another province with similar DCPD laws), and at least one other involved vehicle must be identified and insured.

Optional Coverages That Impact Your Premium
While the mandatory components provide a safety net, most New Brunswick drivers opt for additional coverage to protect their own investment in their vehicle. These "physical damage" coverages are where quotes often differ the most.
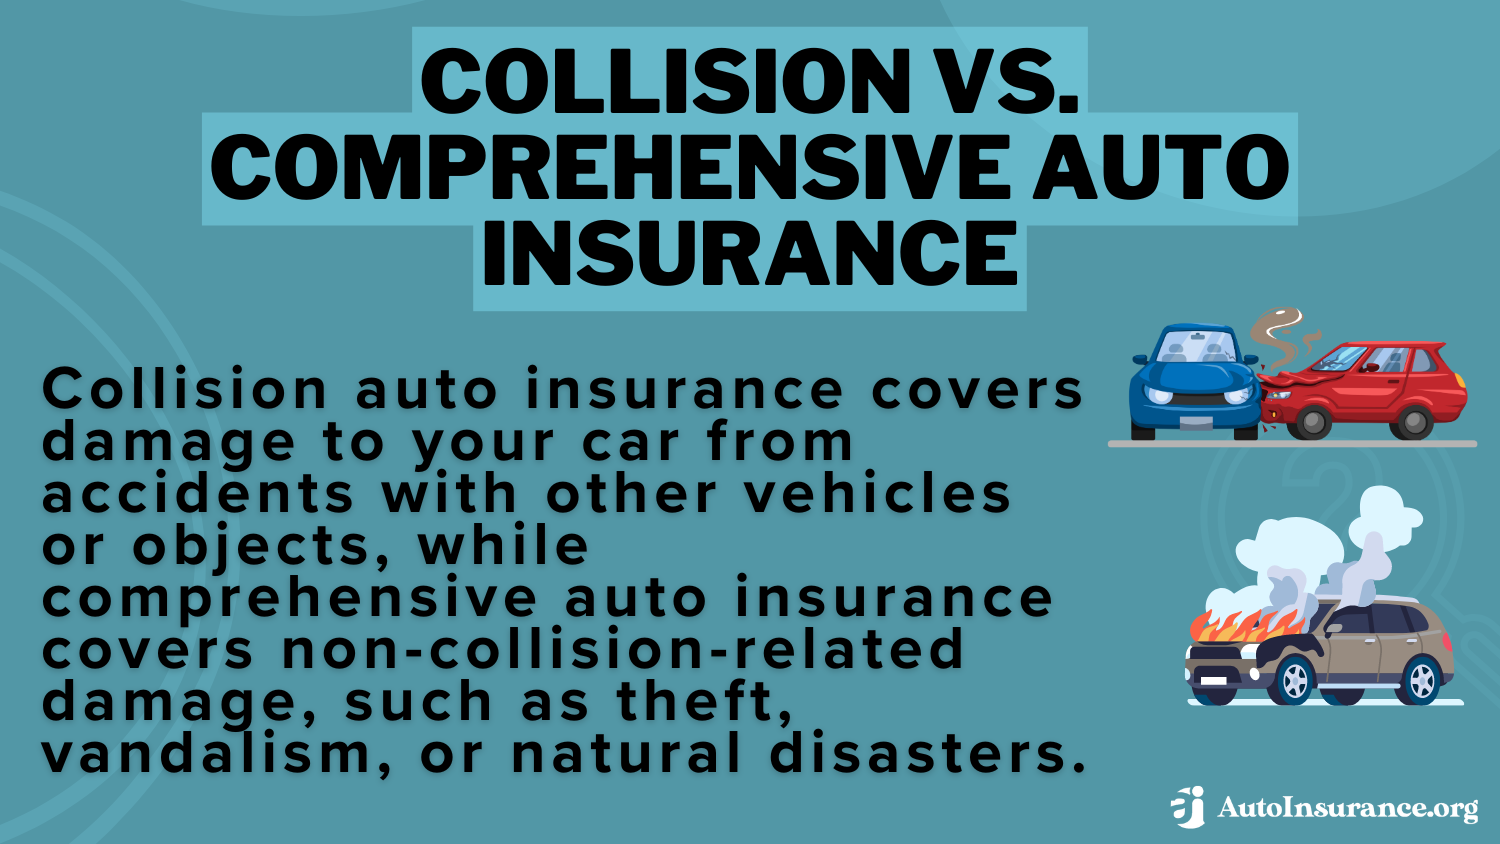
- Collision Coverage: This pays for damage to your vehicle caused by a collision with another object or another vehicle, regardless of fault. If you have a car loan or lease, your lienholder will almost certainly require this.
- Comprehensive Coverage: This covers "all other" perils, such as fire, theft, vandalism, and falling objects. In New Brunswick, this is particularly relevant for wildlife collisions (moose and deer) and storm-related damage, which have become more frequent and costly as of 2026.
- Specified Perils: A narrower version of comprehensive coverage that only covers specific risks named in the policy.
- All Perils: A combination of Collision and Comprehensive, often providing the most robust level of protection.
The Role of Deductibles
Your deductible—the amount you pay out of pocket before insurance kicks in—is a major lever in your quote. A higher deductible (e.g., $1,000 instead of $500) reduces the insurer's risk and therefore lowers your premium. When comparing quotes, ensure the deductibles are identical across all options to get an "apples-to-apples" comparison.
Factors Influencing Your 2026 Quote
Insurance companies use hundreds of data points to generate a quote. In New Brunswick, several specific factors carry the most weight:
| Factor | Impact on Quote | Why it Matters in New Brunswick |
|---|---|---|
| Driving Record | High | Tickets and at-fault accidents stay on your record for several years and are the biggest predictors of future risk. |
| Location (Postal Code) | Moderate | Urban areas like Saint John or Fredericton often have higher rates due to traffic density, whereas rural areas may have lower rates but higher wildlife collision risks. |
| Vehicle Make/Model | High | Modern vehicles (2024–2026 models) with advanced driver assistance systems (ADAS) are safer but significantly more expensive to repair. |
| Annual Mileage | Moderate | The more you drive, the higher the statistical probability of an incident. |
| Experience Level | High | New drivers are statistically riskier. New Brunswick uses a "grid" or similar rating system to ensure fair pricing for new residents and young drivers. |
The "Minor Injury Cap" and Its Effect on Premiums
One of the unique aspects of New Brunswick's auto insurance system is the Minor Injury Cap. This is a limit on the amount of "pain and suffering" (non-pecuniary) damages a person can claim for injuries classified as minor, such as sprains, strains, or certain whiplash-associated disorders.
For 2026, this cap is adjusted annually for inflation. When you look at your quote, the existence of this cap helps keep premiums lower than they would be in a full-tort province. It is important to understand that this cap only applies to pain and suffering for minor injuries; it does not limit your ability to claim for lost wages or actual medical expenses.
Understanding Endorsements (SEF Forms)
Standard endorsements, known as Standard Endorsement Forms (SEF), are additions to your policy that modify your coverage. You will see these listed on your quote, and they can change the price significantly.
- SEF 44 (Family Protection Coverage): This is perhaps the most important endorsement in New Brunswick. If you are injured by an underinsured driver, SEF 44 covers the difference between the at-fault driver's liability limit and your own. Given that some drivers only carry the $200,000 minimum, this protects your family if a claim exceeds that amount.
- SEF 20 (Loss of Use): This pays for a rental car or transportation costs while your vehicle is being repaired after a covered claim.
- SEF 27 (Legal Liability for Damage to Non-Owned Automobiles): This extends your physical damage coverage to rental cars, often eliminating the need to buy expensive insurance at the rental counter.
- SEF 43R (Waiver of Depreciation): For owners of new vehicles, this ensures that if the car is totaled within the first 24–36 months, the insurer pays the original purchase price rather than the depreciated market value.
How to Compare Auto Insurance Quotes Effectively
When you have three or four quotes on your desk (or screen), do not simply look at the bottom line. Follow this systematic approach to ensure you are getting the best value:
- Verify Liability Limits: Ensure every quote uses the same limit (e.g., $1,000,000). A quote with only $200,000 will be cheaper but leaves you dangerously exposed.
- Check the Deductibles: If Quote A has a $250 deductible and Quote B has a $1,000 deductible, Quote B will look better but costs you more during a claim.
- Confirm Endorsements: Does the quote include SEF 44? What about roadside assistance or accident forgiveness?
- Review the Rating Information: Check the "Driver Rating" section. If the insurer has incorrectly listed you as having an accident from 2021 that wasn't your fault, your quote will be artificially high.
- Look for Discounts: New Brunswick insurers offer various discounts. Common ones in 2026 include multi-vehicle discounts, winter tire discounts (essential for NB winters), and "telematics" discounts for those willing to use a driving-tracker app.
Common Pitfalls and Misunderstandings
A common mistake when interpreting New Brunswick quotes is failing to disclose "material changes in risk." If you use your vehicle for food delivery or ride-sharing and do not disclose this during the quoting process, the quote is effectively useless. In the event of an accident, the insurer can void the policy for misrepresentation.
Another misunderstanding involves the "Facility Association." If you have a poor driving record and are denied coverage by standard insurers, you will be quoted through the Facility Association. This is a "pool" of last resort. These quotes are significantly higher and are designed to encourage drivers to improve their records to return to the standard market.
Expert Strategies for Lowering Your Quote
By 2026, the cost of living has made insurance premiums a significant household expense. To lower your quote without sacrificing essential protection, consider the following:
- Bundle Policies: Combining your home or tenant insurance with your auto insurance is the most effective way to secure a 10% to 15% discount.
- Increase Deductibles: If you have an emergency fund, taking a higher deductible can save you hundreds of dollars over a few years.
- Maintain a Continuous Insurance History: Gaps in insurance coverage can lead to higher quotes. If you are selling a car and waiting to buy another, talk to your broker about a "non-owner" policy to maintain your history.
- Drive Less: If you have shifted to a permanent remote work model since the mid-2020s, ensure your quote reflects "Pleasure" use rather than "Commute" use.
Frequently Asked Questions
Is the $200,000 liability limit enough in New Brunswick for 2026?
Technically, it is the legal minimum, but it is rarely enough. In 2026, with the rising costs of medical care and high-value vehicles, a multi-vehicle accident can easily result in claims exceeding $500,000. Most experts recommend at least $1,000,000 to protect your personal assets from seizure in a lawsuit.
Why did my quote go up even though I had no accidents?
Insurance rates are influenced by the "collective risk." If your specific vehicle model has become more expensive to repair due to parts shortages or complex technology, or if your postal code has seen an increase in theft or accidents, your premium may rise to reflect that provincial trend.
Does New Brunswick have "No-Fault" insurance?
New Brunswick uses a hybrid system. It is "no-fault" for medical and income replacement benefits (Accident Benefits), meaning you get help immediately regardless of who caused the crash. However, it still allows for lawsuits against at-fault drivers for pain and suffering (subject to the minor injury cap) and property damage.
Can I get a quote if I only have a GDL (Graduated Driver’s License)?
Yes. Drivers in the Graduated Driver's License program can obtain quotes, but they are typically higher due to the lack of experience. Completing a recognized driver training course is the best way for a GDL holder to lower their initial quote.
What is the impact of winter tires on my insurance quote?
Most insurers in New Brunswick offer a small discount (usually around 2% to 5%) if you attest that your vehicle is equipped with four winter tires during the snowy months. This reflects the lower statistical likelihood of at-fault "sliding" accidents.
Next Steps for New Brunswick Drivers
After receiving your auto insurance quotes, your next action should be to verify the reputation and claims-handling history of the provider. A quote is a promise of future service; use resources like the FCNB website to ensure the company is licensed and in good standing. Once you select a quote, read the "Policy Wordings" carefully—specifically the exclusions section—to understand exactly what is not covered before you sign the final application.
Image Gallery
Select an image to open it in a new tab.

Celine Dubois
Contemporary Living and Global Arts Columnist
