Why Insurance for Fitness Trainers Matters: A Comprehensive Guide to Professional Risk Management
Insurance for fitness trainers is a fundamental requirement for risk mitigation, designed to protect professionals from the financial and legal consequences of client injuries, equipment property damage, or professional negligence claims. By securing a comprehensive policy—typically encompassing General Liability and Professional Liability—trainers safeguard their personal assets, maintain professional credibility, and meet the mandatory operational requirements of most gyms and fitness facilities.
The Landscape of Professional Fitness Risks
The fitness industry, while centered on wellness, is inherently physical and subject to high levels of risk. Fitness trainers occupy a unique position where they are responsible for the physical safety and health outcomes of their clients. Even with the most meticulous planning, the potential for accidents is ever-present.
Risk in this sector is broadly categorized into two types: physical injury and professional guidance errors. A client may trip over a resistance band, pull a muscle during a supervised squat, or suffer a more significant medical event during a high-intensity interval training (HIIT) session. Alternatively, a client might claim that a trainer’s advice regarding form, nutrition, or recovery contributed to a chronic injury or failed to achieve promised health outcomes. Without insurance, a single lawsuit resulting from these scenarios can lead to legal costs, settlement payments, and potential bankruptcy for an independent contractor.
Distinguishing Between Primary Insurance Coverages
Fitness professionals must understand that a single policy often consists of several distinct "lines" of coverage. Understanding these is essential for ensuring no gaps exist in one's protection strategy.
General Liability Insurance
Often referred to as "slip and fall" insurance, General Liability (GL) covers third-party bodily injury and property damage. If a client trips over a piece of gym equipment in a space you rent or manage, or if you accidentally damage a facility's expensive flooring, GL coverage typically covers the legal defense costs and medical expenses associated with these incidents.
Professional Liability (Errors and Omissions)
Professional Liability (PL), or E&O, is perhaps the most critical component for a trainer. This coverage addresses claims of negligence regarding the advice or instruction provided. If a client alleges that your programming caused a long-term injury or that you provided improper guidance that led to financial or physical harm, PL insurance provides the defense and indemnity necessary to address these professional disputes.
Product Liability
For trainers who sell supplements, exercise equipment, or nutrition plans, Product Liability is a necessary expansion. It protects against claims that a product you recommended or sold caused harm or sickness to a client.
Requirements and Institutional Compliance
In 2026, the fitness industry is highly professionalized, and the expectation of insurance coverage has become a standard requirement. Whether you are an employee at a large-scale commercial gym or an independent contractor renting space at a boutique studio, insurance is almost always mandated.
Most fitness facilities require trainers to provide a "Certificate of Insurance" (COI) that lists the facility as an "Additionally Insured" party. This arrangement ensures that the gym is shielded from liability for the specific actions of the trainer operating within their facility. Attempting to work in professional environments without providing this documentation often results in a refusal of entry or the termination of facility use agreements. Furthermore, many professional certifications (such as those from the NASM, ACE, or ISSA) either provide access to group insurance rates or require proof of insurance as part of their code of ethics.
Evaluating Costs and Coverage Limits
The cost of insurance for fitness trainers varies based on the scope of their services, their geographic location, and their history of claims. As of 2026, most entry-level policies for individual trainers range between $150 and $400 per year. However, high-risk specialized trainers—such as those focusing on CrossFit, heavy powerlifting, or youth athletics—may face higher premiums due to the increased frequency or severity of potential injuries associated with those modalities.
| Insurance Component | Primary Purpose | Common Coverage Limit |
|---|---|---|
| General Liability | Bodily injury/Property damage | $1,000,000 per occurrence |
| Professional Liability | Negligence in training advice | $1,000,000 per claim |
| Product Liability | Harm caused by products sold | $1,000,000 aggregate |
| Equipment Coverage | Theft/Damage to owned gear | Varies by asset value |
Note: Limits are representative; always verify the specific policy declaration page.
Common Misconceptions About Liability Protection
A frequent error in the fitness industry is the reliance on client waivers as a substitute for insurance. While a liability waiver (or "release of liability") is a vital legal document, it is not a fail-safe. Waivers can be challenged in court, particularly if gross negligence or willful misconduct is alleged. Insurance acts as a secondary layer of protection that kicks in when a waiver is deemed unenforceable or when the legal costs of defending the validity of that waiver become prohibitive.
Another common mistake is assuming that a gym's corporate insurance policy covers independent contractors. In the majority of cases, an employer's policy protects the entity, not the individual contractor. If you are sued, the gym’s insurance carrier will often deny coverage for your personal defense, leaving you legally and financially exposed.
Operational Steps to Maintain Coverage
Securing a policy is only the first step. Maintaining its effectiveness requires consistent administrative hygiene.
- Document Everything: Maintain meticulous records of client assessments, exercise logs, and signed waivers. In the event of a claim, these records are your primary evidence of standard-of-care adherence.
- Report Incidents Promptly: Even minor accidents should be reported to the insurance provider immediately. Delays in notification can sometimes lead to coverage denials.
- Scope of Practice: Insurance policies are written based on the specific services you provide. If you begin offering specialized modalities—such as sports massage or specialized clinical nutritional counseling—you must update your policy. Operating outside your insured scope of practice can void your coverage.
- Annual Reviews: As your business scales in 2026, your revenue and the volume of your clients will change. Periodically audit your policy limits to ensure they are sufficient for the size and scope of your current operation.
Frequently Asked Questions
Does my personal health insurance cover me if I get sued at work? No. Personal health insurance covers your own medical expenses. It does not provide legal defense or professional indemnity for claims brought against you regarding your business activities.
What happens if I work for multiple gym locations? You should ensure your policy is "portable," meaning it covers you regardless of which facility you are training at. Most standard professional liability policies for fitness trainers are designed to follow the trainer, but you must ensure that each gym is provided with its own certificate of insurance as required.
Can I be sued if a client experiences a medical emergency, like a heart attack? While you are generally not responsible for a client's pre-existing medical conditions, you can still be named in a lawsuit if the client or their estate alleges that your training intensity caused or exacerbated the event. Insurance provides the defense required to handle such claims, even if they are ultimately dismissed.
Is insurance tax-deductible for fitness trainers? In many jurisdictions, the premiums paid for professional liability insurance are considered an "ordinary and necessary" business expense. You should consult with a tax professional regarding your specific deduction eligibility based on your business structure (e.g., Sole Proprietorship, LLC).
What if I only train clients online? Online training involves unique risks, including data privacy concerns and potential misinterpretation of virtual instructions. Many modern policies now include specific riders for "cyber liability" or "virtual training" to account for the digital nature of the service.
Final Recommendation
Do not wait for a claim to arise before considering your insurance needs. If you are currently training clients without a dedicated professional liability policy, the next step is to contact a broker who specializes in the fitness and wellness industry. Compare quotes from at least three reputable carriers, paying close attention to the "per-occurrence" vs. "aggregate" limits. Ensure your policy includes a "tail" or "run-off" provision if you anticipate leaving the industry, as claims can sometimes emerge months or years after the service was provided. Prioritizing this coverage is not merely a bureaucratic requirement; it is a critical component of professional longevity and financial security.
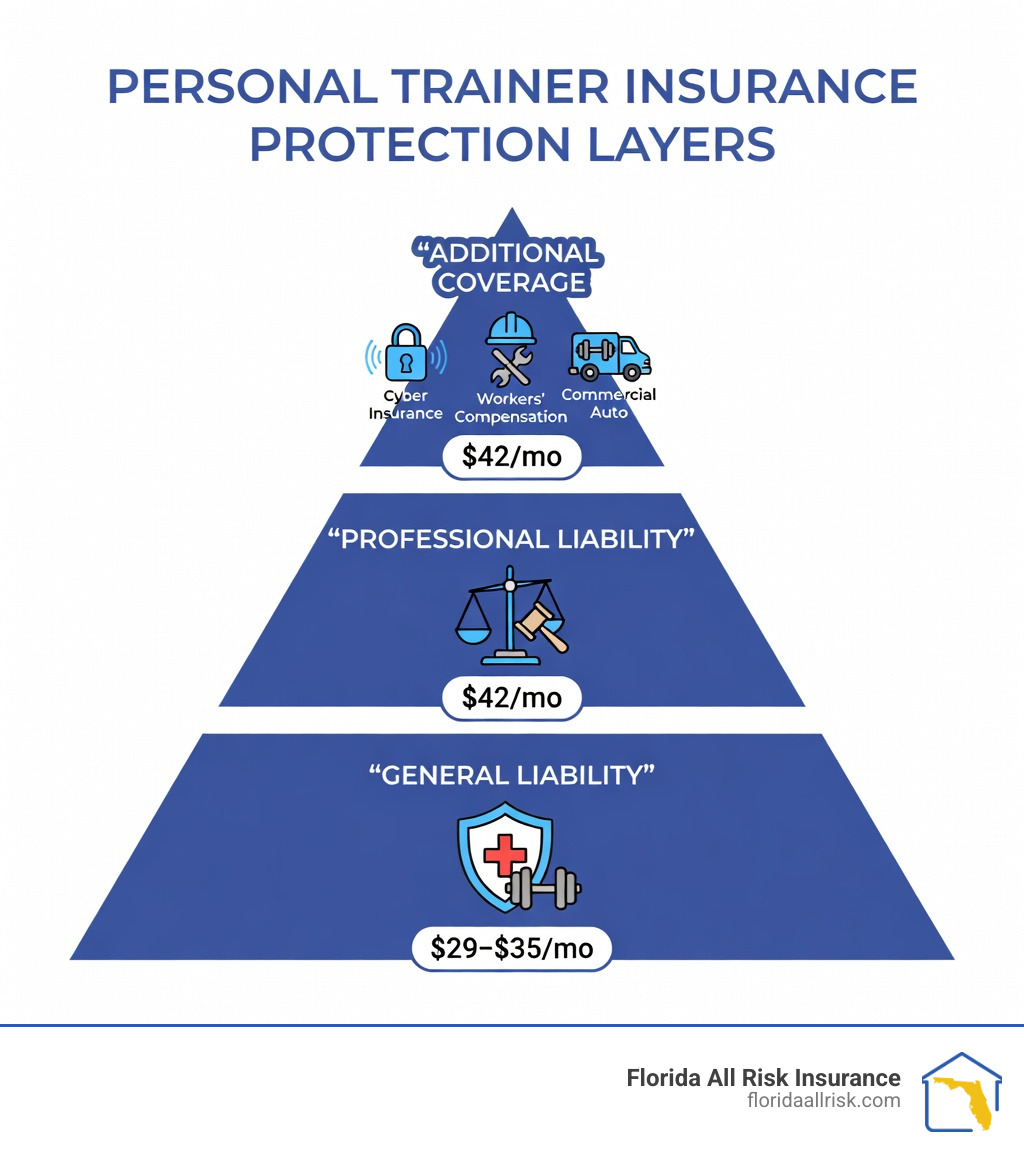
Image Gallery
Select an image to open it in a new tab.
Omar Farooq
EdTech Innovation and Virtual Pedagogy Journalist
