
To choose the best Oklahoma auto insurance in 2026, you must prioritize providers that offer a balance of financial stability, competitive localized rates, and robust Uninsured Motorist (UM) coverage. Begin by verifying the insurer’s AM Best rating, comparing quotes for Oklahoma's 25/50/25 mandatory limits, and evaluating comprehensive options to protect against the state's frequent hail and wind damage.
Oklahoma's insurance market in 2026 presents unique challenges for drivers. From the high frequency of extreme weather events in "Tornado Alley" to the significant percentage of uninsured motorists on the road, selecting a provider is not merely about finding the lowest premium. It requires a strategic understanding of state-specific risks, legal requirements, and the financial health of the companies vying for your business. This guide provides an exhaustive roadmap to navigating the Oklahoma insurance landscape, ensuring you secure coverage that is both legally compliant and financially protective.
Understanding the Oklahoma Insurance Landscape
The Oklahoma insurance environment is shaped by two primary factors: geography and demographics. As a resident, you are operating in a state that consistently ranks among the highest for comprehensive claims due to weather. In 2026, insurers have adjusted their risk models to account for more volatile spring storm seasons, making "Comprehensive" coverage more of a necessity than a luxury for vehicle owners.
Furthermore, Oklahoma remains a "Tort" state. This means that the driver found at fault in an accident is responsible for paying the damages. However, because a notable portion of the population remains underinsured or completely uninsured, the burden of recovery often shifts back to the victim. Choosing a provider in 2026 requires looking beyond the basic liability requirements to ensure your own assets are shielded from these external variables.
The Impact of Credit-Based Insurance Scores
In Oklahoma, state law allows insurance companies to use your credit history as a factor in determining your premium. In 2026, this practice has become highly sophisticated. Providers use "Credit-Based Insurance Scores" to predict the likelihood of a claim. Drivers with excellent credit often see significantly lower rates than those with poor credit, even if their driving records are identical. When choosing a provider, it is essential to ask how much weight they place on credit versus driving history, as some carriers are more "credit-sensitive" than others.
Mandatory Coverage vs. Reality: The 25/50/25 Rule
Before you can choose a provider, you must understand the baseline requirements set by the Oklahoma Insurance Department. As of 2026, the state-mandated minimum liability limits remain at 25/50/25.
- $25,000 for bodily injury per person: This covers the medical expenses of a single person you injure in an accident.
- $50,000 for bodily injury per accident: This is the total cap the insurer will pay for all injuries resulting from one accident.
- $25,000 for property damage: This covers repairs to the other party's vehicle or property.
While these are the legal minimums required to register a vehicle and avoid penalties under the Oklahoma Compulsory Insurance Law, they are often insufficient. A modern SUV or electric vehicle can easily exceed $25,000 in repair costs. If you cause an accident that exceeds these limits, you are personally liable for the difference. When evaluating providers, look for those that offer affordable "umbrella" policies or higher limit structures (such as 100/300/100) to protect your savings and home equity.
Essential Coverage Extensions for Oklahoma Drivers
Choosing the "best" provider often comes down to the quality of their optional coverages. In Oklahoma, the following three extensions are considered essential by industry experts in 2026.
Uninsured/Underinsured Motorist Coverage (UM/UIM)
Oklahoma has historically struggled with high rates of uninsured drivers. UM/UIM coverage protects you if you are hit by someone who lacks insurance or has limits too low to cover your medical bills. Unlike liability insurance, which pays for others, UM/UIM pays for you. In 2026, most top-tier Oklahoma providers will offer this as a standard suggestion; if a provider downplays the importance of UM/UIM, it may be a sign that they are prioritizing low "sticker price" quotes over actual driver security.
Comprehensive Coverage (Weather Protection)
Because Oklahoma sits in the heart of Tornado Alley, hail damage is the most frequent cause of non-collision claims. Comprehensive insurance covers damage from "acts of God," including wind, hail, flood, and fire. When comparing providers, pay close attention to their glass replacement policies. Some Oklahoma insurers offer a "Full Glass" endorsement, which allows you to replace a cracked windshield (common during Oklahoma’s temperature swings) without paying a deductible.
Medical Payments (MedPay)
MedPay is an optional add-on in Oklahoma that covers medical or funeral expenses for you and your passengers regardless of fault. Given the rising costs of healthcare in 2026, MedPay can act as a vital buffer, covering health insurance deductibles and immediate emergency room costs following a collision.
How to Evaluate Insurance Provider Stability
The best price is irrelevant if the company cannot pay your claim after a massive hailstorm. Financial stability is the most critical metric for long-term satisfaction.
- Check AM Best Ratings: AM Best is the industry standard for creditworthiness. Look for companies rated "A-" (Excellent) or higher. This ensures the company has the reserves to handle catastrophic losses across the state.
- Review the Complaint Index: The Oklahoma Insurance Department publishes an annual report detailing the number of consumer complaints filed against each carrier relative to their market share. A low complaint index indicates that the company resolves disputes and pays claims fairly.
- Local Adjuster Presence: Some national "budget" carriers use remote adjusters or AI-based photo estimates for everything. In 2026, the best Oklahoma providers maintain a network of local adjusters who understand the specific costs of labor and parts in regions like Oklahoma City, Tulsa, and Lawton.
Comparing the Top Providers in Oklahoma (2026 Data)
The following table compares the leading insurance carriers in Oklahoma based on their 2026 market performance, typical customer profiles, and specific strengths within the state.
| Provider | Best For... | Financial Strength (AM Best) | Key Feature for OK Drivers |
|---|---|---|---|
| State Farm | Localized Service | A++ | Largest network of local agents in rural OK. |
| Progressive | Tech-Savvy Drivers | A+ | Snapshot program for low-mileage discounts. |
| Geico | Budget-Conscious | A++ | Highly competitive rates for government/military. |
| USA | Military Families | A++ | Exceptional service for Tinker/Altus AFB personnel. |
| Liberty Mutual | New Car Owners | A | Better Car Replacement™ coverage options. |
| Shelter Insurance | Regional Expertise | A | Deep understanding of midwest weather risks. |
Steps to Choosing the Right Provider
Finding the right provider in 2026 requires a systematic approach. Follow these steps to ensure you are getting the best value and protection.
Step 1: Gather Your Data
Before requesting quotes, have your vehicle identification number (VIN), your driver’s license number, and a copy of your current "Declarations Page" ready. Your Declarations Page is the best tool for comparison because it shows exactly what limits and deductibles you have now, allowing for an "apples-to-apples" comparison with new quotes.
Step 2: Request Multiple Quotes
Never settle for the first quote. Obtain at least three quotes from different types of insurers: a large national brand (like Geico), a captive agent brand (like State Farm), and an independent agency that represents multiple smaller carriers.
Step 3: Evaluate the Deductible Structure
In Oklahoma, many drivers choose a $500 or $1,000 deductible. However, in 2026, some providers offer "vanishing deductibles" where your deductible decreases for every year you drive without an accident. This can be a significant benefit in a state where minor "fender benders" are common in heavy metro traffic.
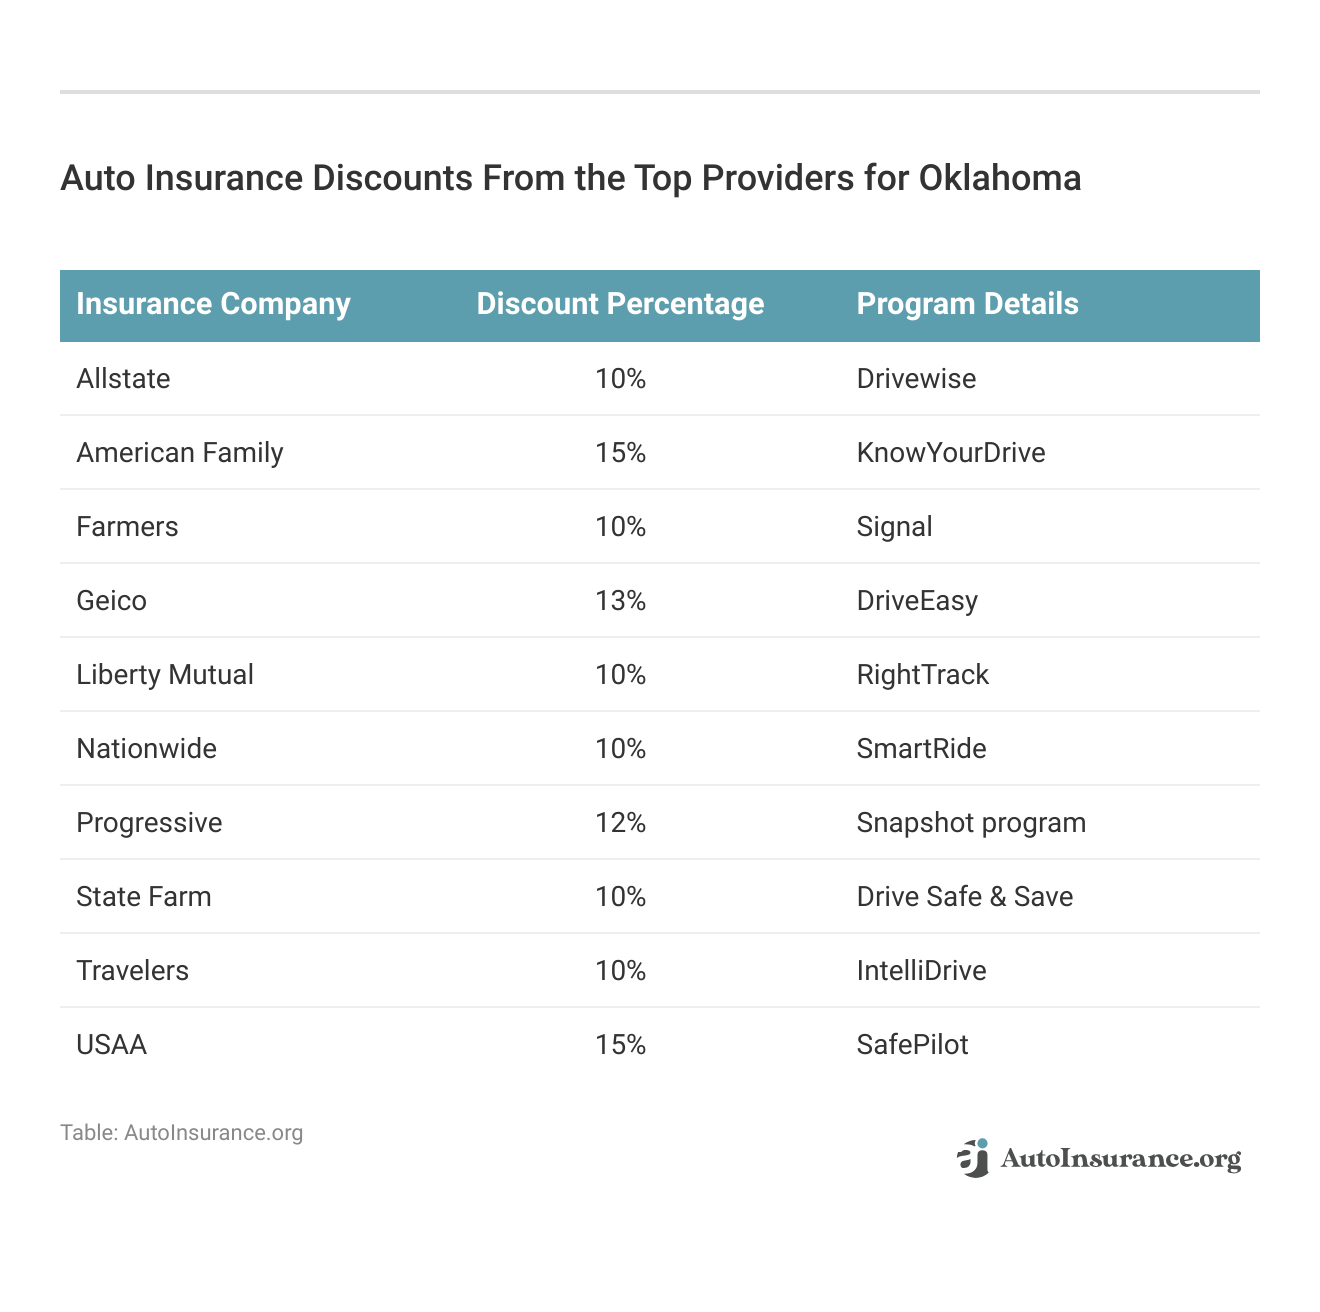
Step 4: Interrogate the Discount List
Insurers offer a variety of discounts that they may not automatically apply. Ask specifically about:
- Multi-Policy: Bundling home and auto is the single most effective way to lower Oklahoma premiums.
- Telematics: Allowing an app to track your driving habits (braking, speed, time of day) can lead to discounts of up to 30% for safe drivers.
- Defensive Driving: Oklahoma drivers over 55 who complete an approved safety course are often eligible for a state-mandated discount.
- Education/Profession: Some carriers offer lower rates for teachers, engineers, or first responders.
Factors Influencing Your Premium in Oklahoma
Your geography within the state matters more than you might think. In 2026, insurance rates in Oklahoma City and Tulsa are typically higher than in rural areas like Woodward or Guymon due to higher traffic density and increased theft rates.
Additionally, the type of vehicle you drive heavily influences your rate. High-performance vehicles or cars with high repair costs (such as those with extensive sensor arrays for self-driving features) will carry higher premiums. In 2026, many Oklahoma providers are also factoring in the "fire risk" of older electric vehicle batteries, so if you are driving an EV, be sure to ask how that specifically impacts your comprehensive premium.
Common Mistakes to Avoid
When choosing an Oklahoma provider, avoid these frequent pitfalls that can lead to financial hardship later:
- Opting for "Liability Only" on Financed Cars: If you have a loan or lease, your lienholder will require Collision and Comprehensive. Even if the car is paid off, "Liability Only" leaves you with zero recourse if a tornado destroys your vehicle.
- Underestimating the Value of UM/UIM: Do not waive this coverage in writing unless you have a significant financial cushion to pay for your own medical bills if hit by an uninsured driver.
- Ignoring the "Excluded Driver" Clause: Be careful about who you allow to drive your car. If you exclude a household member to save money on premiums and they get into an accident, your insurance company will not pay a dime.
Frequently Asked Questions
Is Oklahoma a "No-Fault" state for auto insurance?
No, Oklahoma is a "Tort" or "At-Fault" state. This means the person who causes the accident is legally responsible for the damages. This is why liability insurance is mandatory. If you are not at fault, you generally seek compensation from the other driver's insurance company or sue them directly.
What happens if I drive without insurance in Oklahoma?
Driving without insurance in Oklahoma is a serious offense. In 2026, the state utilizes real-time verification systems linked to law enforcement databases. Penalties include fines up to $250, suspension of driving privileges, and the impoundment of your vehicle. Furthermore, you will likely be required to carry an SR-22 filing for several years, which significantly increases your future premiums.
Does Oklahoma auto insurance cover hail damage?
Yes, but only if you have Comprehensive coverage. Standard liability insurance does not cover weather-related damage. Because hail is so frequent in Oklahoma, it is highly recommended to carry comprehensive coverage with a manageable deductible.
How does my ZIP code affect my Oklahoma insurance rate?
Insurers analyze claim frequency, crime rates, and weather patterns by ZIP code. For example, living in an area of Oklahoma City with high rates of vehicle theft or frequent localized flooding will result in higher premiums than living in a safer, more elevated suburb.
Can I change my insurance provider at any time?
Yes, you can switch insurance providers at any time in Oklahoma. You do not have to wait for your current policy to expire. If you find a better rate in 2026, you can cancel your old policy and receive a pro-rated refund for the unused portion of your premium. Just ensure your new policy is active before canceling the old one to avoid a "lapse in coverage," which can trigger higher future rates.
Final Recommendation
To secure the best Oklahoma auto insurance in 2026, your next action should be to audit your current coverage against the state's rising medical and repair costs. Do not simply renew your existing policy. Instead, contact an independent agent who can run a "loss run report" for you and provide a side-by-side comparison of national carriers like Progressive and regional experts like Shelter Insurance. Prioritize Uninsured Motorist coverage and a low Comprehensive deductible to specifically address the unique risks of driving in the Sooner State.
Image Gallery
Select an image to open it in a new tab.


Declan O'Connor
Higher Education and Campus Culture Reporter
