
Platinum auto insurance is a premium tier of vehicle coverage that bundles high-limit liability with specialized endorsements like new car replacement and OEM parts coverage. It is designed for drivers who prioritize comprehensive financial protection and convenience over the lowest possible monthly premium, offering a specialized safety net that exceeds standard policy limits.
While standard insurance policies focus on meeting state minimums or providing basic collision and comprehensive protection, platinum auto insurance serves as an all-inclusive package. In the 2026 insurance market, where vehicle technology—specifically Advanced Driver Assistance Systems (ADAS) and electric vehicle (EV) components—has made repairs significantly more expensive, these premium tiers have evolved to address modern automotive complexities.
The Anatomy of a Platinum Policy
Platinum insurance is not a single government-regulated product but rather a branding designation used by major carriers to denote their most robust coverage bundles. When an insurer labels a policy "Platinum," they are generally combining several optional endorsements into one cohesive plan.
Total Loss Replacement and New Car Replacement
One of the cornerstone features of platinum-level coverage is the transition from "Actual Cash Value" (ACV) to "Replacement Cost" or "New Car Replacement." In a standard policy, if your car is totaled, the insurer pays you what the car was worth at the moment of the crash—which includes depreciation.
With Platinum New Car Replacement, if your vehicle is totaled within a specific timeframe (often the first two to three years or 30,000 miles), the insurer provides the funds to purchase a brand-new vehicle of the same make and model. This prevents the "depreciation gap" that often leaves drivers owing more on their car loan than the insurance payout provides.
Original Equipment Manufacturer (OEM) Parts Coverage
Modern vehicles in 2026 are essentially computers on wheels. A windshield is no longer just glass; it is a housing unit for LiDAR sensors and cameras that require precise calibration. Standard policies often allow repair shops to use "Aftermarket" or "Like Kind and Quality" (LKQ) parts to save costs.
Platinum policies typically include an OEM Parts Endorsement, ensuring that any repairs are completed using components made by the original manufacturer. This is critical for maintaining vehicle warranties and ensuring that safety sensors function exactly as the manufacturer intended.
Enhanced Liability Limits
While a standard policy might offer liability limits of 100/300/100 ($100,000 per person, $300,000 per accident, $100,000 for property damage), platinum packages often start at 250/500/100 or higher. In a litigious environment, these higher limits protect your personal assets—such as your home or savings—from being seized to settle a judgment if you are found at fault in a major accident.
Financial Protections and Deductible Perks
Beyond the physical repair of the vehicle, platinum auto insurance addresses the financial friction points of the claims process. These features are designed to reward safe driving and minimize out-of-pocket expenses during a crisis.
Disappearing Deductibles
Many platinum plans include a Deductible Rewards or Disappearing Deductible feature. For every year you drive without an accident or a claim, the insurer reduces your deductible by a set amount (e.g., $100 per year). Over time, your deductible can reach $0. This incentivizes safe driving while providing a tangible financial benefit to long-term policyholders.
Accident Forgiveness
In a standard insurance ecosystem, a single at-fault accident can cause premiums to spike by 30% to 50% for three to five years. Platinum packages usually include Accident Forgiveness from day one. This means your first at-fault accident will not result in a rate increase, providing significant long-term savings for drivers who may have a momentary lapse in judgment or encounter unavoidable road hazards.
Gap Insurance Integration
For drivers who lease or finance their vehicles, "Gap" coverage is essential. If the vehicle is totaled and the insurance payout (Actual Cash Value) is less than the remaining loan balance, the driver is responsible for the difference. Platinum policies often bake this protection into the premium, ensuring that the lienholder is paid in full regardless of the vehicle’s depreciated value.
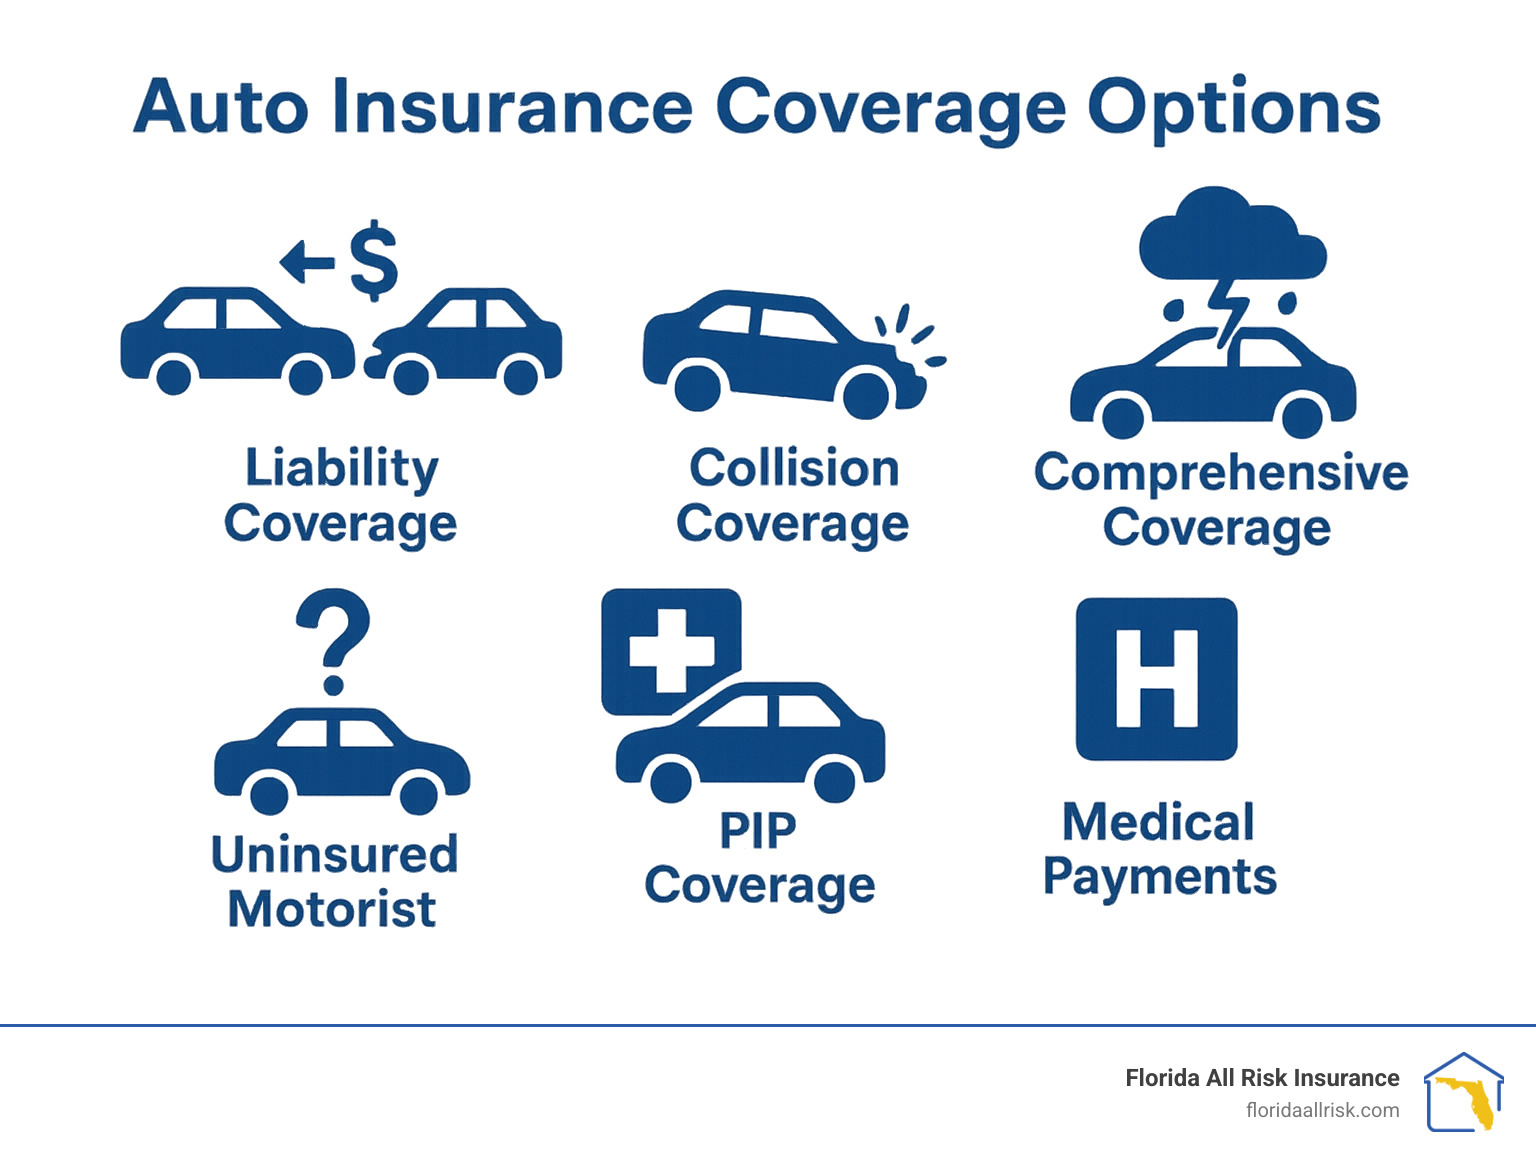
Comparing Standard vs. Platinum Insurance Tiers
To understand the value proposition of a platinum policy, it is helpful to see the side-by-side comparison of typical features available in 2026.
| Feature | Standard Policy | Platinum Policy |
|---|---|---|
| Claim Settlement | Actual Cash Value (Depreciated) | New Car Replacement / Replacement Cost |
| Parts Used | Aftermarket/Refurbished permitted | Guaranteed OEM Parts |
| Deductible | Fixed (e.g., $500 or $1,000) | Disappearing or $0 Glass Deductible |
| Rental Reimbursement | Often limited to $30/day | Enhanced (e.g., $50-$100/day or SUV class) |
| Roadside Assistance | Optional Add-on | Often Included with Trip Interruption |
| Liability Limits | State Minimums to Moderate | High Limits (250/500+) |
| Accident Forgiveness | Rarely included for free | Typically included for the first accident |
Who Actually Needs Platinum Coverage?
While the added protections are objectively better, they come with a higher premium. Determining whether platinum auto insurance is "worth it" depends on your specific vehicle, your financial standing, and your risk tolerance.
Luxury, Performance, and Electric Vehicle Owners
If you drive a high-end vehicle or an EV, platinum coverage is almost a necessity. The specialized nature of EV batteries and the high cost of proprietary tech in luxury sedans mean that aftermarket parts are often unavailable or insufficient. Furthermore, the rapid depreciation of luxury cars in their first two years makes the New Car Replacement feature extremely valuable.
High-Net-Worth Individuals
Individuals with significant assets to protect should look beyond basic coverage. If you are involved in a multi-car accident and your liability limits are exhausted, your personal property and investments are at risk. Platinum policies often serve as the foundation for an Umbrella Policy, providing a seamless layer of protection that shields your entire estate.
Drivers with Long Commutes
If you spend a significant amount of time on the road, your statistical probability of an accident increases. Features like Accident Forgiveness and Enhanced Rental Reimbursement (which ensures you get a comparable vehicle while yours is in the shop) are critical for maintaining your lifestyle and financial stability following a collision.
The Cost Factor: Is the Premium Justified?
In 2026, the price gap between a standard "Full Coverage" policy and a "Platinum" policy typically ranges from 15% to 25%. On a $2,000 annual premium, this represents an additional $300 to $500 per year.
When evaluating this cost, consider the "bundled value." If you were to purchase OEM parts coverage, gap insurance, roadside assistance, and accident forgiveness as separate line-item endorsements, the total cost would often exceed the price of the platinum bundle. Insurers offer these bundles at a slight discount because they are targeting "preferred" drivers—those with high credit scores and clean driving records who are statistically less likely to file frivolous claims.
Furthermore, the $0 Glass Deductible included in many platinum plans can pay for itself in a single claim. With the average cost of windshield replacement for sensor-equipped vehicles now exceeding $1,200 in 2026, avoiding a $500 deductible even once every few years justifies the higher annual premium.
How to Choose the Right Provider
When shopping for platinum auto insurance, it is important to realize that terms vary by carrier. In 2026, several major players dominate this space, each with slight variations in their offerings.
- Check for ADAS Calibration: Ensure the policy explicitly covers the labor costs for calibrating cameras and sensors after a windshield or bumper replacement.
- Verify the Replacement Window: Some companies offer "New Car Replacement" for the first 24 months, while others extend it to 36 months.
- Inquire about "Total Loss" Thresholds: Platinum policies sometimes have a more favorable "total loss" threshold, meaning they are more likely to replace the car rather than attempt a complex, expensive repair that might leave the vehicle with "diminished value."
- Review the Roadside Suite: Top-tier plans should include more than just a tow; they should offer "Trip Interruption" coverage, which pays for lodging and meals if you are stranded far from home.
For more information on standard insurance definitions and state requirements, the National Association of Insurance Commissioners (NAIC) provides updated regulatory guidelines that govern how these policies are marketed.
Frequently Asked Questions
Does platinum insurance cover mechanical breakdowns?
No, platinum auto insurance is still a form of casualty insurance, not a mechanical breakdown warranty. It covers damage resulting from accidents, weather, theft, or vandalism. While it includes roadside assistance for jump-starts or flat tires, it will not pay for a transmission failure or engine malfunction unless that failure was caused by a covered external event (like a collision).
Is gap insurance redundant if I have platinum coverage?
In many cases, yes. Most platinum packages include a form of "Loan/Lease Gap" or "New Car Replacement." However, you should always verify the specific language. If your platinum policy only covers "New Car Replacement" for the first three years, but you have a seven-year car loan, you might need separate gap coverage for the remaining years of the loan.
Will my rates go up if I use the disappearing deductible?
Using your disappearing deductible to pay for a claim does not inherently raise your rates more than a standard claim would. However, once you use the "banked" deductible, it usually resets to its original amount (e.g., $500). You will then have to go through several more years of clean driving to "earn" the $0 deductible back.
Can I get platinum coverage for an older vehicle?
Generally, no. Because features like "New Car Replacement" and "OEM Parts" are central to platinum tiers, insurers typically limit these policies to vehicles that are less than five to seven years old. For older vehicles, the cost of the premium often outweighs the potential payout, and insurers prefer to offer "Standard" or "Value" tiers for those assets.
How does platinum insurance handle ride-sharing?
Most platinum policies are designed for personal use. If you drive for Uber or Lyft, you will likely need a separate "Rideshare Endorsement" even if you have a platinum policy. Some premium carriers are beginning to bundle rideshare coverage into their top-tier plans in 2026, but you must confirm this with your agent to avoid a denial of coverage.
Recommendation for 2026 Drivers
If you own a vehicle manufactured within the last three years, particularly one equipped with advanced safety technology or an electric drivetrain, platinum auto insurance provides the most logical financial protection. The inclusion of OEM parts coverage and new car replacement addresses the most significant risks modern drivers face: technical repair failure and rapid depreciation.
Before signing, request a "Declarations Page" sample to ensure the specific endorsements you value—such as accident forgiveness or glass coverage—are explicitly included in the bundle. For those with high-value assets, integrating this coverage with a personal umbrella policy remains the gold standard for comprehensive financial security.
Image Gallery
Select an image to open it in a new tab.
Mateo Castillo
Decentralized Finance and E-Payments Strategist
