
Deciding whether to use a consumer credit counseling service depends on your total debt load, your monthly cash flow, and your ability to stay disciplined with a multi-year repayment plan. If you are struggling with high-interest credit card debt but have a stable income, a non-profit credit counseling agency can provide a structured Debt Management Plan (DMP) that reduces interest rates and simplifies payments without the severe credit damage of bankruptcy or debt settlement.
Understanding Consumer Credit Counseling: What It Is and How It Works
Consumer credit counseling is a service provided by agencies—typically non-profit organizations—designed to help individuals manage their debt through education, budgeting assistance, and structured repayment programs. In 2026, these services have become increasingly sophisticated, utilizing advanced financial modeling to help consumers navigate a landscape of fluctuating interest rates and digital lending products.
The primary goal of a credit counselor is to review your entire financial picture. This includes your income, expenses, assets, and liabilities. Unlike debt settlement companies, which negotiate to pay back less than what you owe (often at the cost of your credit score), credit counseling focuses on paying back 100% of the principal debt but under much more favorable terms.
A typical session begins with a comprehensive financial review. The counselor looks for areas where you can cut costs and determines if your debt is manageable through simple budgeting. If your debt is "unsecured"—meaning it is not tied to an asset like a house or a car—and it exceeds your ability to pay within a reasonable timeframe, the counselor may recommend a Debt Management Plan (DMP).
Key Indicators: When to Consider Credit Counseling
Deciding to seek professional help is often a difficult emotional hurdle. However, there are specific financial triggers that indicate a consumer credit counseling service is a logical next step.
1. High Interest-to-Principal Ratio
If your monthly credit card statements show that the majority of your payment is going toward interest rather than the principal balance, you are in a "debt trap." Consumer credit counselors have pre-existing agreements with major creditors to lower interest rates—often from 24% or 29% down to somewhere between 0% and 10%.
2. Utilizing More Than 50% of Available Credit
High credit utilization is one of the most significant factors in a declining credit score. If you are consistently maxing out cards or hovering above 50% utilization across all accounts, your "debt-to-limit" ratio is likely hindering your financial mobility.
3. Juggling Multiple Due Dates
When you have five, ten, or more different creditors, the logistical complexity of managing due dates often leads to late fees. A credit counseling service consolidates these into a single monthly payment, which the agency then distributes to your creditors on your behalf.
4. Difficulty Meeting Minimum Payments
If you find yourself choosing between paying the electric bill and making the minimum payment on a Visa card, your debt has become unsustainable. Credit counseling is a proactive measure to prevent default or the need for more drastic legal interventions like bankruptcy.
The Core Mechanism: The Debt Management Plan (DMP)
The Debt Management Plan is the flagship product of most credit counseling agencies. It is a formal agreement between you, the agency, and your creditors.
When you enter a DMP, the agency contacts your creditors to negotiate "concessions." These concessions typically include:
- Reduced Interest Rates: Creditors agree to lower the APR to a fixed, manageable rate.
- Waiver of Fees: Most creditors will agree to stop charging late fees or over-limit fees once you are enrolled and making consistent payments.
- Re-aging Accounts: Some creditors will "re-age" your account, which means they will report the account as "current" to the credit bureaus even if it was previously delinquent, provided you make a series of consecutive payments on the DMP.
In exchange for these benefits, you agree to close your credit card accounts. This is a critical requirement. You cannot continue to accrue new debt while the agency is negotiating lower rates to help you pay off old debt. Most DMPs are designed to be completed within 36 to 60 months.
Comparing Financial Recovery Options
It is essential to understand how credit counseling differs from other forms of debt relief. The following table illustrates the key differences in 2026.
| Feature | Consumer Credit Counseling (DMP) | Debt Settlement | Chapter 7 Bankruptcy | Debt Consolidation Loan |
|---|---|---|---|---|
| Principal Paid | 100% | 40%–60% (typically) | 0% (on discharged debt) | 100% |
| Interest Rates | Reduced (0%–10%) | N/A (accrues until settled) | Eliminated | Varies by credit score |
| Credit Score Impact | Moderate/Temporary Dip | Severe/Long-term Damage | Major (stays for 10 years) | Neutral to Positive |
| Duration | 3 to 5 Years | 2 to 4 Years | 4 to 6 Months | 2 to 7 Years |
| Type of Debt | Unsecured only | Unsecured only | Most unsecured debt | Varies |
| Fees | Small monthly (approx. $25-$50) | Percentage of debt saved | Legal & Filing Fees | Origination Fees |
The Pros and Cons of Consumer Credit Counseling
The Advantages
The most immediate benefit of credit counseling is psychological relief. Knowing there is a definitive end date for your debt can reduce the stress associated with financial instability.
Furthermore, the long-term credit impact is generally positive. While closing your accounts may cause a temporary dip in your score due to a reduction in the average age of accounts and total available credit, the consistent "on-time" payment history reported through the DMP eventually builds a much stronger credit profile.
Another advantage is the professional advocacy. You no longer have to speak with debt collectors. Once a DMP is established, the agency handles the communication, and most collection efforts must cease as long as you remain compliant with the plan.
The Disadvantages
The primary drawback is the loss of credit access. Because the accounts in the DMP must be closed, you will not have credit cards available for emergencies unless you have a card that was specifically excluded from the plan (which is rare and often discouraged).
There is also the commitment factor. A DMP is a marathon, not a sprint. If you miss a payment to the agency, your creditors may immediately revoke the lower interest rates and demand the full balance at the original APR.
Finally, while many agencies are non-profit, they are not "free." There is usually a one-time setup fee and a monthly administrative fee. These are regulated by state law and are typically very modest, but they are a cost consideration nonetheless.
How to Choose a Reputable Credit Counseling Agency
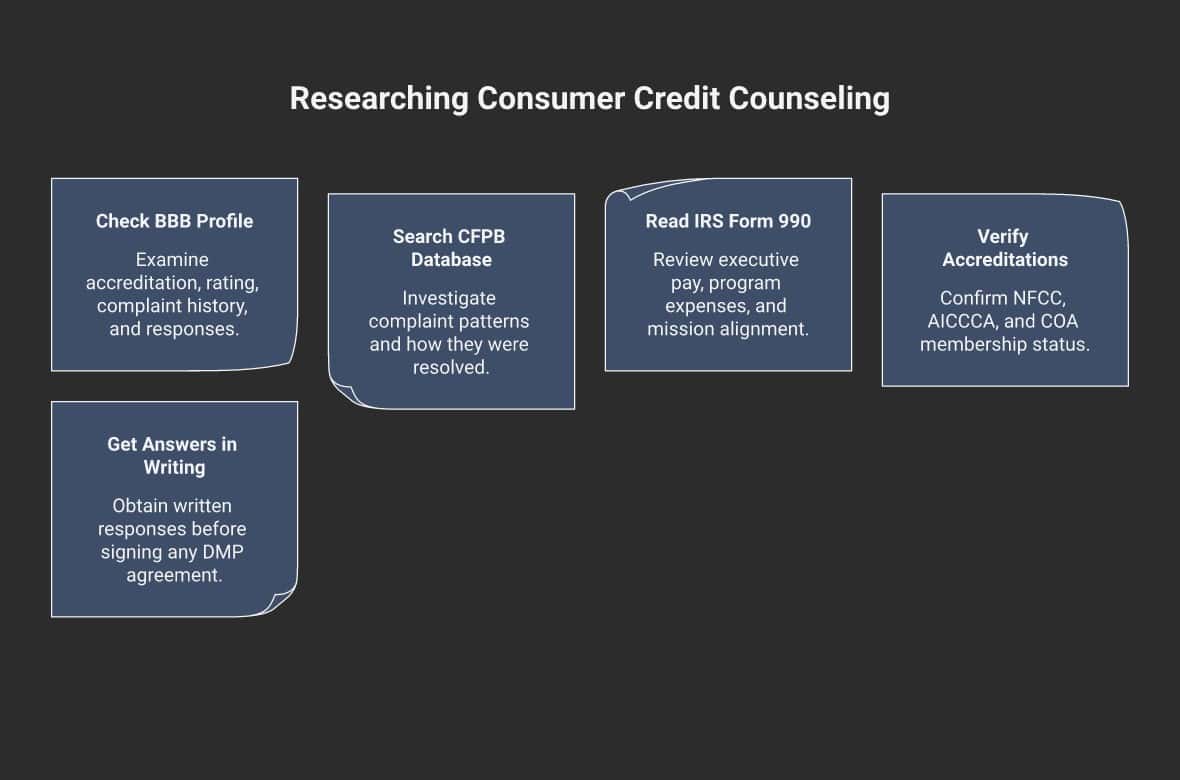
Not all organizations claiming to be "non-profit" have the consumer's best interests at heart. To ensure you are working with a legitimate service in 2026, look for the following credentials:
- Accreditation: Ensure the agency is accredited by the National Foundation for Credit Counseling (NFCC) or the Financial Counseling Association of America (FCAA). These bodies require member agencies to adhere to strict quality and ethical standards.
- Non-Profit Status: Verify their 501(c)(3) status. While this doesn't guarantee quality, it ensures the agency is subject to specific federal oversight regarding their revenue and mission.
- Counselor Certification: Ask if their counselors are independently certified. This ensures the person giving you advice has been trained in budgeting, debt management, and consumer rights.
- Fee Transparency: A reputable agency will provide a written fee schedule before you sign any agreements. According to the Federal Trade Commission (FTC), you should be wary of any agency that asks for large upfront payments or refuses to send you information unless you provide your social security number first.
- Counseling vs. Sales: If the "counselor" spends more time pushing a DMP than analyzing your budget, they are a salesperson, not a counselor. A legitimate session should last 45-90 minutes and focus heavily on your spending habits.
The Step-by-Step Process: What to Expect
If you decide to move forward with a consumer credit counseling service, the process generally follows these steps:
- The Initial Consultation: You will provide a list of all your debts, income sources, and monthly expenses. The counselor will pull a soft-check credit report (which does not hurt your score) to verify the balances.
- Budget Development: The counselor helps you create a realistic "survivable" budget. They will look for ways to decrease spending to ensure you can afford the DMP payment.
- The Proposal Phase: If you choose a DMP, the agency sends proposals to your creditors. They ask for the specific interest rate reductions and fee waivers mentioned earlier.
- Enrollment: Once the creditors accept (and most major banks have standing agreements with NFCC agencies), you sign the final contract.
- Monthly Payments: You make one monthly payment to the agency. In 2026, most agencies use automated clearing house (ACH) transfers to ensure payments are never late.
- Progress Tracking: You will receive monthly statements from both the agency and your creditors, showing your declining balances.
Common Pitfalls and How to Avoid Them
Even with a reputable agency, things can go wrong if you are not prepared.
Failing to Update the Agency on Life Changes: If you lose your job or face a medical emergency, contact the agency immediately. Many creditors are willing to offer a "grace period" or a temporary payment reduction within the DMP, but only if you communicate before the payment is missed.
Ignoring Your Creditor Statements: Even though you are paying the agency, you will still receive statements from your original creditors. It is vital to review these every month to ensure the correct interest rate is being applied and that payments are being credited accurately.
Opening New Credit Lines Early: Taking out a new car loan or another credit card while on a DMP can cause creditors to kick you out of the program. Most plans allow for a "necessity" loan (like an emergency car repair) with prior approval, but generally, you should avoid new debt until the plan is finished.
Alternatives to Credit Counseling
If credit counseling doesn't seem like the right fit, consider these alternatives:
- The Debt Avalanche Method: This is a DIY approach where you pay the minimum on all cards and put every extra dollar toward the card with the highest interest rate. It requires significant discipline and a surplus of cash.
- The Debt Snowball Method: Similar to the avalanche, but you focus on the smallest balance first to gain psychological momentum.
- Debt Consolidation Loans: If your credit score is still relatively high (680+), you might qualify for a personal loan with a lower interest rate than your credit cards. This allows you to pay off the cards and have one fixed monthly payment without closing your accounts.
- Chapter 13 Bankruptcy: This is a court-mandated repayment plan. It is more expensive and legally complex than a DMP but can handle debts that credit counseling cannot, such as tax debt or past-due mortgage payments.
FAQs
Will consumer credit counseling stop debt collector calls?
Yes, in most cases. Once a creditor accepts the proposal for a Debt Management Plan, they generally cease all collection activity. If a third-party collector is involved, providing them with your DMP account number and the agency's contact information is usually enough to stop the calls.
Can I include my student loans or mortgage in a DMP?
No. Consumer credit counseling services are specifically designed for unsecured debt, such as credit cards, personal loans, and some medical bills. Mortgages, car loans, and student loans have different legal structures and interest rate regulations that are not compatible with standard DMPs.
Does credit counseling show up on my credit report?
The fact that you are receiving counseling does not appear on your report. However, if you enter a DMP, some creditors may add a notation that the account is being "managed by a credit counseling agency." While this notation itself doesn't lower your score, it may be visible to future lenders until the debt is paid off.
Is consumer credit counseling a form of debt settlement?
No. Debt settlement involves negotiating to pay less than the full balance, which results in "Settled for less than full amount" on your credit report. Credit counseling involves paying the full principal at a lower interest rate, which is viewed much more favorably by lenders.
What happens if I can't finish the 3-5 year plan?
If you drop out of a DMP, your creditors will likely reset your interest rates to the original high levels and may apply back-dated late fees. It is essential to choose a monthly payment that is truly sustainable for your budget.
Final Recommendation
Should you use a consumer credit counseling service? If you find yourself in a cycle of debt where interest is preventing you from making progress, the answer is yes. It is an effective, non-adversarial way to regain control of your finances.
Next Steps:
- Gather your latest statements for all credit cards and unsecured loans.
- Calculate your total monthly income after taxes.
- Visit the NFCC website to find an accredited non-profit agency.
- Schedule an initial consultation—most agencies offer these for free or a very low cost—to see what interest rate reductions you qualify for.
Note: This guide is for informational purposes only and does not constitute legal or financial advice. Jurisdictional rules regarding debt management vary by state and country.
Image Gallery
Select an image to open it in a new tab.
Omar Farooq
EdTech Innovation and Virtual Pedagogy Journalist
