Applying for life insurance through the Department of Veterans Affairs involves selecting a specific program based on your military service status and health history, completing the appropriate application form, and submitting documentation via the VA’s online portal or mail. Each program, such as VALife or S-DVI, has distinct eligibility criteria, coverage limits, and application pathways that require careful documentation to ensure successful enrollment.
Understanding VA Life Insurance Programs
The Department of Veterans Affairs (VA) administers several life insurance programs, each designed to meet the unique needs of service members, veterans, and their families. Because these programs function differently, the application process is not one-size-fits-all.
The most common programs for veterans in 2026 include:
- VALife (Veterans Affairs Life Insurance): This is a guaranteed acceptance whole life insurance program for veterans with service-connected disabilities. It does not require medical underwriting, meaning your health status does not impact your ability to get approved.
- S-DVI (Service-Disabled Veterans Life Insurance): While largely replaced by VALife for new applicants, existing policyholders may still manage their coverage.
- VGLI (Veterans’ Group Life Insurance): This program allows service members to convert their Servicemembers’ Group Life Insurance (SGLI) to a post-separation policy.
- FSGLI (Family Servicemembers’ Group Life Insurance): A program that provides coverage for the spouses and children of members insured under SGLI.
Before beginning your application, it is essential to identify which program you qualify for. Applying for the incorrect program may result in an immediate rejection, requiring you to restart the process.
Prerequisites for the Application Process
Regardless of the specific policy, the VA requires consistent documentation to verify your identity and military service. Before starting your application, ensure you have the following information prepared:
- Military Service Records: You will generally need your DD Form 214 (Certificate of Release or Discharge from Active Duty). This document confirms your dates of service and discharge characterization, which are critical for establishing eligibility.
- Personal Identification: A valid government-issued ID, such as a driver’s license or passport, is required to verify your identity.
- VA System Access: Most applications are now processed through the official VA.gov website. You will need a verified login—such as a DS Logon, ID.me, or Login.gov account—to access the secure application portals.
- Beneficiary Information: You must have the full legal names, Social Security numbers, and contact information for your designated beneficiaries.
- Payment Details: For programs requiring premiums, you will need to provide banking information for electronic funds transfer (EFT) or set up a deduction from your VA compensation.

Step-by-Step Application Workflow
The digital transformation of VA services has streamlined the application process significantly. For the majority of veterans applying for VALife, the process follows these standard steps:
1. Eligibility Verification
Before submitting an application, use the "Life Insurance Eligibility" tool on the VA website. By entering your service status and disability rating, the system will highlight the specific programs for which you are eligible. Do not skip this step, as it prevents the filing of invalid paperwork.
2. Form Selection
If you are applying for VALife, you will be directed to complete VA Form 29-0679. If you are transitioning from active duty, you may be using SGLV 8714 to convert SGLI to VGLI. Each form is available as a fillable PDF on the VA website, though online submission remains the most efficient method for tracking.
3. Submission via VA.gov
Once you have filled out your chosen form, the digital portal allows you to upload the document directly. This method is preferred because the system immediately validates the required fields, reducing the risk of a "rejected for incomplete data" status.
4. Review and Underwriting
For VALife, since it is a guaranteed acceptance program, there is no medical underwriting. However, for other programs, the VA may contact you if they require further medical evidence or documentation regarding your service record.
5. Confirmation and Policy Issuance
After the VA processes your application, you will receive a notification via your preferred method (usually email or postal mail) confirming your coverage start date. Your policy documents will detail your premium payments and your death benefit amount.
Comparing Key VA Life Insurance Features
| Feature | VALife | VGLI | FSGLI |
|---|---|---|---|
| Eligibility | Veterans with service-connected disabilities | Departing service members | Spouses/children of SGLI holders |
| Medical Exam | Not required | Not required (if within 240 days) | Not required |
| Coverage Cap | $40,000 | $500,000 | $100,000 (spouses) |
| Application Method | Online VA Portal | Online/Mail | Via service member |
Addressing Common Challenges and Troubleshooting
Even with a digitized system, applicants may encounter hurdles. Below are the most common issues and how to resolve them.
Missing DD-214 Records
If you cannot locate your DD-214, the application process will stall. You can request a copy of your records through the National Archives or the VA’s eBenefits portal. Do not submit your application until you have verified your discharge characterization, as "other than honorable" statuses may require an additional administrative review.
Premium Payment Failures
If your initial premium payment fails to process, the VA typically provides a 30-day grace period to update your banking information. If this is missed, your policy may lapse. Always ensure that your payment method is set to "autopay" within the VA dashboard to avoid accidental cancellation.
Beneficiary Confusion
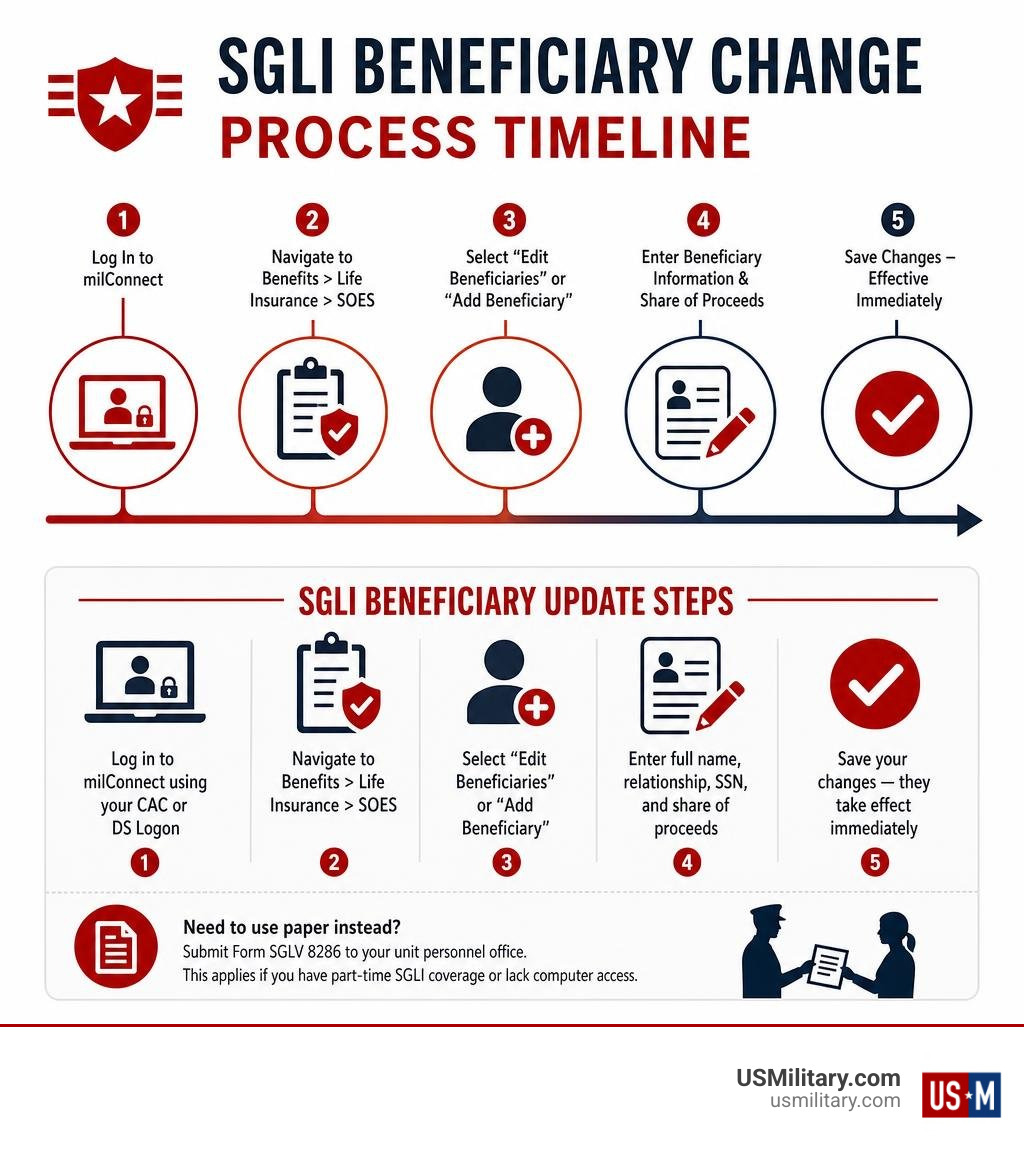
Many applicants make the mistake of not updating their beneficiaries. If you experience a major life event, such as a marriage, divorce, or the birth of a child, you must log into your VA account to update your SGLI or VGLI beneficiary designations. This is a separate process from the initial application and is not updated automatically.
Professional Advice and Limitations
While the VA provides robust resources, these insurance programs are designed for specific populations. If you are a veteran with complex financial planning needs, the VA’s insurance products may not be your only or best option. VALife, for instance, has a coverage cap that may not be sufficient for comprehensive estate planning.
Always consult with a financial advisor or a Veterans Service Officer (VSO) before making final decisions regarding your coverage. A VSO can assist you with the paperwork at no cost and provide personalized guidance based on your specific military background. Note that the VA does not provide private financial advice; it only administers the insurance products themselves.
Frequently Asked Questions
Can I apply for VALife if I have a high-risk medical condition?
Yes. VALife is a guaranteed acceptance program, meaning your health history, medical conditions, and pre-existing disabilities do not affect your approval or your premium rates.
How long does the application process typically take?
The processing time varies depending on the volume of applications. Once you submit a completed electronic application, you can usually expect to receive a confirmation of coverage within 30 to 60 days.
Can I have more than one VA life insurance policy?
Yes, in many cases. It is possible to hold different types of VA insurance if you meet the specific eligibility requirements for each. However, there are often aggregate limits on the total amount of coverage a single individual can hold.
What happens if I move while my application is pending?
You must update your contact information immediately through the VA.gov profile settings. If the VA attempts to mail correspondence to an outdated address, your application could be marked as undeliverable, leading to potential delays or cancellation.
Are VA life insurance premiums tax-deductible?
Generally, no. Life insurance premiums paid to the VA are considered personal expenses and are not tax-deductible for federal or state income tax purposes.
Next Steps for Applicants
To begin your application, log in to your account at VA.gov and navigate to the "Life Insurance" section. First, verify your eligibility using the official tools provided. Gather your DD-214 and banking details, then complete the online application. If you encounter any technical issues, use the "Contact Us" feature on the VA portal to speak with an insurance representative who can provide status updates on your specific file. Ensure you keep a digital copy of your submission receipt for your records.
Image Gallery
Select an image to open it in a new tab.



Declan O'Connor
Higher Education and Campus Culture Reporter
