
A mortgage does not count toward liquid net worth as an asset; instead, it is a liability that reduces your liquid net worth. While your home is a physical asset, it is illiquid. To calculate liquid net worth, you subtract your total liabilities—including your mortgage balance—from your liquid assets like cash and stocks.
Defining the Terms: Total Net Worth vs. Liquid Net Worth
To understand how a mortgage fits into your financial picture in 2026, it is essential first to distinguish between two primary metrics: total net worth and liquid net worth. While they share the same foundational logic—assets minus liabilities—the types of assets included differ significantly.
What is Total Net Worth?
Total net worth is the broadest measure of wealth. It includes everything you own (assets) minus everything you owe (liabilities). In this calculation, your home is a major asset, and your mortgage is a major liability. If your home is worth $600,000 and you owe $400,000 on your mortgage, the $200,000 in equity contributes positively to your total net worth.
What is Liquid Net Worth?
Liquid net worth is a more stringent metric. It measures the amount of wealth you could access in cash almost immediately, typically within a few days to a week, without significant loss of value. This metric is used by financial institutions, investors, and high-net-worth individuals to determine "functional" wealth—the money available to cover emergencies, make new investments, or sustain a lifestyle during a loss of income.
In a liquid net worth calculation, illiquid assets—such as your primary residence, vehicles, jewelry, and private business interests—are excluded. However, the liabilities associated with those assets, specifically your mortgage, are still subtracted from your liquid pool. This provides a sobering but accurate view of your financial flexibility.
How a Mortgage Specifically Impacts Liquid Net Worth
The relationship between a mortgage and liquid net worth is often misunderstood. Many homeowners assume that because their home is excluded from the "liquid asset" column, the mortgage should be excluded from the "liability" column. This is a mistake in formal financial accounting.
The Liability Side of the Ledger
A mortgage is a legal obligation to pay a debt. Even though the debt is secured by a non-liquid asset (the house), the obligation itself impacts your overall liquidity. If you were to sell all your stocks and empty your bank accounts today, that total "pile of cash" is still shadowed by the total amount you owe to creditors.
In most professional financial assessments, including those used for SEC accredited investor status or high-level wealth management, your liquid net worth is calculated as: Liquid Assets (Cash + Equities + Bonds) - Total Liabilities (Mortgage + Auto Loans + Credit Cards + Student Loans).
Why the House is Excluded
The reason the house is not counted in liquid net worth is due to "transaction friction." In the 2026 real estate market, selling a home involves commissions, closing costs, and a time investment that can range from weeks to months. Furthermore, you cannot "spend" 5% of your kitchen to buy groceries. Because the value is locked in a physical structure, it provides no immediate liquidity.

Calculating Liquid Net Worth in 2026: A Step-by-Step Guide
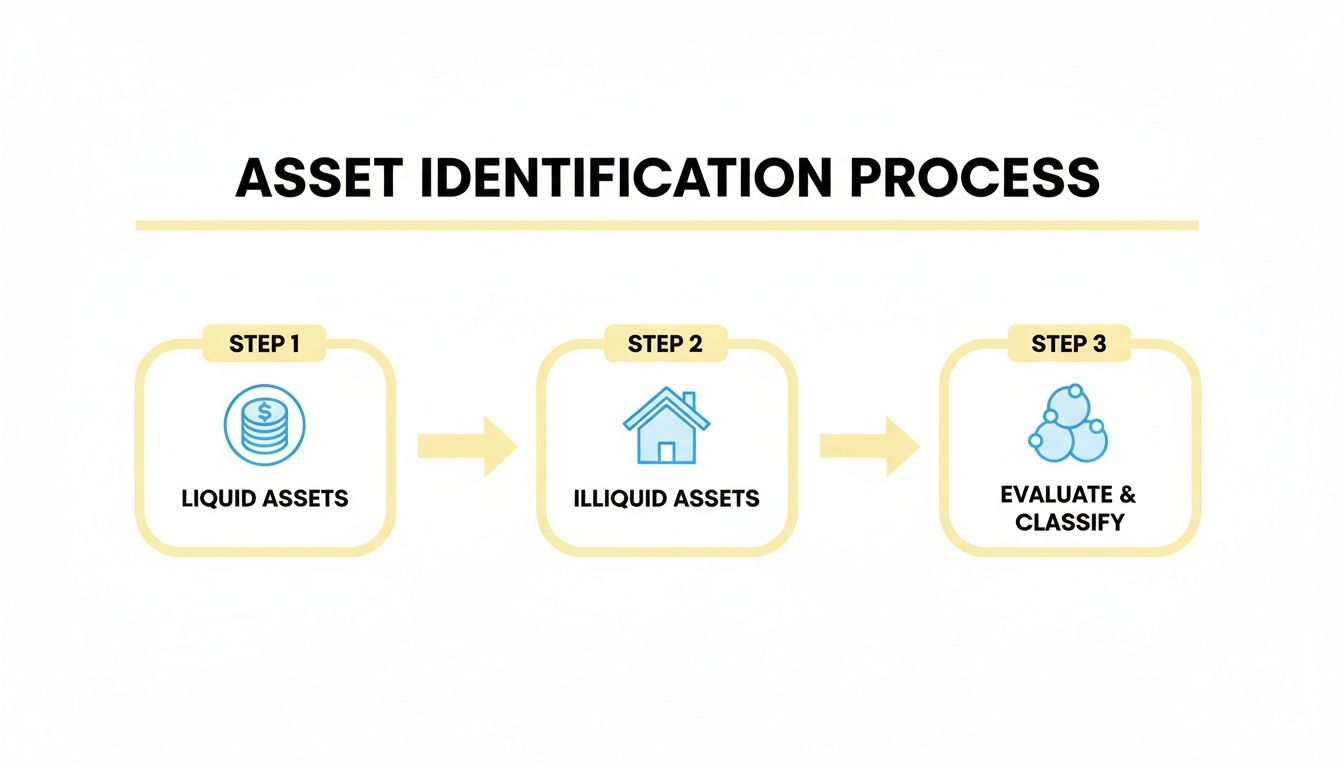
To determine your current standing, you must categorize your holdings accurately. Use the following steps to arrive at a precise figure.
Step 1: Total Your Liquid Assets
Liquid assets include items that are already cash or can be converted to cash instantly at a predictable market price.
- Cash and Cash Equivalents: Checking accounts, high-yield savings accounts (HYSAs), and money market accounts.
- Publicly Traded Securities: Stocks, ETFs, and mutual funds held in taxable brokerage accounts.
- Certificates of Deposit (CDs): Provided they are near maturity or have manageable early-withdrawal penalties.
- Bonds: Treasury bills and liquid corporate bonds.
Note: Retirement accounts like 401(k)s and IRAs are often excluded from liquid net worth calculations because of age restrictions and tax penalties for early withdrawal.
Step 2: Total Your Liabilities
List every debt you currently owe. This is where the mortgage plays its central role.
- The Mortgage Balance: The current payoff amount, not the original loan amount.
- Personal Loans: Any outstanding unsecured debt.
- Credit Card Debt: The total balance across all cards.
- Student Loans: Both federal and private.
Step 3: The Subtraction
Subtract the total from Step 2 from the total in Step 1.
| Asset/Liability Category | Included in Liquid Net Worth? | Reason for Inclusion/Exclusion |
|---|---|---|
| Checking/Savings | Yes (Asset) | Immediate access to cash. |
| Brokerage Stocks | Yes (Asset) | Can be sold and settled in 1–2 days. |
| Primary Residence | No (Asset) | High transaction costs; time-consuming to sell. |
| Mortgage Balance | Yes (Liability) | It is a mandatory debt that offsets available cash. |
| Retirement (401k) | No (Asset) | Penalties and taxes limit immediate liquidity. |
| Credit Card Debt | Yes (Liability) | Immediate short-term debt obligation. |
| HELOC Balance | Yes (Liability) | Used credit lines are active debts. |
Why Liquid Net Worth Matters More Than Total Net Worth
While total net worth might make you feel wealthier on paper, liquid net worth is the engine of your financial life. There are several reasons why focusing on this number is vital in the current economic landscape of 2026.
1. The "House Rich, Cash Poor" Trap
Many individuals have a total net worth exceeding $1 million, yet they struggle to cover a $5,000 emergency repair. If 90% of your wealth is tied up in your home's equity, your liquid net worth may actually be negative if your mortgage and other debts exceed your cash reserves. This leaves you vulnerable to interest rate spikes or employment shifts.
2. Accredited Investor Status
For those looking to invest in private equity, hedge funds, or certain startups, the Securities and Exchange Commission (SEC) has historically used net worth thresholds to define "accredited investors." A key component of these rules is the exclusion of the value of your primary residence. When the residence is excluded, but the mortgage remains a factor in your broader financial profile, your liquid net worth becomes the primary gatekeeper for these exclusive investment opportunities.
3. Financial Flexibility and Opportunity Cost
Liquid net worth allows you to pivot. Whether it is a "buying opportunity" in a market downturn or the ability to start a business, liquid cash is your primary tool. A heavy mortgage reduces this flexibility because a significant portion of your monthly cash flow is diverted to debt service rather than asset accumulation.
Strategies to Improve Liquid Net Worth While Carrying a Mortgage
If your calculation reveals a lower-than-desired liquid net worth, you have two primary levers: increasing liquid assets or decreasing liabilities.
Strategic Debt Paydown
In 2026, interest rate environments dictate whether you should prioritize paying down your mortgage or investing in the market. If your mortgage rate is significantly lower than the yields available in high-yield savings or the stock market, it may be mathematically superior to keep the debt and grow your liquid assets. However, if you are seeking to improve the "liquid net worth" figure specifically, reducing the mortgage balance is the only way to lower that liability.
Enhancing Cash Reserves
Focusing on "liquid-first" investing—allocating funds to taxable brokerage accounts rather than just 401(k)s—can help balance your net worth. While you lose some tax advantages, you gain liquidity, which improves the ratio of liquid assets to the mortgage liability.
Considering the HELOC Factor
A Home Equity Line of Credit (HELOC) is a unique entity. It is not a liquid asset because it is borrowed money. However, in an emergency, it provides a "bridge" to liquidity. From a strict accounting standpoint, an unused HELOC does not count toward your liquid net worth, but a used HELOC counts as a liability, further depressing the figure.
Common Pitfalls and Misconceptions
"My home equity is liquid if I get a loan."
Many people believe that because they can take out a home equity loan, their mortgage doesn't "count against them." This is false. A loan is simply more debt. Converting home equity into cash via a loan increases your liquid assets but increases your liabilities by the same amount, leaving your liquid net worth unchanged (or slightly lower due to fees).
Ignoring the "Payoff" Reality
When calculating liquid net worth, some people use the "home value minus mortgage" and count that as liquid. This is incorrect. Unless the house is sold and the cash is in the bank, that value remains illiquid. The mortgage remains a standing debt against whatever cash you do have.
Retirement Account Confusion
As of 2026, the debate continues over whether to include Roth IRAs in liquid net worth, as contributions can be withdrawn tax-free. Generally, for a conservative and accurate financial plan, it is best to exclude all retirement accounts to ensure you are measuring "true" liquidity—money that can be spent without compromising your future.
Frequently Asked Questions
Does my mortgage count against me for SEC accredited investor status?
Yes, in a specific way. The SEC rules require an individual to have a net worth of $1 million, excluding the value of the primary residence. If your mortgage exceeds the value of your home (underwater), the excess debt is subtracted from your other assets. Even if not underwater, your mortgage is a debt that factors into your overall financial stability when lenders or private funds review your liquidity.
If I pay off my mortgage, does my liquid net worth go up?
No, it usually stays the same or decreases initially. If you use $100,000 in cash (a liquid asset) to pay off $100,000 of your mortgage (a liability), your liquid net worth remains unchanged because both sides of the equation decreased by the same amount. However, your monthly cash flow improves, which allows you to build liquid assets faster moving forward.
Should I include my second home in liquid net worth?
Generally, no. While a second home or investment property is an asset, it is not liquid. Like a primary residence, it takes time to sell and involves high transaction costs. The mortgage on that second home, however, is a liability that must be subtracted from your liquid assets to find your true liquid net worth.
How does a mortgage affect my ability to get a margin loan?
Lenders look at your liquid net worth to determine your risk profile. A high mortgage relative to your liquid assets suggests that you have high fixed costs. This might make a lender more conservative with the "margin" or leverage they are willing to extend to you, as a market dip could leave you unable to service both the margin call and the mortgage.
Is liquid net worth the same as "cash on hand"?
Not quite. Cash on hand is literally your bank balances. Liquid net worth includes those balances plus things like stocks and bonds, minus all your debts. You could have $50,000 cash on hand but a negative liquid net worth if you owe $60,000 in total debt.
Practical Recommendation
To gain a true understanding of your financial health in 2026, perform a "Liquidity Stress Test" annually. Calculate your liquid net worth by taking your total cash and brokerage balances and subtracting your total mortgage balance and other debts.
If the resulting number is negative, do not panic—this is common for homeowners early in their careers. However, your goal should be to trend toward a positive liquid net worth over time. This ensures that you aren't just "rich on paper" through your home's valuation, but that you possess the actual capital necessary to navigate economic shifts, invest in new opportunities, and maintain financial independence regardless of the real estate market's volatility.
Image Gallery
Select an image to open it in a new tab.
Ingrid Bjornson
Global Cyber Policy and Regulation Analyst
