Finding the Cheapest Auto Insurance Deals in California: A Comprehensive Consumer Guide

Finding the cheapest auto insurance deals in California requires navigating a tightly regulated yet uniquely expensive market shaped by state coverage mandates, high litigation rates, regional cost variations, and specific rating factors like your driving record and zip code. Securing an affordable policy involves understanding minimum liability limits set by the California Department of Insurance, leveraging statutory discounts, maintaining a clean driving history, and strategically comparing quotes from multiple licensed carriers operating within the state.
Understanding California’s Auto Insurance Market and Requirements
To secure the cheapest auto insurance deals in California, you must first understand what the state legally requires of every driver. California operates under a tort system, meaning the driver at fault for an accident is financially responsible for the resulting damages and injuries. Consequently, state law mandates that all vehicle owners carry continuous liability insurance.
As of January 1, 2025, California increased its mandatory minimum liability coverage limits under Senate Bill 1107. The previous limits of 15/30/5 were doubled to ensure drivers have adequate protection against escalating medical and repair costs. The current mandatory minimum requirements are:
- $30,000 for injury or death of one person per accident.
- $60,000 for total injury or death liability per accident when multiple people are hurt.
- $15,000 for property damage liability per accident.
While purchasing only the state minimum liability limits is the most direct way to secure the lowest possible upfront premium, it carries significant financial risk. If you cause an accident that results in severe injuries or property damage exceeding these limits, you remain personally liable for the remaining balance. Therefore, balancing affordability with adequate protection—such as adding comprehensive and collision coverage—is vital, especially if you finance or lease your vehicle.
Core Factors That Influence Auto Insurance Rates in California
Insurance companies in California use complex underwriting algorithms to assess risk and determine your premium. While Proposition 103, passed by voters in 1988, heavily restricted how insurers price policies—prohibiting them from relying solely on zip codes or credit scores—several primary factors still dictate your rates.
Driving Record and Safety History
Your driving history is arguably the most influential factor in determining whether you receive a cheap auto insurance deal. Clean driving records free of at-fault accidents, speeding tickets, and moving violations unlock the lowest tier pricing. Conversely, a single DUI, reckless driving charge, or multiple minor infractions can cause your rates to double or triple, moving you into high-risk pools where standard discounts no longer apply.
Years of Driving Experience
Insurers evaluate how long you have held a valid driver's license. Drivers with fewer than three years of experience face higher premiums due to statistical risk profiles. California law explicitly prohibits insurers from using credit scores to set auto insurance rates, which sets the state apart from most of the country and helps protect drivers with low credit marks from paying inflated prices.
Annual Mileage and Vehicle Use
How much you drive directly correlates with your exposure to risk. Insurers ask for your estimated annual mileage and whether you use your vehicle for a long daily commute, pleasure, or commercial purposes. Low-mileage drivers—those driving under 7,500 or 10,000 miles per year—frequently qualify for significant low-mileage discounts.
Vehicle Make, Model, and Safety Rating
The car you drive impacts your insurance costs. Vehicles with high safety ratings, standard anti-theft devices, and readily available replacement parts are cheaper to insure. Luxury vehicles, sports cars, and cars with expensive electronic components or specialized body panels cost more to repair or replace, driving up comprehensive and collision insurance premiums.
Strategies to Lower Your Car Insurance Premiums in California
Implementing specific, proactive strategies can dramatically reduce your annual auto insurance expenditure without compromising necessary coverage levels.
1. Shop Around and Compare Multiple Quotes
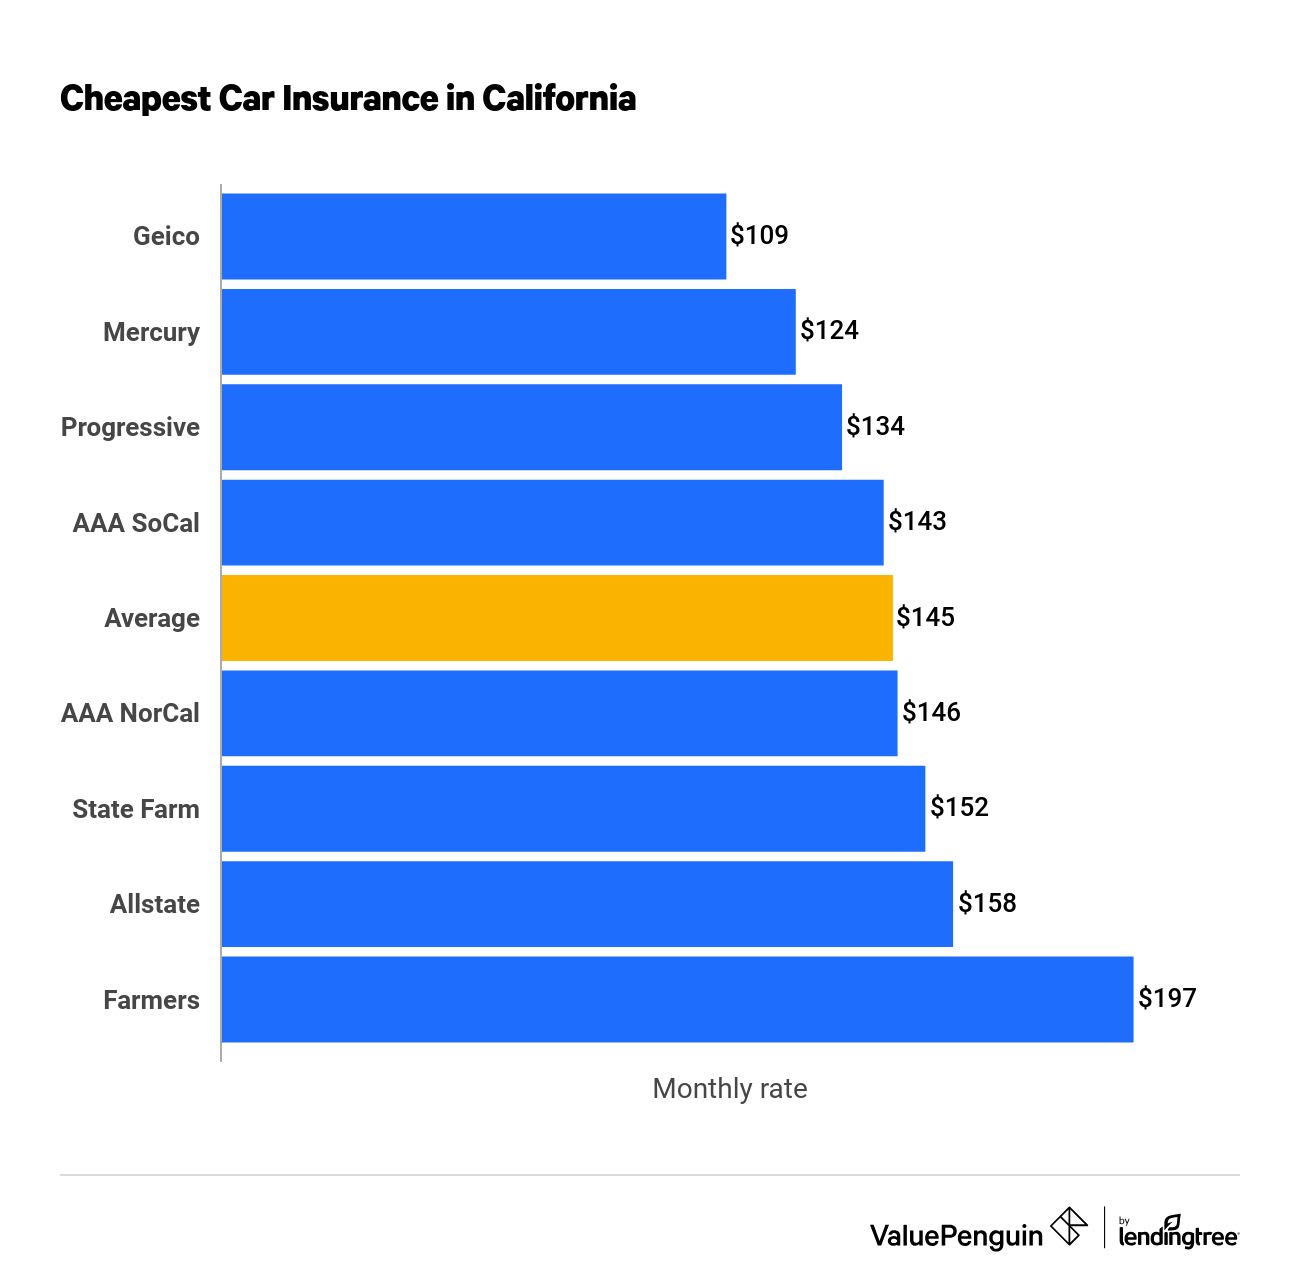
Insurance rates for the exact same coverage limits can vary wildly between companies. Gathering quotes from at least three different carriers—including major national brands and regional California-specific insurers—ensures you identify the most competitive rate. Online comparison tools and direct insurer websites make this process straightforward.
2. Maximize Available Discounts
California insurers offer a wide array of statutory and discretionary discounts. Common options include:
- Good Driver Discount: Mandated by Proposition 103 for drivers who have been licensed for at least three years, have no more than one point on their driving record in the past 36 months, and have not been at fault in an accident resulting in injury or property damage over a specified threshold. This discount must offer at least a 20% reduction from standard rates.
- Bundle and Save: Purchasing your homeowners, renters, or umbrella insurance from the same carrier as your auto policy.
- Multi-Car Discount: Insuring two or more household vehicles under a single policy.
- Paperless and Automatic Payment Discounts: Enrolling in electronic billing and automatic withdrawals.
- Safety Equipment and Telematics: Installing factory-approved anti-theft devices or enrolling in app-based telematics programs that track your actual driving habits, such as speed, braking, and phone distraction.
3. Adjust Your Deductibles Wisely
Raising your comprehensive and collision deductibles from $500 to $1,000 can lower your physical damage premium by 15% to 30%. However, you must ensure you have adequate emergency savings to cover the higher out-of-pocket cost if you need to file a claim.
4. Utilize the California Low Cost Automobile Insurance Program (CLCA)
For low-income California drivers who struggle to afford traditional private insurance, the state administers the California Low Cost Automobile Insurance Program. Established by the state legislature, the CLCA program provides liability insurance to eligible drivers who meet income guidelines, own a vehicle valued below a specific threshold, and have a valid driver's license.
Comparing Coverage Options and Cost Impacts
Understanding how different types of coverage interact with your overall budget helps you make informed purchasing decisions.
| Coverage Type | What It Protects | Cost Impact | Recommended For |
|---|---|---|---|
| State Minimum Liability | Other drivers' injuries and property damage when you are at fault. | Lowest | Older, paid-off cars where the owner has substantial savings. |
| Standard Liability (Higher Limits) | Higher limits for other drivers' injuries and property damage ($50k/$100k+). | Moderate | Most drivers with personal assets to protect. |
| Full Coverage (Liability + Collision + Comprehensive) | Both other parties and your own vehicle against accidents, theft, weather, and vandalism. | Highest | Newer vehicles, financed cars, or leased automobiles. |
| Uninsured/Underinsured Motorist | Your medical bills and vehicle repairs if hit by a driver with no insurance or insufficient coverage. | Low-to-Moderate | Essential protection given high rates of uninsured drivers in California. |
Common Mistakes to Avoid When Buying Car Insurance
Navigating the insurance market involves several pitfalls that can cost drivers hundreds of dollars annually or leave them unprotected during a crisis.
- Underinsuring to Save Money: Buying only the state minimum liability limits to secure the absolute cheapest deal can backfire catastrophically if you cause a major accident, leaving your personal assets exposed to lawsuits.
- Failing to Update Mileage Estimates: If your commute changes or you stop driving long distances, failing to update your annual mileage with your insurer means you are likely paying for risk tiers you no longer fit.
- Lapsing in Coverage: Allowing your policy to lapse, even for a few days, can lead to severe penalties from the Department of Motor Vehicles (DMV), suspension of your vehicle registration, and significantly higher rates when you attempt to reinstate coverage.
- Overlooking Group Affiliations: Many insurers offer exclusive discounts for specific alumni associations, professional organizations, unions, or military personnel. Always check if you qualify for affinity group discounts.
Step-by-Step Action Plan to Secure Your Cheap Policy
To efficiently find and lock in the cheapest auto insurance deal tailored to your situation, follow this sequential process:
- Pull Your Driving Record: Obtain a copy of your official motor vehicle record from the California DMV to check for any unexpected points, errors, or unresolved tickets.
- Determine Your Coverage Needs: Assess your vehicle's current market value, your personal net worth, and whether you require comprehensive and collision protection.
- Gather Baseline Quotes: Visit the California Department of Insurance website to use their premium comparison tools, and request direct quotes from at least four distinct insurance providers.
- Verify Discounts: Explicitly ask each provider if you qualify for the Good Driver Discount, multi-policy bundling, low-mileage programs, or telematics savings.
- Review and Purchase: Compare the total annual or monthly premiums alongside the carrier's customer service ratings and financial stability before finalizing your policy.
By approaching the search methodically, understanding state-specific regulations, and taking full advantage of statutory discounts, you can secure reliable auto insurance in California that fits comfortably within your budget.
Image Gallery
Select an image to open it in a new tab.
Omar Farooq
EdTech Innovation and Virtual Pedagogy Journalist
