Understanding Term Life Insurance in France
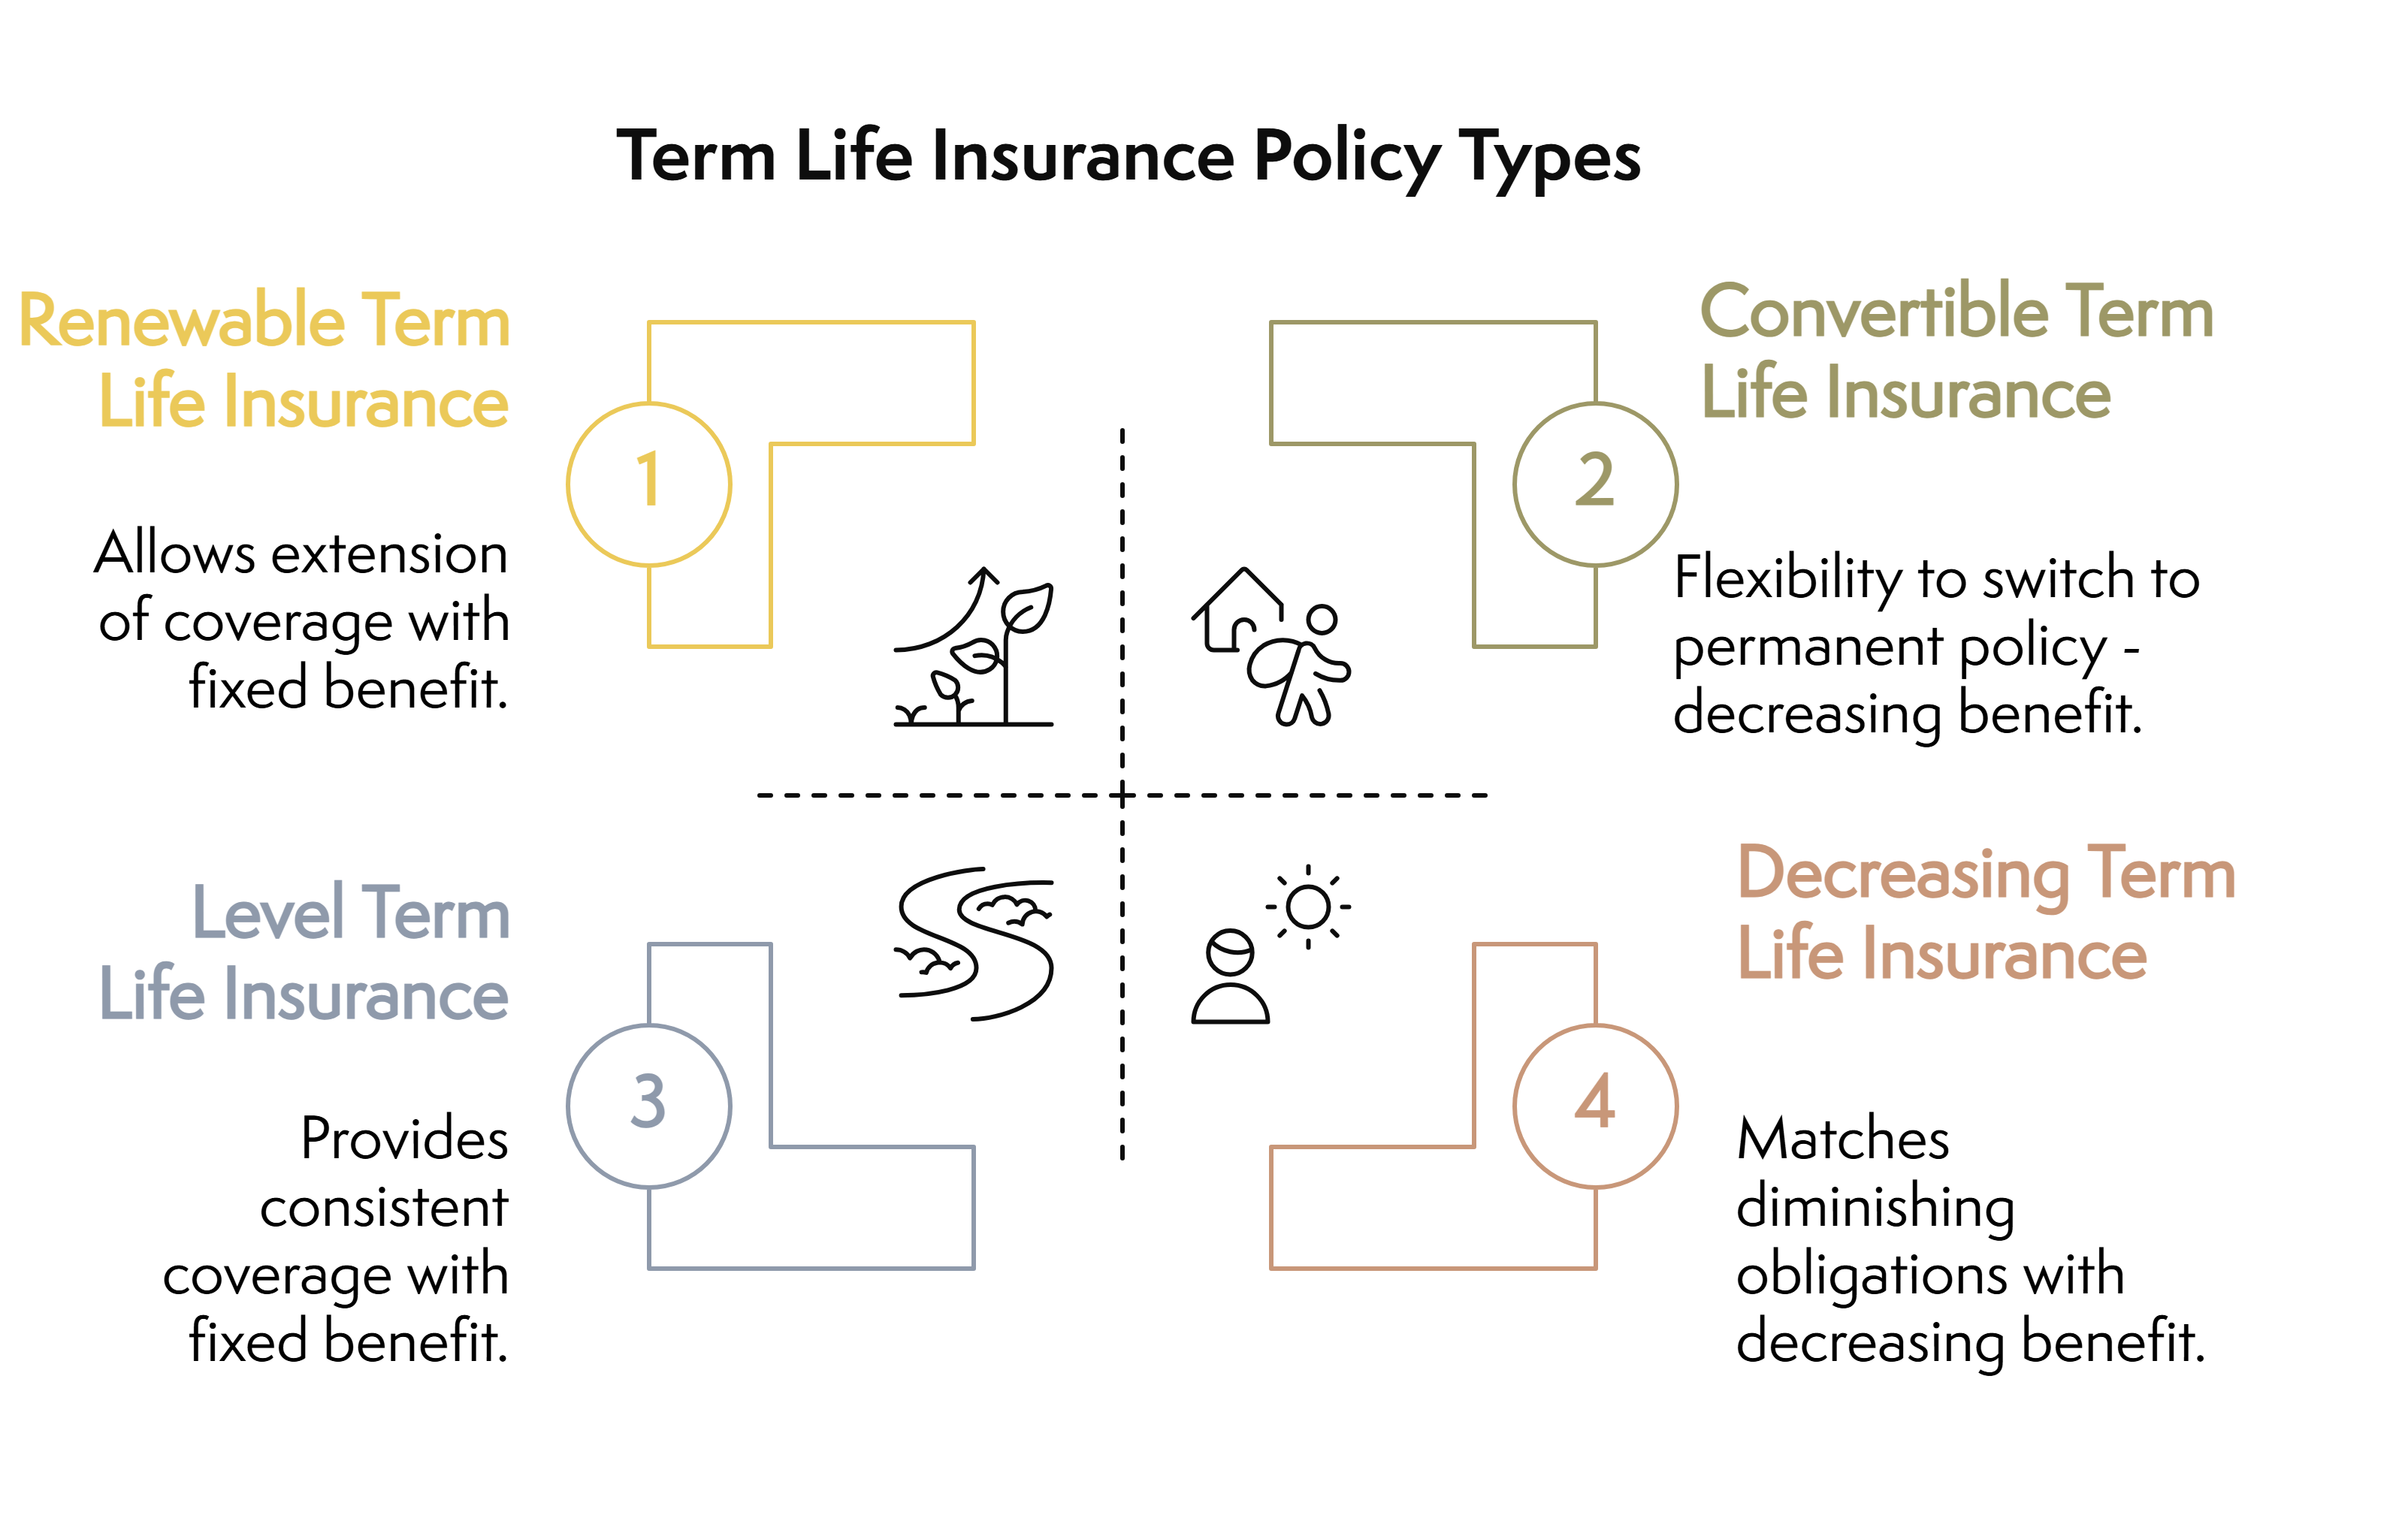
Understanding term life insurance in France involves navigating a specialized financial market known as assurance décès. Unlike whole life or capital accumulation products like assurance-vie, term life insurance is a pure protection instrument designed to pay out a lump sum to designated beneficiaries if the insured passes away during a specific contractual period. This coverage is essential for securing mortgages, protecting dependents, and covering estate taxes without building an investment cash value.
Introduction to Assurance Décès in the French Insurance Market
Navigating the French insurance landscape requires distinguishing between two entirely different financial instruments that share similar English translations: assurance-vie and assurance décès. While assurance-vie is fundamentally a tax-advantaged savings and investment vehicle, assurance décès is the exact equivalent of term life insurance. It is a risk-only policy where you pay periodic premiums in exchange for a guaranteed death benefit paid to your beneficiaries upon your demise within a set timeframe.
For expatriates, residents, and property buyers in France, understanding this distinction is the first critical step. Term life insurance does not accumulate a cash surrender value, nor does it act as a tax-sheltered investment portfolio. Instead, it offers peace of mind and financial security for a defined period. Whether you are purchasing a primary residence, starting a family, or managing business succession, understanding how French insurers structure, price, and regulate these policies is vital to securing adequate financial protection.
Core Types of Term Life Insurance Policies in France
French insurance companies structure term life insurance policies into distinct categories based on duration, payout structure, and the nature of the insured risk. Selecting the correct structure depends entirely on your personal financial liabilities and long-term objectives.
Temporary Flat-Rate Term Life (Assurance Décès Temporaire à Capital Fixe)
This is the most straightforward form of term life insurance available in France. You select a fixed capital sum (e.g., €150,000) and a fixed duration (e.g., 20 years). If you pass away during this window, your beneficiaries receive the exact pre-agreed lump sum. If you outlive the policy term, the contract expires, and no benefits are paid out. Premiums typically remain level or increase predictably as you age, depending on the initial underwriting terms.
Decreasing Term Life Insurance (Assurance Décès Decreissante)
Decreasing term life insurance is heavily utilized in France for a specific purpose: securing real estate loans (prêt immobilier). Under this structure, the insured capital decreases year by year, mirroring the diminishing principal balance of a repayment mortgage. Because the insurer's liability decreases over time, the premiums for decreasing term insurance are generally lower than those for flat-rate policies. If the borrower dies, the remaining mortgage balance is paid off entirely, shielding the surviving family members from inherited debt.
Whole-of-Life vs. Term Distinction (Assurance Décès Vie Entière)
While standard term life insurance expires at a certain age or after a fixed number of years, whole-of-life policies (assurance décès vie entière) guarantee a payout whenever death occurs, provided premiums are maintained. These policies are significantly more expensive and are frequently utilized for estate planning, specifically to offset high French inheritance taxes (droits de succession) levied on beneficiaries.

Key Features, Eligibility, and Underwriting Requirements
Securing a term life insurance policy in France involves a formal underwriting process governed by strict French consumer protection laws and insurance regulations overseen by the Autorité de Contrôle Prudentiel et de Résolution (ACPR).
Medical Questionnaires and Health Declarations
When applying for coverage, applicants must complete a detailed medical questionnaire (questionnaire de santé). Under French law, full transparency is mandatory. Falsifying or omitting material medical history can result in the nullification of the contract under Article L. 113-8 of the French Insurance Code (Code des assurances).
However, legislative reforms such as the Loi Lemoine have introduced significant consumer protections regarding medical screening:
- For policies where the insured credit amount does not exceed €200,000 per insured person, and the loan is scheduled to be fully repaid before the insured reaches the age of 60, medical questionnaires have been entirely eliminated.
- The "right to be forgotten" (droit à l'oubli) allows individuals with a history of certain severe illnesses, such as specific cancers or hepatitis C, to omit disclosing their past medical condition after a designated period post-treatment completion.
Age Limits and Occupational Restrictions
Insurers enforce strict eligibility thresholds based on age and lifestyle:
- Entry Age: Most term life policies require applicants to be between 18 and 65 or 70 years old at inception, with coverage typically terminating by age 75 or 80.
- Occupational and Avocational Hazards: High-risk professions (e.g., construction workers, firefighters, pilots) and extreme sports (e.g., parachuting, scuba diving, rock climbing) require specialized underwriting. Insurers may apply coverage exclusions or charge higher premiums (surprimes) for these activities.
Comparing French Term Life Insurance Options
| Policy Type | Primary Purpose | Capital Evolution | Typical Premium Trend | Expiry / Duration |
|---|---|---|---|---|
| Flat-Rate Term (Temporaire à Capital Fixe) | Family income replacement, debt protection | Constant / Fixed | Level or age-adjusted | Fixed term (e.g., 10, 20, 30 years) |
| Decreasing Term (Temporaire Décroissante) | Securing mortgages (assurance emprunteur) | Decreases annually | Fixed or decreasing | Matches mortgage term (e.g., 15–25 years) |
| Whole-of-Life (Vie Entière) | Estate planning, inheritance tax coverage | Constant / Fixed | Higher, stable or escalating | Lifetime (guaranteed payout) |
The Role of Borrower’s Insurance in French Real Estate
When purchasing residential or commercial property with a mortgage in France, lenders routinely require borrowers to take out borrower's insurance (assurance emprunteur). While legally optional in the strictest sense of the consumer code, no mainstream French bank will issue a substantial mortgage without it.
Delegated Insurance (Délégation d'Assurance)
Historically, French banks forced borrowers to accept the group insurance policy (contrat groupe) offered directly by the lending institution. These group policies apply a uniform risk pool rate regardless of individual health status, which can disadvantage young and healthy applicants.
Thanks to consumer legislation such as the Lagarde law, the Bourquin amendment, and the Loi Lemoine, borrowers have the legal right to substitute the bank's group policy with an external, individual insurance contract (délégation d'assurance) at any time, provided the external policy offers an equivalent level of coverage (équivalence des garanties). Shopping around for external policies frequently yields substantial cost savings over the lifetime of a long-term mortgage.
Mandatory Coverage Scopes
A standard French mortgage insurance package typically covers multiple contingencies:
- Death (Décès): Immediate payout of the remaining capital to settle the bank loan.
- Total and Irreversible Loss of Autonomy (PTIA): Payout triggered if the insured becomes permanently disabled and requires constant third-party assistance for daily living.
- Total Temporary Disability (ITT): Temporary coverage of mortgage payments if illness or injury prevents the insured from working.
- Partial Disability (IPT): Partial compensation if a medical condition limits earning capacity.
Tax Treatment of Term Life Insurance in France
Tax implications vary significantly depending on whether the policy is a standalone protection plan or tied to a mortgage, as well as who pays the premiums and who receives the payout.
Income Tax and Social Charges
For standard term life insurance policies (assurance décès), premiums paid by individuals are generally not tax-deductible from personal income tax (impôt sur le revenu). However, payouts received by beneficiaries are exempt from income tax. Furthermore, they are exempt from French social security charges (prélèvements sociaux), which differentiates them from investment-oriented assurance-vie products.
Inheritance and Estate Taxes
Under standard French inheritance law, payouts from a term life insurance policy are generally excluded from the taxable estate (actif successoral) shared among legal heirs, provided the premiums paid were not manifestly exaggerated (primes manifestement exagérées) given the policyholder's financial situation.
Depending on the age of the insured when premiums were paid and the relationship to the beneficiary, specific tax regimes apply under Articles 990 I and 757 B of the French General Tax Code (Code général des impôts), often allowing substantial tax-free transfers to designated loved ones.
Common Pitfalls and How to Avoid Them
Navigating French insurance contracts requires careful attention to detail. Overlooking minor contractual clauses can result in denied claims or inadequate financial protection.
- Failing to Disclose Pre-Existing Conditions: As noted, omitting medical history on the health questionnaire can lead to policy nullification. Always disclose complete medical records honestly.
- Ignoring Exclusion Clauses: Review the fine print for suicide exclusions (typically applying only during the first year of the policy), hazardous sports exclusions, and geographical limits if you travel or reside abroad frequently.
- Accepting Bank Group Policies Without Comparison: Relying solely on the lender's default insurance offer without exploring external providers can lead to significantly higher over-the-term costs.
- Misunderstanding Joint Policies (Quotité): For co-borrowers, failing to calculate the correct percentage share (quotité) of insurance coverage (e.g., insuring each partner at 100% rather than splitting 50/50) can leave a surviving partner exposed to residual mortgage debt if the primary earner passes away.
Frequently Asked Questions
Can a non-resident buy term life insurance in France?
Yes, non-residents who own property in France or have financial interests within the country can purchase French term life insurance. However, underwriting may require translated medical records, and insurers will assess whether they have the legal framework to service international policyholders.
What happens if I stop paying my term life insurance premiums?
If you miss a premium payment, the insurer will issue a formal notice granting a grace period (typically 30 to 40 days). If the premium remains unpaid at the expiration of this window, the policy lapses, coverage ceases immediately, and all previously paid premiums are forfeited because term life insurance builds no cash value.
Are suicide and risky hobbies covered under French policies?
Suicide is generally excluded during the first year of the contract, provided the policy was taken out in good faith, though full coverage usually activates from the second year onward. Risky hobbies are evaluated on an individual basis; standard policies may exclude extreme sports unless specific riders are purchased and declared.
Can I change my beneficiaries after signing the contract?
Yes, you retain the legal right to modify your designated beneficiaries (clause bénéficiaire) at any time during the life of the policy, provided the beneficiary has not formally accepted the designation (acceptation de la bénéficiaire). Changes should be communicated to the insurer in writing via registered mail or a formal rider.
Is term life insurance mandatory for buying a home in France?
Legally, French law does not mandate insurance to buy a home. Practically, however, no commercial bank will approve a mortgage loan without borrower’s insurance (assurance emprunteur) covering death and disability risks.
Practical Next Actions
To secure the appropriate term life insurance policy in France, begin by defining your exact financial liabilities, such as outstanding mortgage balances, the number of dependents, and future educational expenses. Request quotes from multiple providers or utilize online comparison platforms specializing in French insurance products. If you are securing a mortgage, compare the bank's group insurance offer against independent delegated insurance options to identify potential cost savings. Finally, consult with an independent financial advisor (conseiller en gestion de patrimoine) or insurance broker (courtier) to ensure your policy structure, medical disclosures, and beneficiary clauses align precisely with French legal and tax frameworks.
Image Gallery
Select an image to open it in a new tab.


Akira Tanaka
International Academic Trends Correspondent
