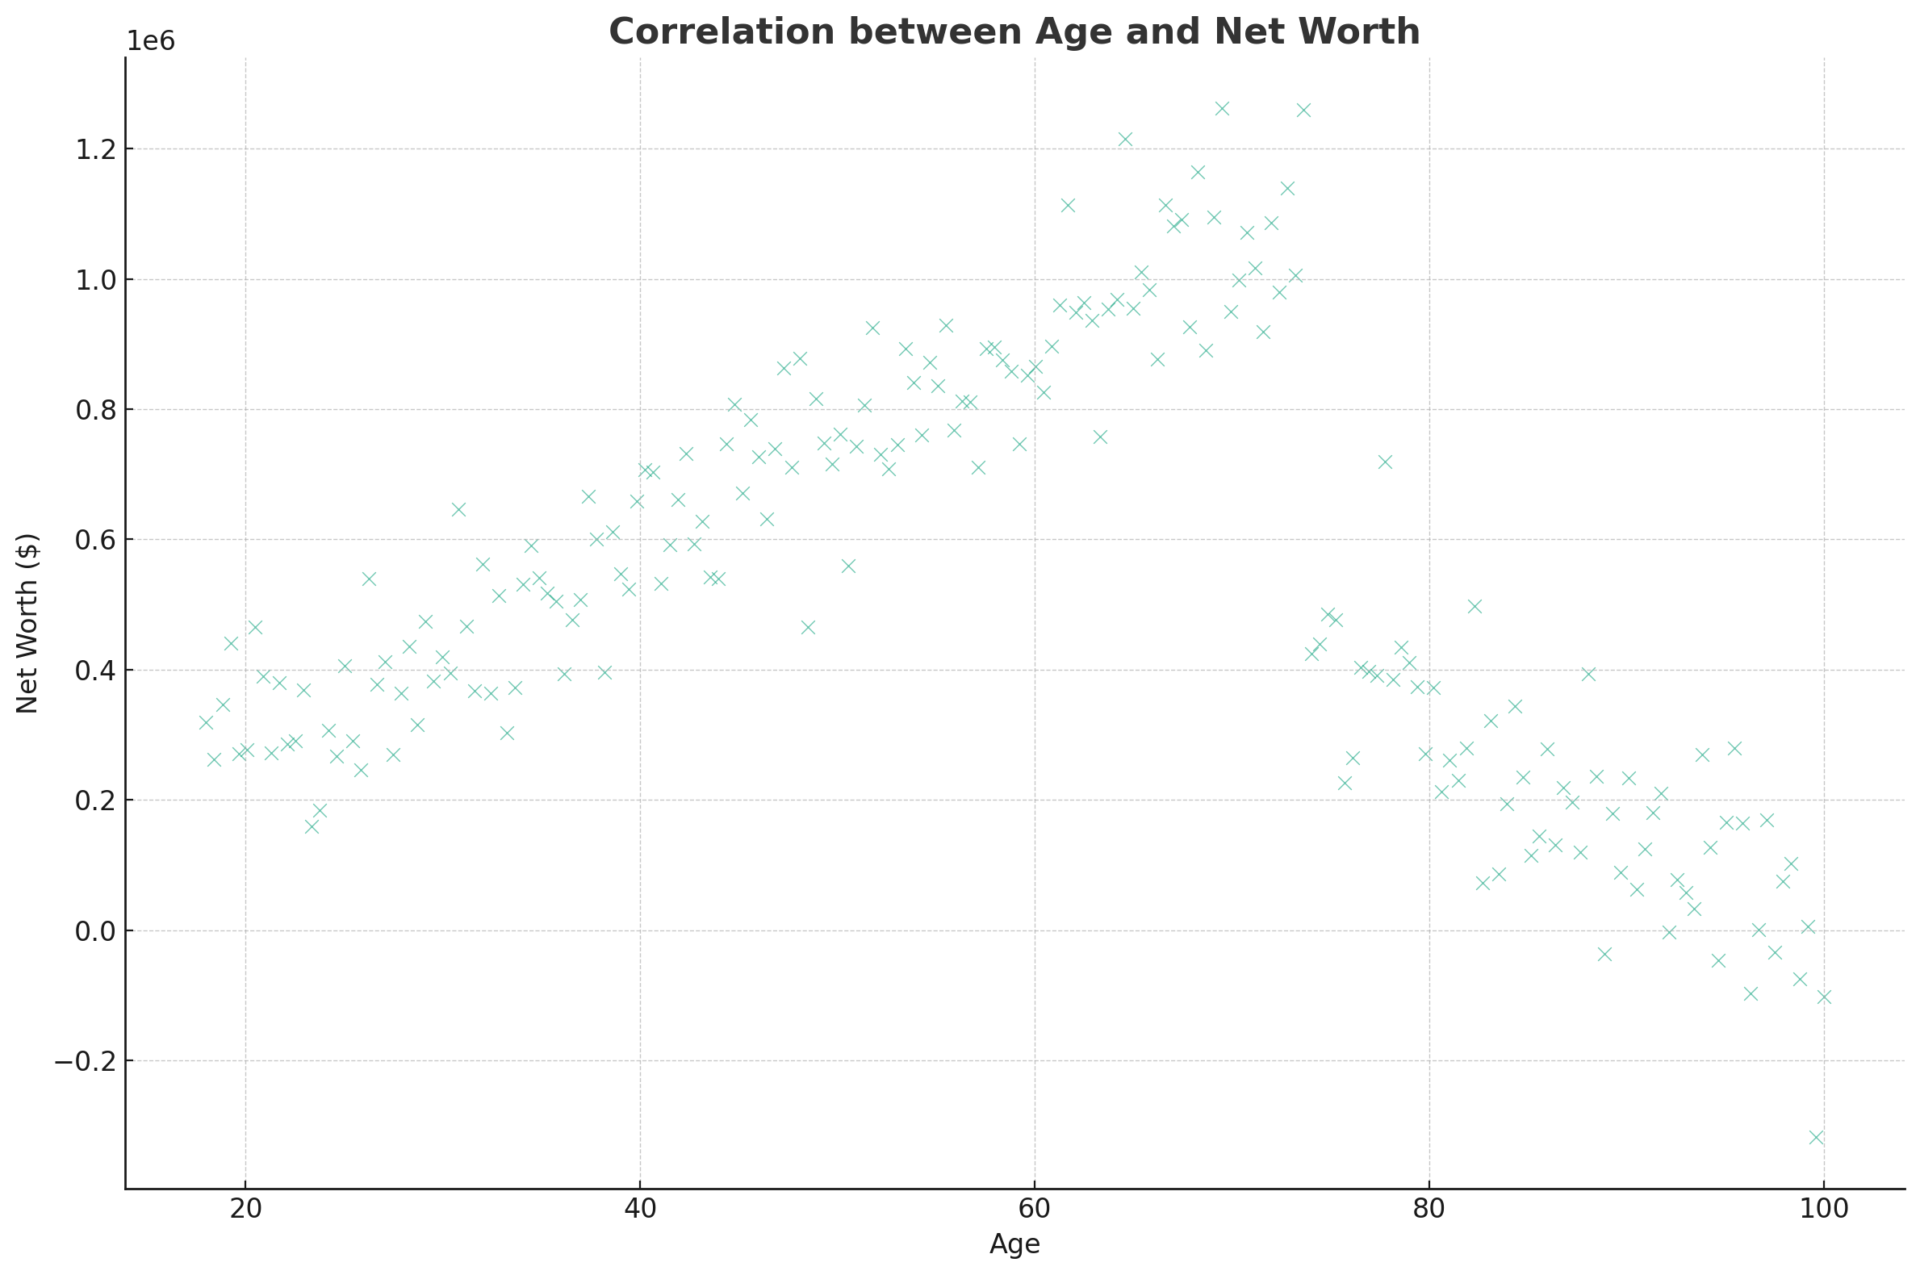
Reaching the top 1 percent of net worth for a specific age group requires a disciplined combination of high income generation, aggressive asset accumulation, strategic tax management, and compounding investments over time. Because net worth thresholds vary dramatically by age—reflecting decades of career progression, asset appreciation, and compounding returns—achieving this elite financial status demands a clear understanding of age-based benchmarks, structural economic leverage, and long-term capital allocation strategies.
To enter the top 1 percent of your age cohort, you must transition from relying solely on earned income to building a robust portfolio of income-producing and appreciating assets. This involves moving beyond traditional employment models, leveraging tax-advantaged accounts, managing liabilities strategically, and scaling business or investment vehicles. The process is not built on overnight success or speculation, but rather on systematic wealth preservation, high savings rates, and disciplined exposure to compounding growth engines like equities, real estate, and private enterprises.
Understanding Net Worth Thresholds by Age Cohort
Net worth is calculated simply as total assets minus total liabilities. Assets include liquid cash, retirement accounts, taxable brokerage portfolios, real estate equity, private business valuations, and valuable personal property. Liabilities encompass mortgages, student loans, consumer credit, and business debts. Because accumulated wealth naturally correlates with time in the workforce, the net worth required to reach the top 1 percent shifts upward as age increases.
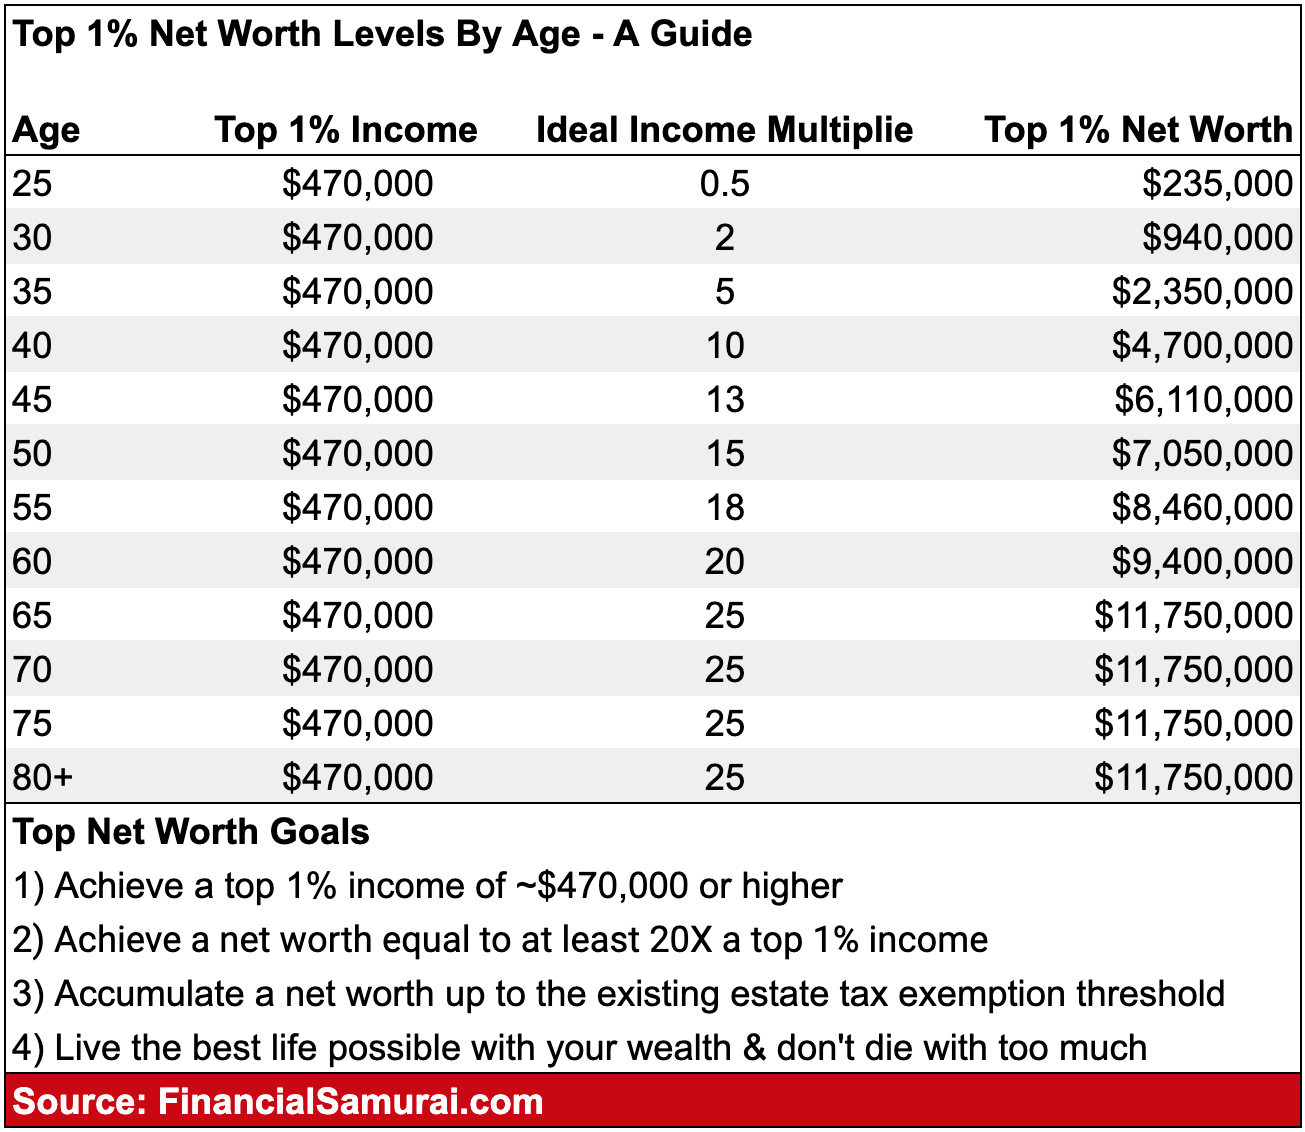
Data compiled from economic surveys, such as the Federal Reserve’s Survey of Consumer Finances, illustrate how the bar for the top 1 percent scales across generations. Under-35 cohorts face a lower absolute threshold due to shorter career windows, while cohorts aged 55 to 64 and above represent the peak accumulation phase, where thresholds often stretch into millions of dollars. Recognizing your target benchmark for your specific age group is the essential first step in designing an accurate financial roadmap.
| Age Group | Estimated Top 1% Net Worth Threshold | Primary Wealth Drivers | Common Financial Constraints |
|---|---|---|---|
| Under 35 | $400,000 – $600,000 | Equity compensation, entrepreneurship, high savings | Student debt, low initial capital, entry-level salaries |
| 35 – 44 | $1,500,000 – $2,500,000 | Business equity, career peak scaling, real estate | Mortgages, childcare costs, lifestyle inflation |
| 45 – 54 | $3,500,000 – $5,000,000 | Senior executive compensation, portfolio compounding | Sandwich generation expenses, tax liabilities |
| 55 – 64 | $7,000,000 – $9,000,000 | Business exits, mature investments, real estate equity | Healthcare costs, transition to wealth preservation |
| 65 and Older | $10,000,000+ | Inheritances, decades of compounding, realized exits | Required minimum distributions, estate transfer |
The Mathematical Foundation: Savings Rate and Income Amplification
Reaching the top 1 percent by net worth is fundamentally a math problem governed by three variables: income, savings rate, and return on investment. While investment returns are subject to market volatility, and income ceilings vary by profession, your savings rate is the variable entirely within your direct control.
High earners who maintain low savings rates frequently fail to reach top-tier net worth brackets due to lifestyle creep—the tendency to expand personal consumption in direct proportion to income growth. Conversely, individuals with moderate incomes who achieve extraordinarily high savings rates (often 50 percent or more of net income) can accelerate their journey into upper wealth tiers, particularly when combined with aggressive capital reinvestment.
To bridge the gap between ordinary accumulation and elite status, you must simultaneously optimize two pillars:
- Income Expansion: Relying solely on a W-2 salary rarely scales quickly enough to reach the top 1 percent at younger ages. High-net-worth individuals typically diversify revenue streams through equity ownership in private businesses, commercial real estate portfolios, intellectual property, or high-commission sales roles.
- Capital Efficiency: Every dollar saved must be deployed efficiently. This means minimizing investment friction, such as high management fees, unnecessary transactional costs, and inefficient tax structures that erode returns over multi-decade time horizons.
Strategic Asset Allocation and Compounding
Once capital is generated and saved, asset allocation dictates the velocity of wealth accumulation. Individuals aiming for the top 1 percent cannot rely exclusively on conservative, low-yield vehicles like traditional savings accounts or fixed-income bonds, especially during inflationary economic cycles. Instead, portfolios must be weighted toward growth-oriented, high-return asset classes while managing downside risk.
Equity Markets and Public Securities
Core equity ownership—via low-cost index funds, exchange-traded funds (ETFs), or carefully selected individual equities—provides broad exposure to global economic growth. For younger investors aiming for the top 1 percent, maintaining a significant allocation to equities harnesses the power of time and long-term market compounding.
Private Business and Entrepreneurship
Statistically, a vast majority of individuals in the top 1 percent derive their wealth not from salaries or public stocks, but from owning private businesses. Building, scaling, and eventually executing a liquidity event or sale of a privately held enterprise remains one of the most reliable catalysts for rapid net worth expansion.
Real Estate Leverage
Real estate offers a dual advantage: appreciation and cash flow, amplified by the judicious use of leverage. Acquiring multi-family residential or commercial properties allows investors to control large asset bases while tenants pay down the underlying debt. Over long periods, real estate acts as both an inflation hedge and a stable source of passive income.
Tax Optimization and Wealth Preservation
As net worth scales toward the top 1 percent, taxation becomes one of the single largest friction points against capital accumulation. Without proactive planning, federal, state, and local taxes can consume nearly half of earned income and significantly erode investment gains. Wealthy individuals employ sophisticated, legal tax strategies to maximize retained capital.
- Tax-Advantaged Accounts: Maximizing contributions to employer-sponsored plans (such as 401(k)s or 403(b)s), IRAs, Health Savings Accounts (HSAs), and utilizing backdoor Roth conversions where applicable shelters investment growth from immediate taxation.
- Capital Gains Management: Holding assets for longer than one year qualifies gains for lower long-term capital gains tax rates. Furthermore, strategic tax-loss harvesting allows investors to offset realized gains with realized losses.
- Entity Structuring: Utilizing corporate structures, limited liability companies (LLCs), and trusts helps shield personal assets from liability while optimizing business tax classifications under applicable tax codes.
(Note: Tax laws are complex and subject to frequent legislative changes. Consult a certified public accountant or licensed financial advisor to align strategies with current federal and state regulations.)
Common Pitfalls on the Path to Elite Net Worth
Attempting to fast-track your way into the top 1 percent often introduces severe financial risks. Recognizing and avoiding common behavioral and strategic traps is essential for preserving capital during market cycles.
- Excessive Leverage: While debt can accelerate returns in real estate or business, over-leveraging personal finances exposes you to catastrophic insolvency during economic downturns or asset corrections.
- Chasing Speculative Trends: High-net-worth accumulation is built on durable assets and cash-flowing businesses, not speculative trading, meme stocks, or unregulated digital tokens. Capital preservation must always precede aggressive speculation.
- Neglecting Insurance and Risk Management: A single medical emergency, lawsuit, or property disaster can wipe out years of disciplined savings. Comprehensive liability, umbrella, and health insurance policies are non-negotiable components of wealth protection.
Frequently Asked Questions
What net worth puts you in the top 1 percent globally versus locally?
Global net worth thresholds for the top 1 percent are significantly lower than country-specific thresholds due to vast disparities in worldwide economic output. For instance, entering the global top 1 percent requires a net worth of approximately $1 million USD, whereas entering the top 1 percent in developed economies like the United States requires significantly higher thresholds, often starting above $5.8 million USD depending on the specific data source and demographic filters applied.
Is high income alone enough to reach the top 1 percent?
High income is rarely sufficient on its own due to progressive income tax structures and lifestyle inflation. A high earner who spends everything they make maintains a net worth of zero. True top-tier net worth is achieved by converting high income into appreciating assets, business equity, and diversified investment portfolios that generate wealth independently of active labor.
How does starting a business compare to climbing the corporate ladder for net worth growth?
While senior corporate executives frequently break into the top 1 percent late in their careers, business ownership offers an asymmetrical upside. Scaling a private enterprise allows an entrepreneur to capture equity value that far exceeds standard executive compensation packages, often compressing the timeline required to reach elite net worth thresholds.
What role does debt play in building a top-tier net worth?
Not all debt is treated equally. High-interest consumer debt (credit cards, personal loans) destroys wealth by compounding against the borrower. Conversely, productive debt—such as mortgages on cash-flowing real estate or loans used to acquire revenue-generating businesses—can accelerate wealth accumulation by allowing individuals to leverage other people's money to acquire appreciating assets.
How often do net worth thresholds for the top 1 percent change?
Thresholds fluctuate continuously based on macroeconomic factors, including stock market performance, real estate valuations, inflation rates, and overall economic growth. Financial institutions and economic research groups typically update these benchmarks annually using comprehensive consumer finance surveys and tax data.
Next Actions for Strategic Wealth Building
Reaching the top 1 percent of net worth and age requires an unyielding commitment to long-term financial planning, income expansion, and rigorous asset management. Begin by auditing your current financial standing: calculate your exact net worth, establish your specific age-cohort benchmark, and evaluate your current savings and investment rates. From there, focus on increasing your primary earning capacity, minimizing tax friction, and systematically channeling surplus capital into high-quality, cash-flowing assets. Treat wealth building as an institutional business model rather than a passive byproduct of time, and continuously adapt your strategy to meet changing economic conditions.
Image Gallery
Select an image to open it in a new tab.




Vivian Cho
Executive IT and Emerging Technologies Reporter
