
Understanding how OSGIL (Ogun State Government Insurance Levy or similar organizational insurance structures) life insurance rates work requires an examination of actuarial risk assessment, the specific underwriting guidelines established by the governing body, and the demographic variables that dictate individual premium costs. As of 2026, these rates are determined by a combination of standardized group underwriting and individual profile adjustments, designed to ensure the financial sustainability of the insurance pool while providing coverage to the target workforce.
The Foundation of OSGIL Rate Calculation
At its core, life insurance pricing functions on the principle of pooling risk. For programs like OSGIL, the objective is to spread the financial burden of potential claims across a large number of participants. When you look at how these rates are structured, they are rarely arbitrary; they are the result of mathematical modeling designed to predict the likelihood of a claim within a specific timeframe.
The rate you pay is essentially the "cost of risk." The insurer—or the administrative body managing the OSGIL fund—calculates the probability of death for a person of your age, gender, and health status, then adds a "loading" fee. This loading covers administrative costs, potential profit margins, and a safety buffer against unexpected fluctuations in mortality rates (such as a pandemic or a sudden change in regional health outcomes).
Key Variables Influencing Premium Costs
Unlike private, highly customized market policies where individual health examinations are often mandatory, group-based insurance programs like OSGIL often utilize a simplified underwriting process. However, the following factors remain central to how your specific rate is determined:
1. Age and Life Expectancy
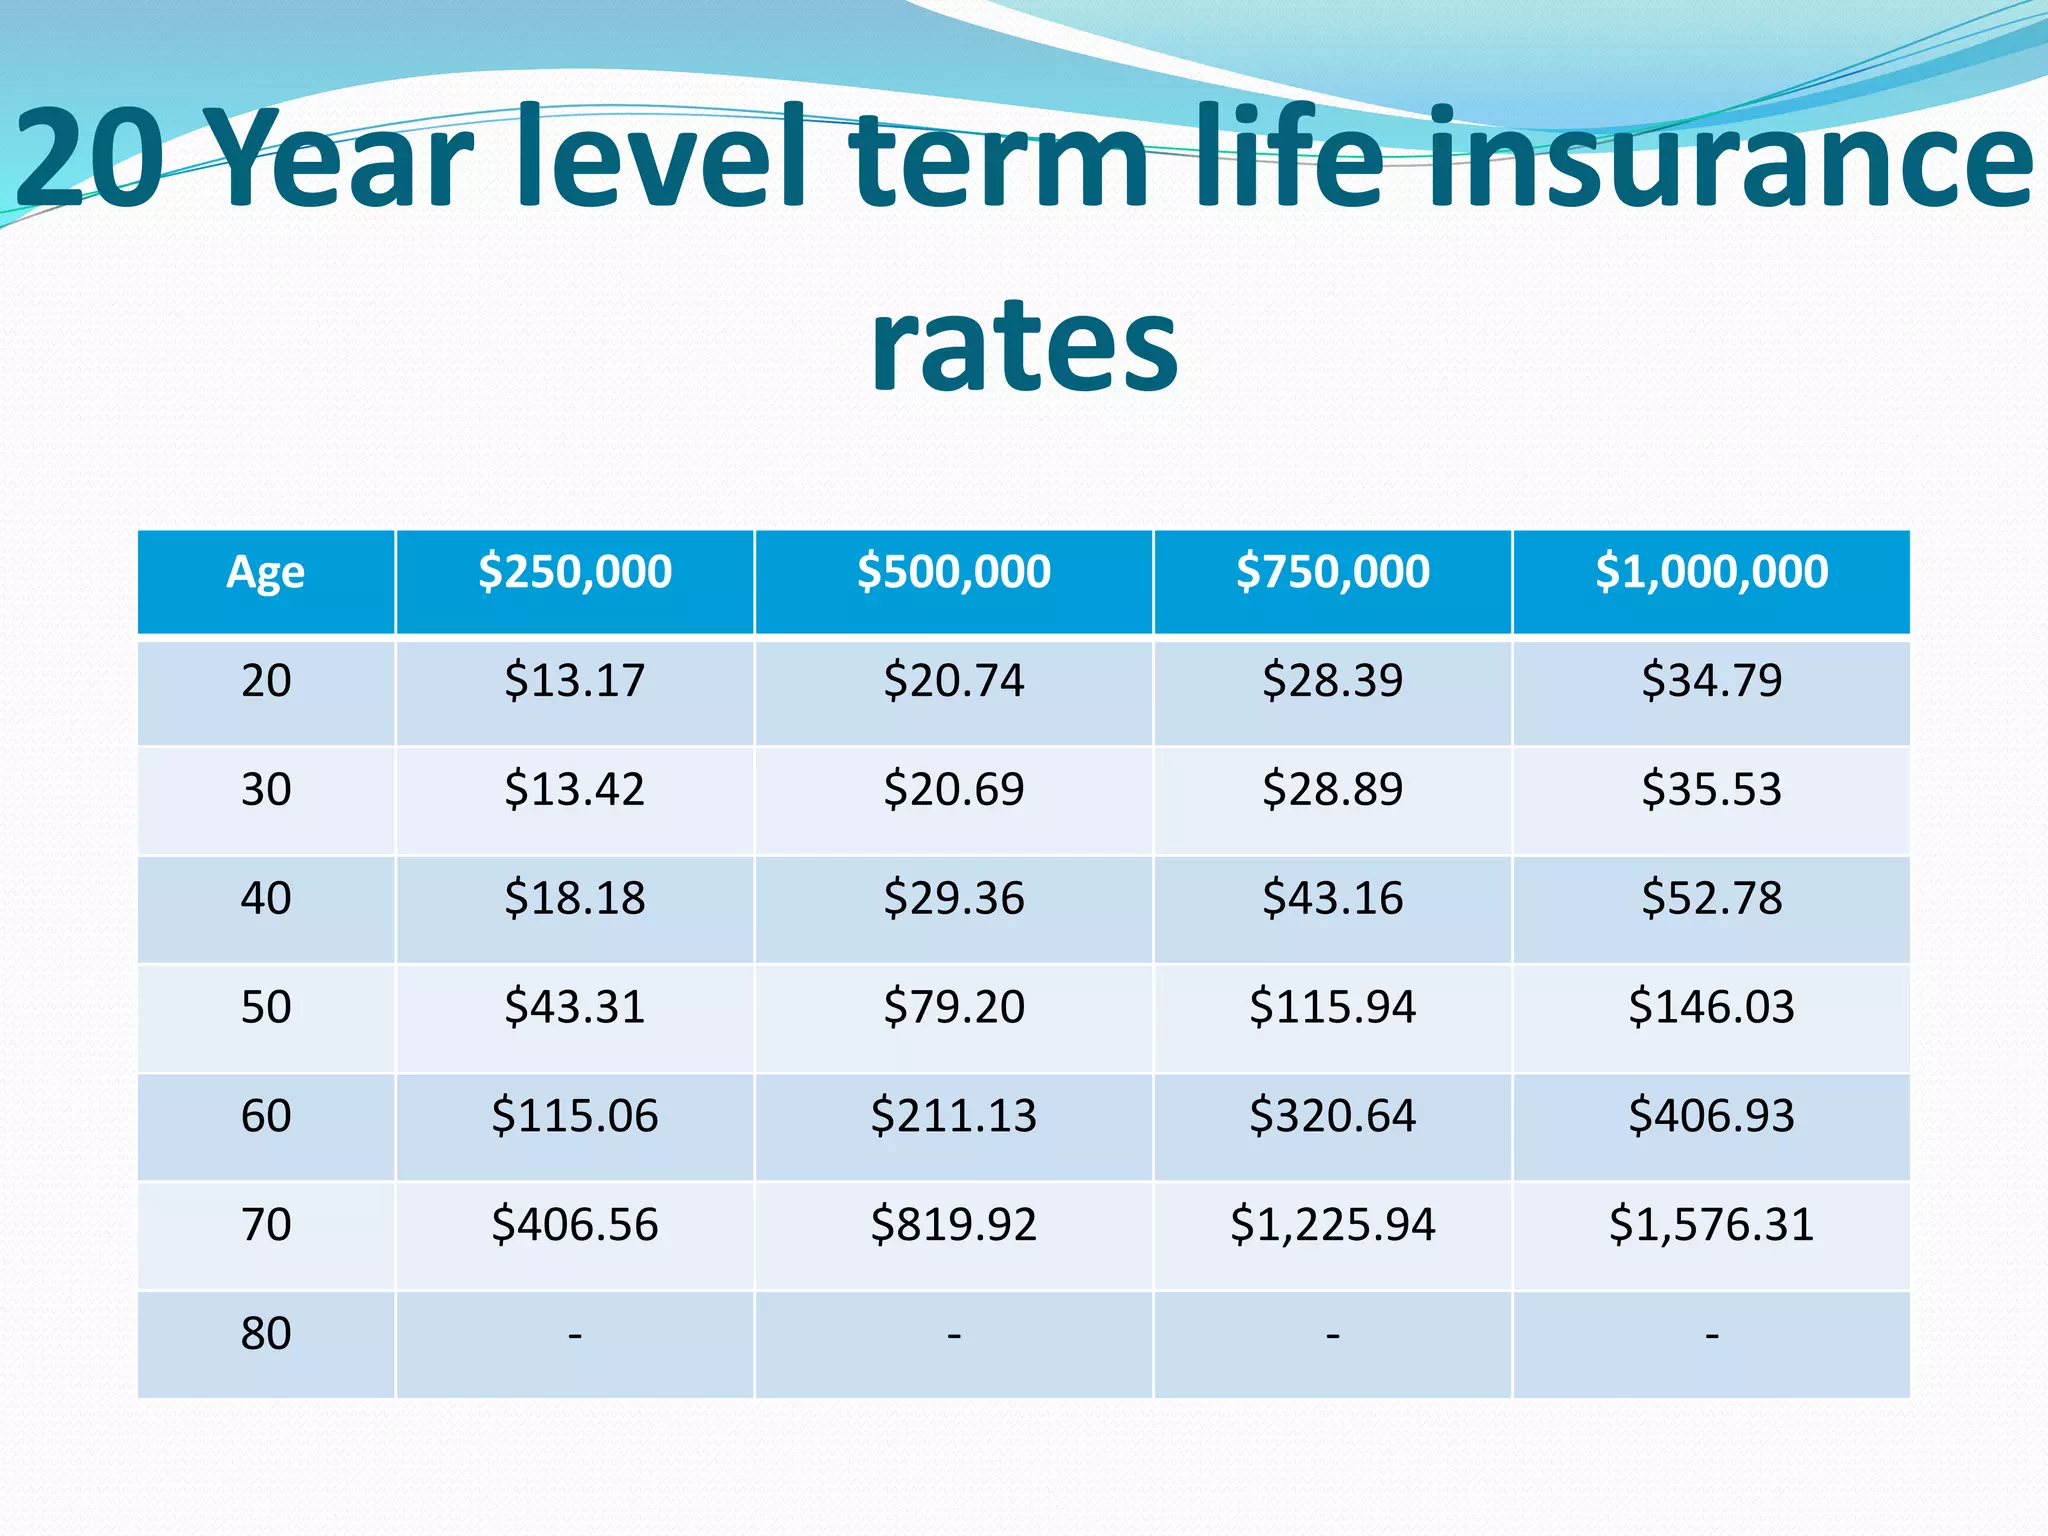
Age is the most significant predictor of mortality. In almost every life insurance model, the premium increases as you age because the statistical probability of a death benefit claim becomes higher. In programs managed by public or quasi-public entities, age bands are often used to group participants into specific premium tiers, preventing the price from changing monthly and instead adjusting it at defined milestones.
2. Occupational Risk Profile
If the insurance policy is tied to a specific employment sector or geographic region, the inherent hazards of that industry play a role. If the workforce is exposed to manual labor, hazardous machinery, or specific environmental stressors, the collective risk profile of the pool is higher. This is often reflected in a "base rate" that is higher than that of low-risk, sedentary office-based insurance pools.
3. Coverage Amount (The Death Benefit)
The face value of the policy, or the total sum paid to beneficiaries upon the death of the insured, is a direct multiplier of the cost. A policy with a higher death benefit requires a higher premium because the insurer is accepting more financial exposure. Most OSGIL structures offer tiered coverage amounts, allowing participants to align their premium contributions with their personal financial needs.
4. Underwriting Standards
Group insurance typically relies on "guaranteed issue" or "simplified issue" underwriting. Because the group itself provides a natural cross-section of health, the insurer does not require an exhaustive medical exam. However, this convenience comes at a cost; the premium is calculated based on the average health of the group, rather than the ideal health of an individual.
Comparing OSGIL Rate Structures
Understanding the distinction between different insurance models helps clarify why your rate might look the way it does. The following table illustrates common rate drivers found in similar government-linked insurance frameworks.
| Factor | Impact on Rate | Rationale |
|---|---|---|
| Age | High | Mortality risk increases naturally with age. |
| Group Participation | Low | Large pools stabilize costs through shared risk. |
| Occupational Hazard | Medium | High-risk sectors require a higher contingency fund. |
| Inflation Adjustment | Moderate | Periodic increases to keep the real value of the benefit stable. |
| Administrative Load | Low | Costs for managing the program are distributed among members. |
The Role of Actuarial Science in 2026
By 2026, the use of predictive analytics in managing life insurance pools has become more sophisticated. Actuaries working with programs like OSGIL utilize historical data—specifically looking at trends in regional mortality and economic stability—to forecast what the premiums need to be to ensure the plan remains solvent.
If the historical data shows that mortality rates in the covered demographic are stable or improving, rates may stay level. Conversely, if medical inflation or changing socio-economic conditions lead to higher claim volumes, the governing body may be forced to initiate a rate adjustment. This is not a penalty to the individual, but a necessary correction to ensure that the insurance fund does not run out of capital before a claim is filed.
Navigating Premium Increases and Policy Updates
It is common for participants to wonder why their premiums might change over time, even if their personal health status remains unchanged. Most insurance frameworks linked to governmental or large-scale institutional organizations are subject to "experience rating." This means that if the group as a whole experiences more claims than were predicted in the previous year, the premium rates for the next cycle may be adjusted upward to cover the shortfall.
Additionally, legislative changes or policy revisions in 2026 might require the inclusion of new benefits or expanded coverage definitions. When a policy is expanded to offer more comprehensive protections, the cost of that expansion is typically passed through to the policyholders via a premium adjustment.
Frequently Asked Questions (FAQ)
1. Does my personal medical history change my OSGIL rate? In most group insurance settings, personal medical history (like pre-existing conditions) does not change your individual rate because the plan is underwritten at the group level. You are generally charged the same rate as other members in your age and job-class bracket.
2. Can I lower my insurance rates within this program? While you cannot change the base rate set by the actuarial rules, you can often lower your total premium cost by reducing the coverage amount (the death benefit). Choosing a lower benefit tier will result in a lower payroll deduction or premium payment.
3. Are these rates fixed for life? No. Rates in programs like OSGIL are typically reviewed periodically—often annually or every few years—to account for inflation, demographic shifts, and the overall financial health of the insurance pool.
4. What happens to my rate if I change jobs or departments? If the insurance is tied to specific occupational risk categories, moving to a different role could change your classification. If you move from a high-risk to a lower-risk category, you might see a decrease in your premiums, depending on the specific administrative rules of the organization.
5. How do I verify if my current rate is accurate? You should review your most recent policy statement provided by the administrative office. Compare your current deduction against the published rate table for your specific coverage tier. If there is a discrepancy, contact the HR or benefits department immediately for a breakdown of your current deductions.
Practical Next Steps for Policyholders
If you are a participant in an OSGIL-related plan, the most effective way to manage your costs and benefits is to perform an annual check-up of your policy.
First, request a summary of benefits that details your current coverage level and the specific premium associated with it. Compare this to your household budget to ensure the coverage remains appropriate for your financial needs. If your salary has increased or your number of dependents has changed, the "standard" amount of coverage you enrolled in years ago may no longer be sufficient.
Second, if you notice an unexpected increase in your premiums, do not assume it is an error. Contact the program administrator to ask if there was a scheduled "experience adjustment" or a cost-of-living increase implemented for the 2026 fiscal year. Understanding the "why" behind the numbers empowers you to make informed decisions about your long-term financial planning.
Finally, keep your beneficiary information updated. Even the best-priced insurance policy provides no value if the administrative records are outdated. Ensuring that the fund is accurately managed is a collaborative effort between the participants and the governing body.
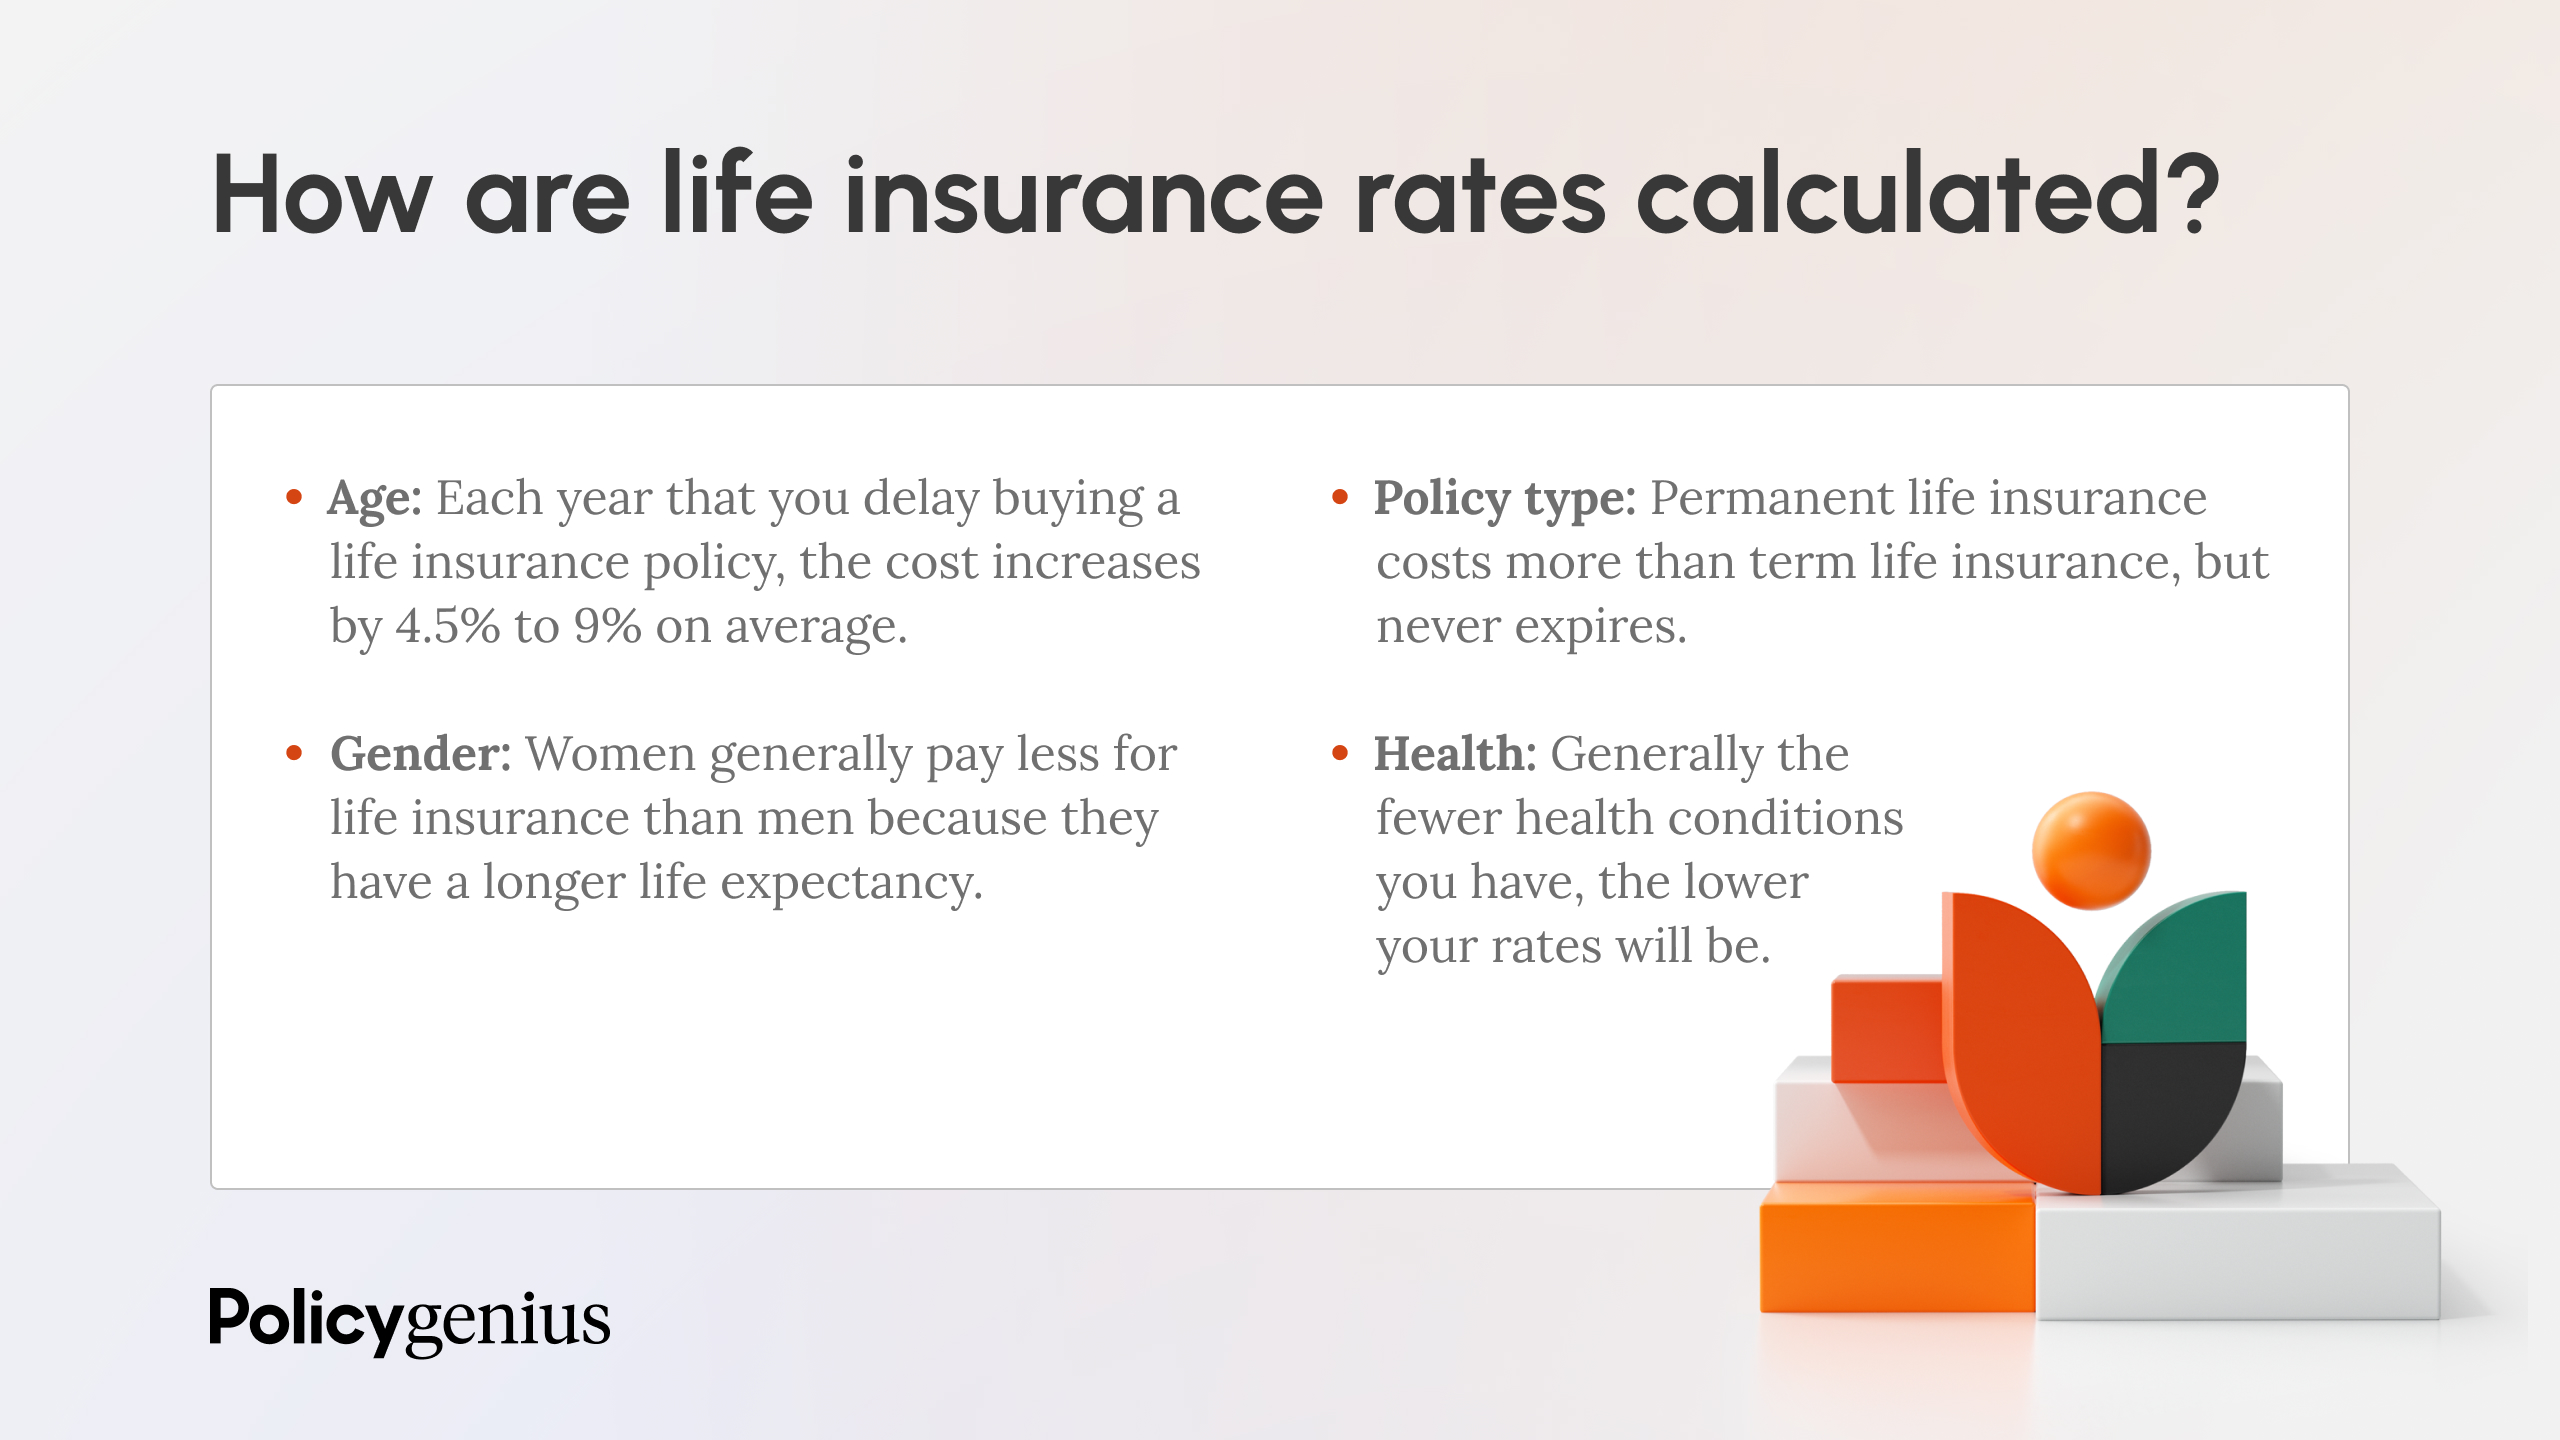
Image Gallery
Select an image to open it in a new tab.

Zara El-Hashem
Sociocultural Dynamics and Academics Writer
