Navigating the Complexities and Challenges of Insurance Auto Recovery
Insurance auto recovery is the multifaceted process by which insurers, third-party recovery specialists, and legal teams locate, secure, repossess, and liquidate or redeploy vehicles tied to insurance claims—ranging from total-loss settlements and salvage title acquisitions to fraudulent disappearances and subrogation disputes. This operational pipeline is fraught with legal hurdles, logistical bottlenecks, technological fragmentation, and severe administrative friction that can substantially diminish net recovery values.
The Landscape of Auto Recovery in Insurance Operations
Auto recovery occupies a critical juncture in the insurance lifecycle. When a vehicle is declared a total loss, stolen, abandoned, or subject to a subrogation claim where fault is contested, the insurer assumes a vested interest in recovering the physical asset or its financial equivalent. However, the path from claim notification to final asset disposition involves navigating a labyrinth of regulatory constraints, physical barriers, and digital disconnects.
Insurers face mounting pressure to accelerate cycle times, reduce loss adjustment expenses (LAE), and maximize salvage returns. Yet, external forces—such as overcrowded towing lots, convoluted state-by-state titling laws, and the rising sophistication of auto theft rings—frequently complicate recovery efforts. Understanding these hurdles requires examining the distinct phases of the recovery lifecycle and the specific systemic failures that undermine efficiency.
Logistical and Physical Bottlenecks in Vehicle Retrieval
The physical retrieval of a vehicle is rarely a straightforward tow-and-store operation. Insurers frequently encounter severe logistical hurdles immediately following an accident, theft recovery, or abandonment notification.
Locating and Accessing Impound Lots
When a vehicle is towed from a collision scene or recovered by municipal law enforcement after a theft, it is typically placed in a private or municipal impound lot. These facilities often operate with limited hours, opaque fee structures, and minimal digital communication infrastructure.
- Impound Fees: Storage fees accumulate rapidly—often ranging from $50 to over $100 per day—plus steep initial towing and administrative charges. If an insurer experiences delays in processing a claim or dispatching a recovery agent, these fees can quickly eclipse the actual wholesale value of the vehicle.
- Access Restrictions: Impound yards frequently impose rigid release requirements, demanding original power of attorney documents, specific release forms, or physical signatures from insured parties who may be hospitalized, uncooperative, or difficult to reach.
Complexities of Remote and Off-Road Locations
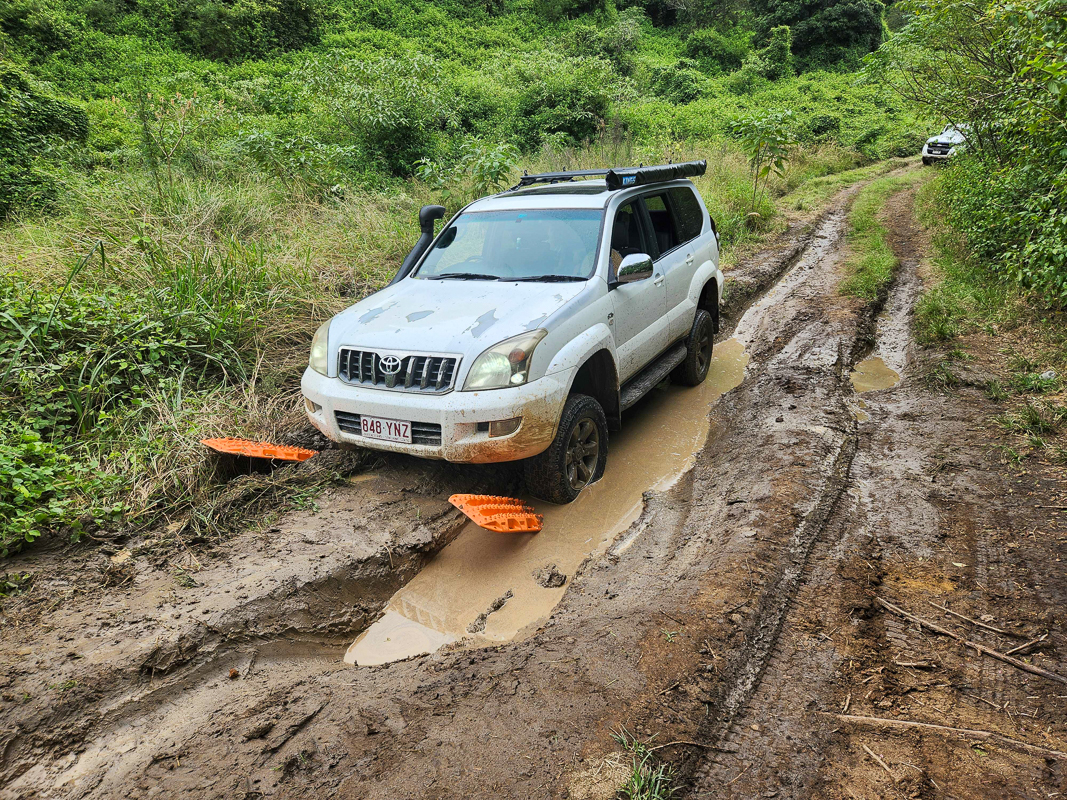
Not all vehicles are recovered neatly on paved roadways. Total losses occurring in remote rural areas, dense forests, or multi-level parking structures require specialized heavy equipment, flatbed transport, or off-road recovery gear. Coordinating these specialized services drives up direct expenses and extends cycle times, increasing the risk of secondary damage or vandalism while the vehicle sits unattended.

Regulatory and Titling Compliance Challenges
Perhaps the most formidable barrier to efficient auto recovery lies in the patchwork of state and federal regulations governing vehicle ownership, salvage branding, and title transfers.
State-Specific Titling Laws
Every jurisdiction maintains its own statutory framework for how and when an insurer can take possession of a title.
- Salvage Branding Thresholds: Different states mandate salvage or non-repairable title branding at vastly different damage thresholds (e.g., a percentage of total loss value or specific structural criteria). An insurer handling multi-state claims must navigate conflicting administrative timelines and documentation mandates.
- Power of Attorney (POA) Hurdles: Securing a signed POA from the vehicle owner is essential for executing title transfers. When owners are unresponsive, disputing fault, or facing financial distress, obtaining this legal instrument can stall salvage sales for weeks or months.
Abandoned Vehicle and Liens Legislation
When dealing with uncollected vehicles or vehicles abandoned at repair facilities, insurers must navigate complex mechanics' liens and abandoned vehicle statutes. Failure to follow statutory notification windows (such as certified mail requirements to registered owners and lienholders) can result in legal liability, wrongful conversion claims, or inability to auction the asset legally.
Subrogation and Liability Disputes
Subrogation occurs when an insurer steps into the shoes of its insured to recover payout costs from a liable third party. In auto recovery, subrogation represents a vital avenue for mitigating net losses, but it is routinely impeded by evidentiary and legal friction.
- Claim Settlement: Insurer pays insured for vehicle loss.
- Investigation: Evidence collected (police reports, telemetry).
- Liability Demand: Formal demand sent to third-party carrier.
- Arbitration/Litigation: Settling disputes over fault percentages.
- Recovery Realized: Funds collected or written off as uncollectible.
Evidentiary Gaps and Accident Reconstruction
Proving liability requires robust evidence, including dashcam footage, accurate police reports, witness statements, and increasingly, telematics data from connected vehicles. When evidence is ambiguous, contradictory, or missing, third-party insurers routinely deny liability or offer low-ball settlements. Pursuing these disputes through inter-company arbitration (such as Arbitration Forums, Inc.) or formal litigation introduces significant legal costs and delays.
Uninsured and Underinsured Motorists
A persistent reality in auto insurance is the high volume of motorists driving without adequate liability coverage. When an at-fault driver lacks insurance or assets, subrogation recovery is virtually impossible, forcing the primary insurer to absorb the loss despite establishing legal liability.
Technological Integration and Data Fragmentation
The modernization of the automotive industry has outpaced the legacy software systems utilized by many insurance carriers and salvage yards, creating severe operational silos.
Disconnected Ecosystems
Insurers often rely on disparate platforms for claims management, salvage bidding, telematics tracking, and legal document management. When these systems fail to communicate in real-time, manual data entry errors occur, status updates are delayed, and vehicles languish in inventory queues. Furthermore, third-party vendors—such as towing operators and salvage auction houses—frequently utilize proprietary software that does not integrate seamlessly with carrier systems.
Telematics and Connected Vehicle Data
Modern connected vehicles generate vast amounts of diagnostic and positional data that can aid recovery and liability assessment. However, extracting, authenticating, and utilizing this data while complying with evolving consumer privacy regulations presents a significant technical hurdle for adjusters and recovery specialists.
Financial and Operational Impact Matrix
To evaluate the operational burden of auto recovery challenges, insurers must examine how specific friction points impact key performance metrics.
| Recovery Challenge | Primary Operational Impact | Financial Consequence | Mitigation Strategy |
|---|---|---|---|
| Impound Lot Storage Fees | Extended cycle times; administrative backlog | Rapid escalation of Loss Adjustment Expenses (LAE) | Automated impound notification and expedited digital dispatch |
| Title Acquisition Delays | Inability to release vehicles to salvage auctions | Depreciated asset value; storage cost accumulation | Proactive digital POA acquisition and standardized state workflows |
| Subrogation Disputes | Prolonged arbitration and legal overhead | Reduced net recovery yield; trapped capital | Early deployment of telematics and AI-driven liability assessment |
| Vendor Fragmentation | Communication silos; manual tracking errors | Increased administrative overhead; lost asset tracking | Integrated API platforms connecting carriers and salvage networks |
Fraud, Theft Recovery, and Organized Crime
Auto recovery operations are increasingly targeted by sophisticated fraud rings and organized crime networks, complicating routine asset retrieval.
Fraudulent Total Losses and Export Rings
Staged accidents, paper-titled vehicles, and intentional vehicle disappearances designed for illegal export present severe challenges for recovery units. Special Investigation Units (SIUs) must pause recovery and liquidation efforts to investigate suspicious claims, during which time physical vehicles may be stripped for parts or shipped across international borders, rendering physical recovery impossible.
Cloning and Identity Theft
Fraudsters frequently utilize vehicle identification number (VIN) cloning to obscure stolen vehicles, complicating the verification duties of recovery agents. If an insurer or recovery agent seizes a cloned vehicle in error, they may face legal complications, wrongful repossession claims, and regulatory scrutiny.
Best Practices for Overcoming Recovery Friction
Mitigating the challenges of insurance auto recovery requires a strategic overhaul of operational workflows, vendor management, and technology adoption.
- Automated Vendor Networks: Partner with centralized digital towing and recovery platforms that provide real-time GPS tracking, automated impound alerts, and pre-negotiated storage fee caps to prevent runaway expenses.
- Early Intervention Protocols: Initiate salvage disposition and title requests concurrently with the initial claim payout evaluation rather than waiting for physical vehicle inspection completion.
- Advanced Data Analytics: Leverage predictive analytics to identify high-probability subrogation claims early, routing them to specialized legal recovery teams before evidence degrades.
- Regulatory Compliance Automation: Implement dynamic compliance software that updates state-specific titling, lien, and abandonment notification rules automatically, minimizing administrative errors.
Frequently Asked Questions
Why do impound storage fees accumulate so quickly during auto recovery?
Impound lots operate on commercial business models where storage is priced at a premium to encourage rapid vehicle removal. When claims involve disputed liability, missing titles, or uncooperative owners, vehicles remain stranded in these yards, causing daily fees to compound rapidly and occasionally surpass the salvage value of the automobile.
How do state titling laws complicate insurance auto recovery?
Each state enforces unique thresholds for branding titles as salvage or non-repairable, alongside varying requirements for power of attorney and lienholder releases. Insurers operating across multiple states must navigate disparate administrative procedures, which frequently delays the legal transfer of ownership needed to sell recovered vehicles at auction.
What is the role of subrogation in auto recovery?
Subrogation is the process where an insurance company pursues a liable third party to recover financial payouts made to its own insured. In auto recovery, successful subrogation helps offset claim costs and reduce premium pressures, though it is often hindered by contested liability, missing accident evidence, or uninsured at-fault parties.
How can insurers reduce cycle times for total-loss vehicle recovery?
Insurers can reduce cycle times by automating vendor dispatch, integrating real-time tracking for towed vehicles, initiating digital power-of-attorney requests early in the claims process, and establishing direct digital communication channels with salvage auction houses and impound facilities.
Conclusion and Strategic Next Actions
The challenges of insurance auto recovery demand a proactive, technology-driven approach that addresses logistical bottlenecks, regulatory hurdles, and operational fragmentation simultaneously. Insurers and recovery professionals must audit their current vendor relationships, modernize their digital infrastructure to eliminate data silos, and implement early-stage title and subrogation workflows. By treating asset recovery as an integrated, end-to-end operational pipeline rather than an isolated back-office task, organizations can systematically reduce cycle times, control loss adjustment expenses, and maximize net financial recovery.
Image Gallery
Select an image to open it in a new tab.


Akira Tanaka
International Academic Trends Correspondent
