Delaris M. Barclay Irrevocable Trust and Stranger-Originated Life Insurance: Understanding Risks and Regulatory Frameworks

The intersection of the Delaris M. Barclay Irrevocable Trust and the complex mechanisms of stranger-originated life insurance (STOLI) involves high-stakes estate planning and insurance regulation. At its core, this subject centers on whether specific trust structures were utilized to circumvent insurable interest laws, which require that the policy owner or beneficiary have a financial stake in the continued life of the insured.
The Foundation of Irrevocable Trusts in Estate Planning
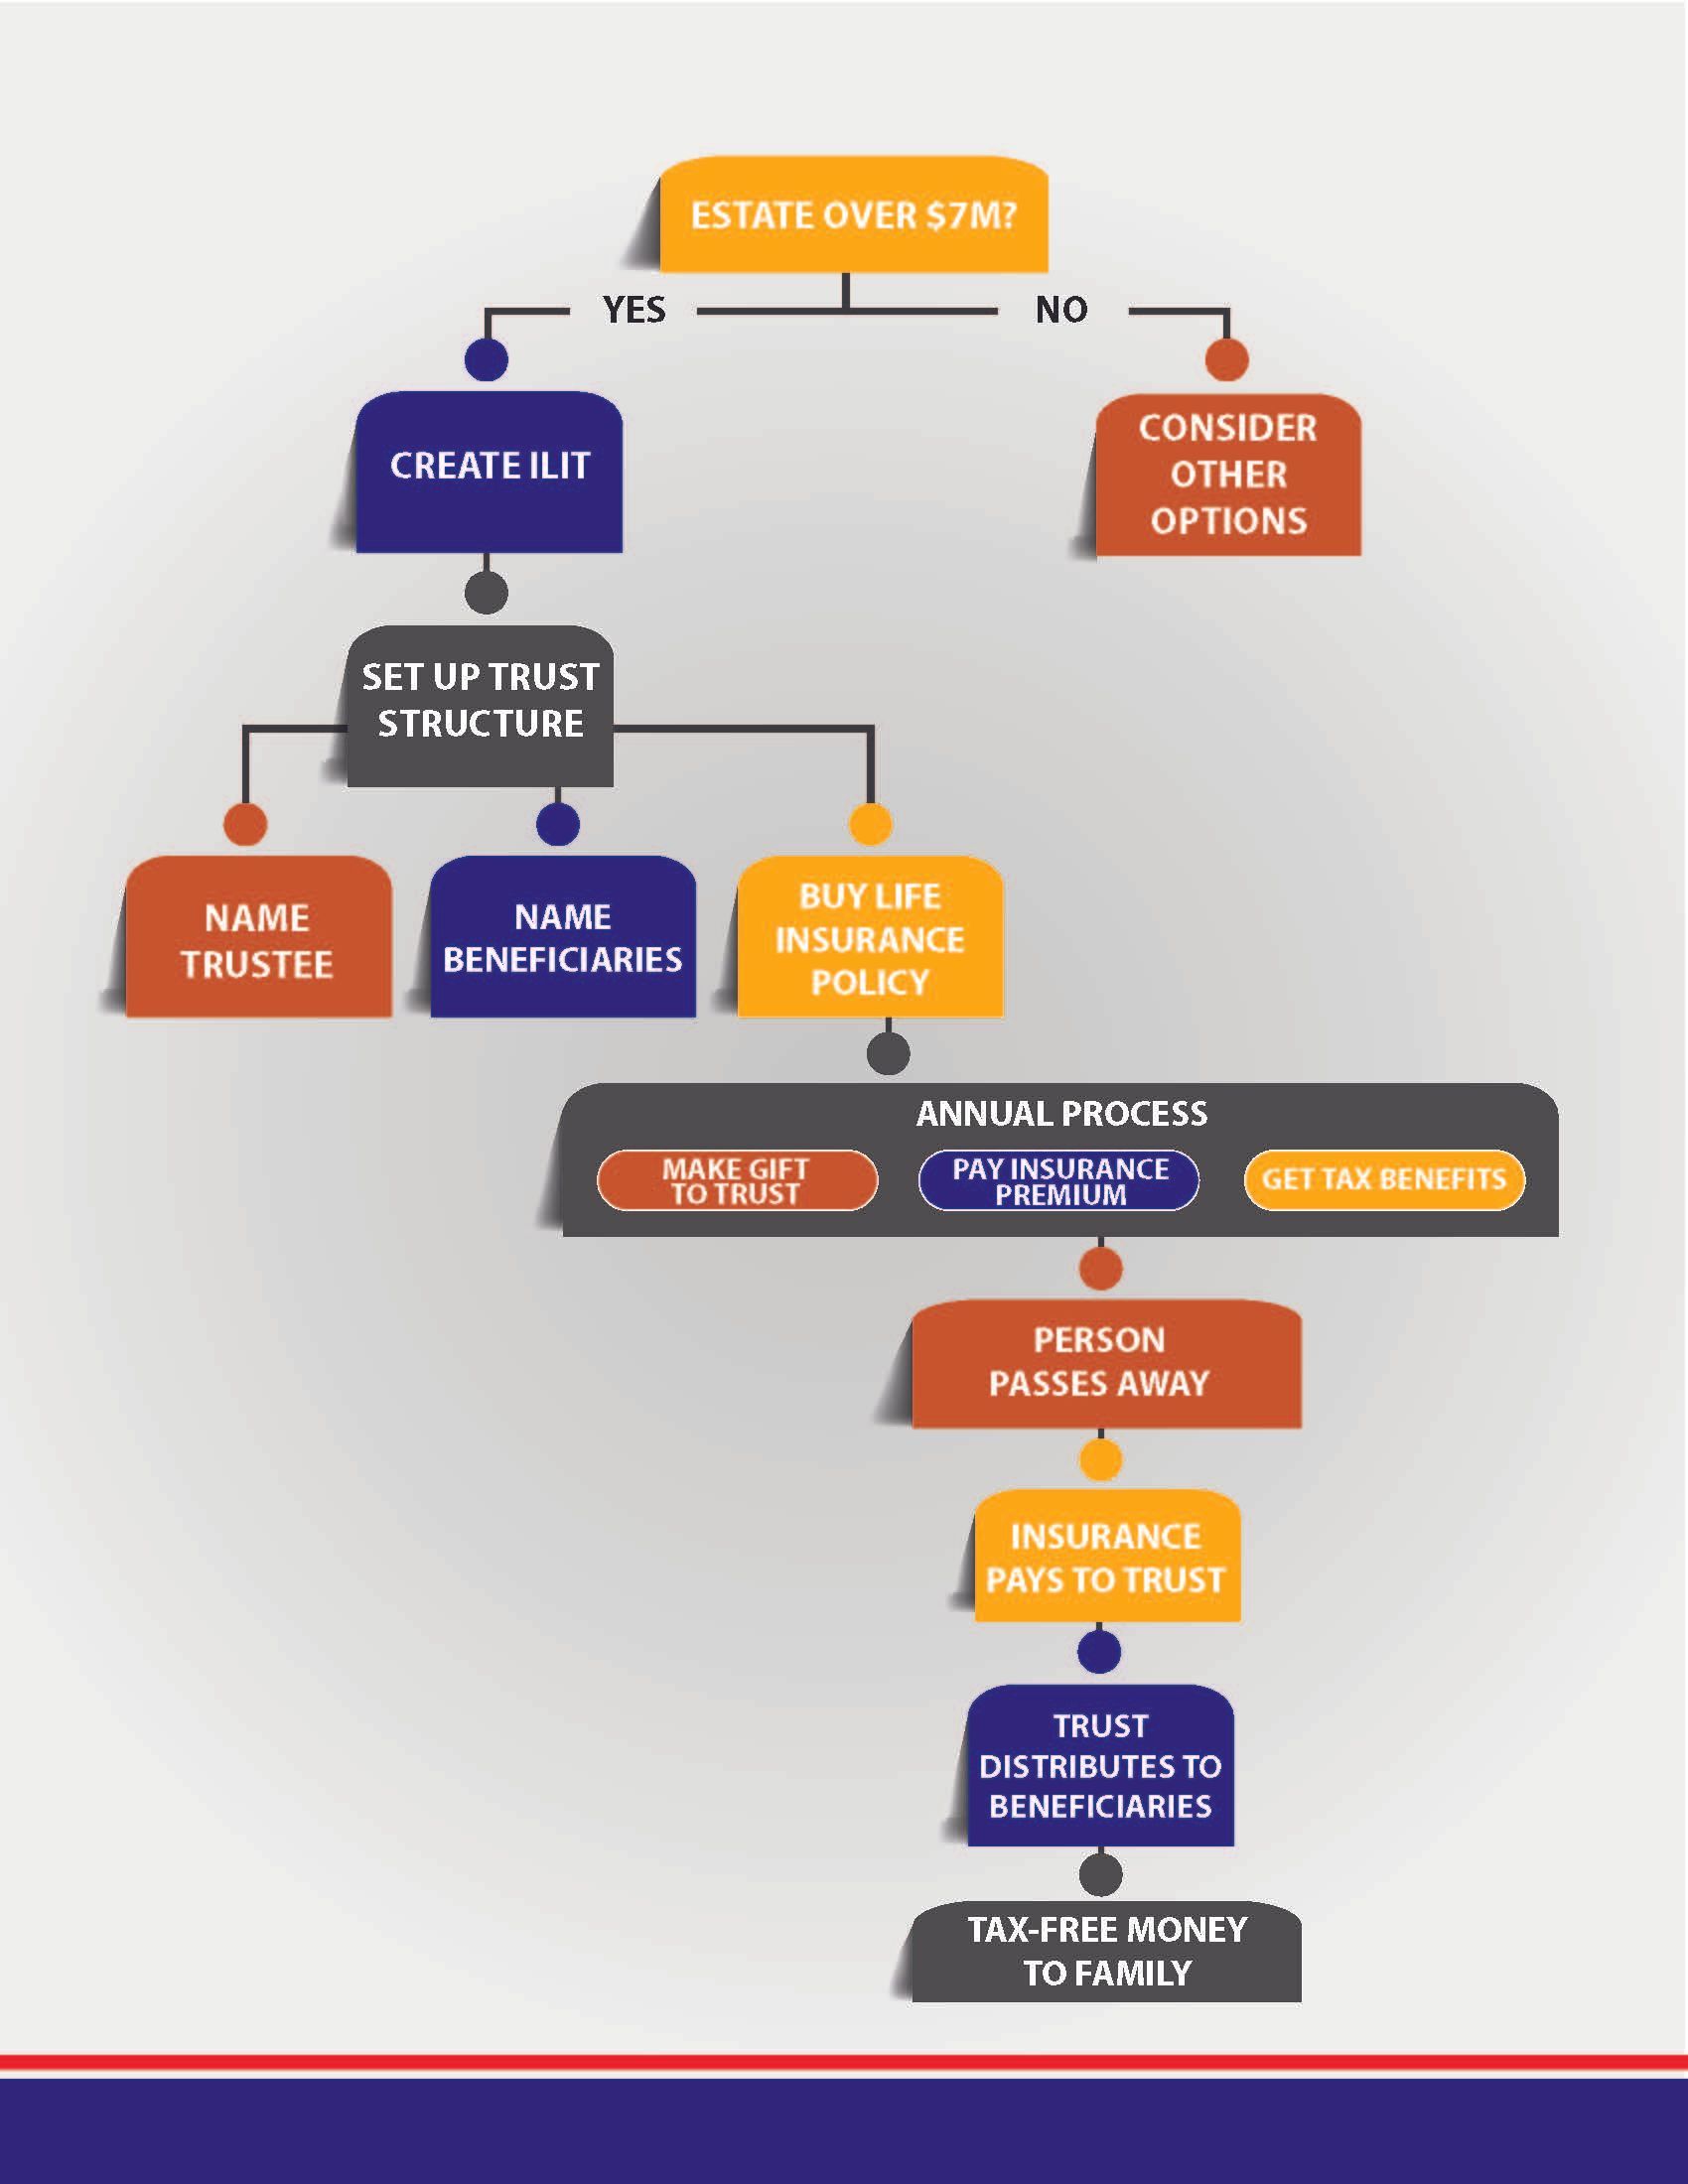
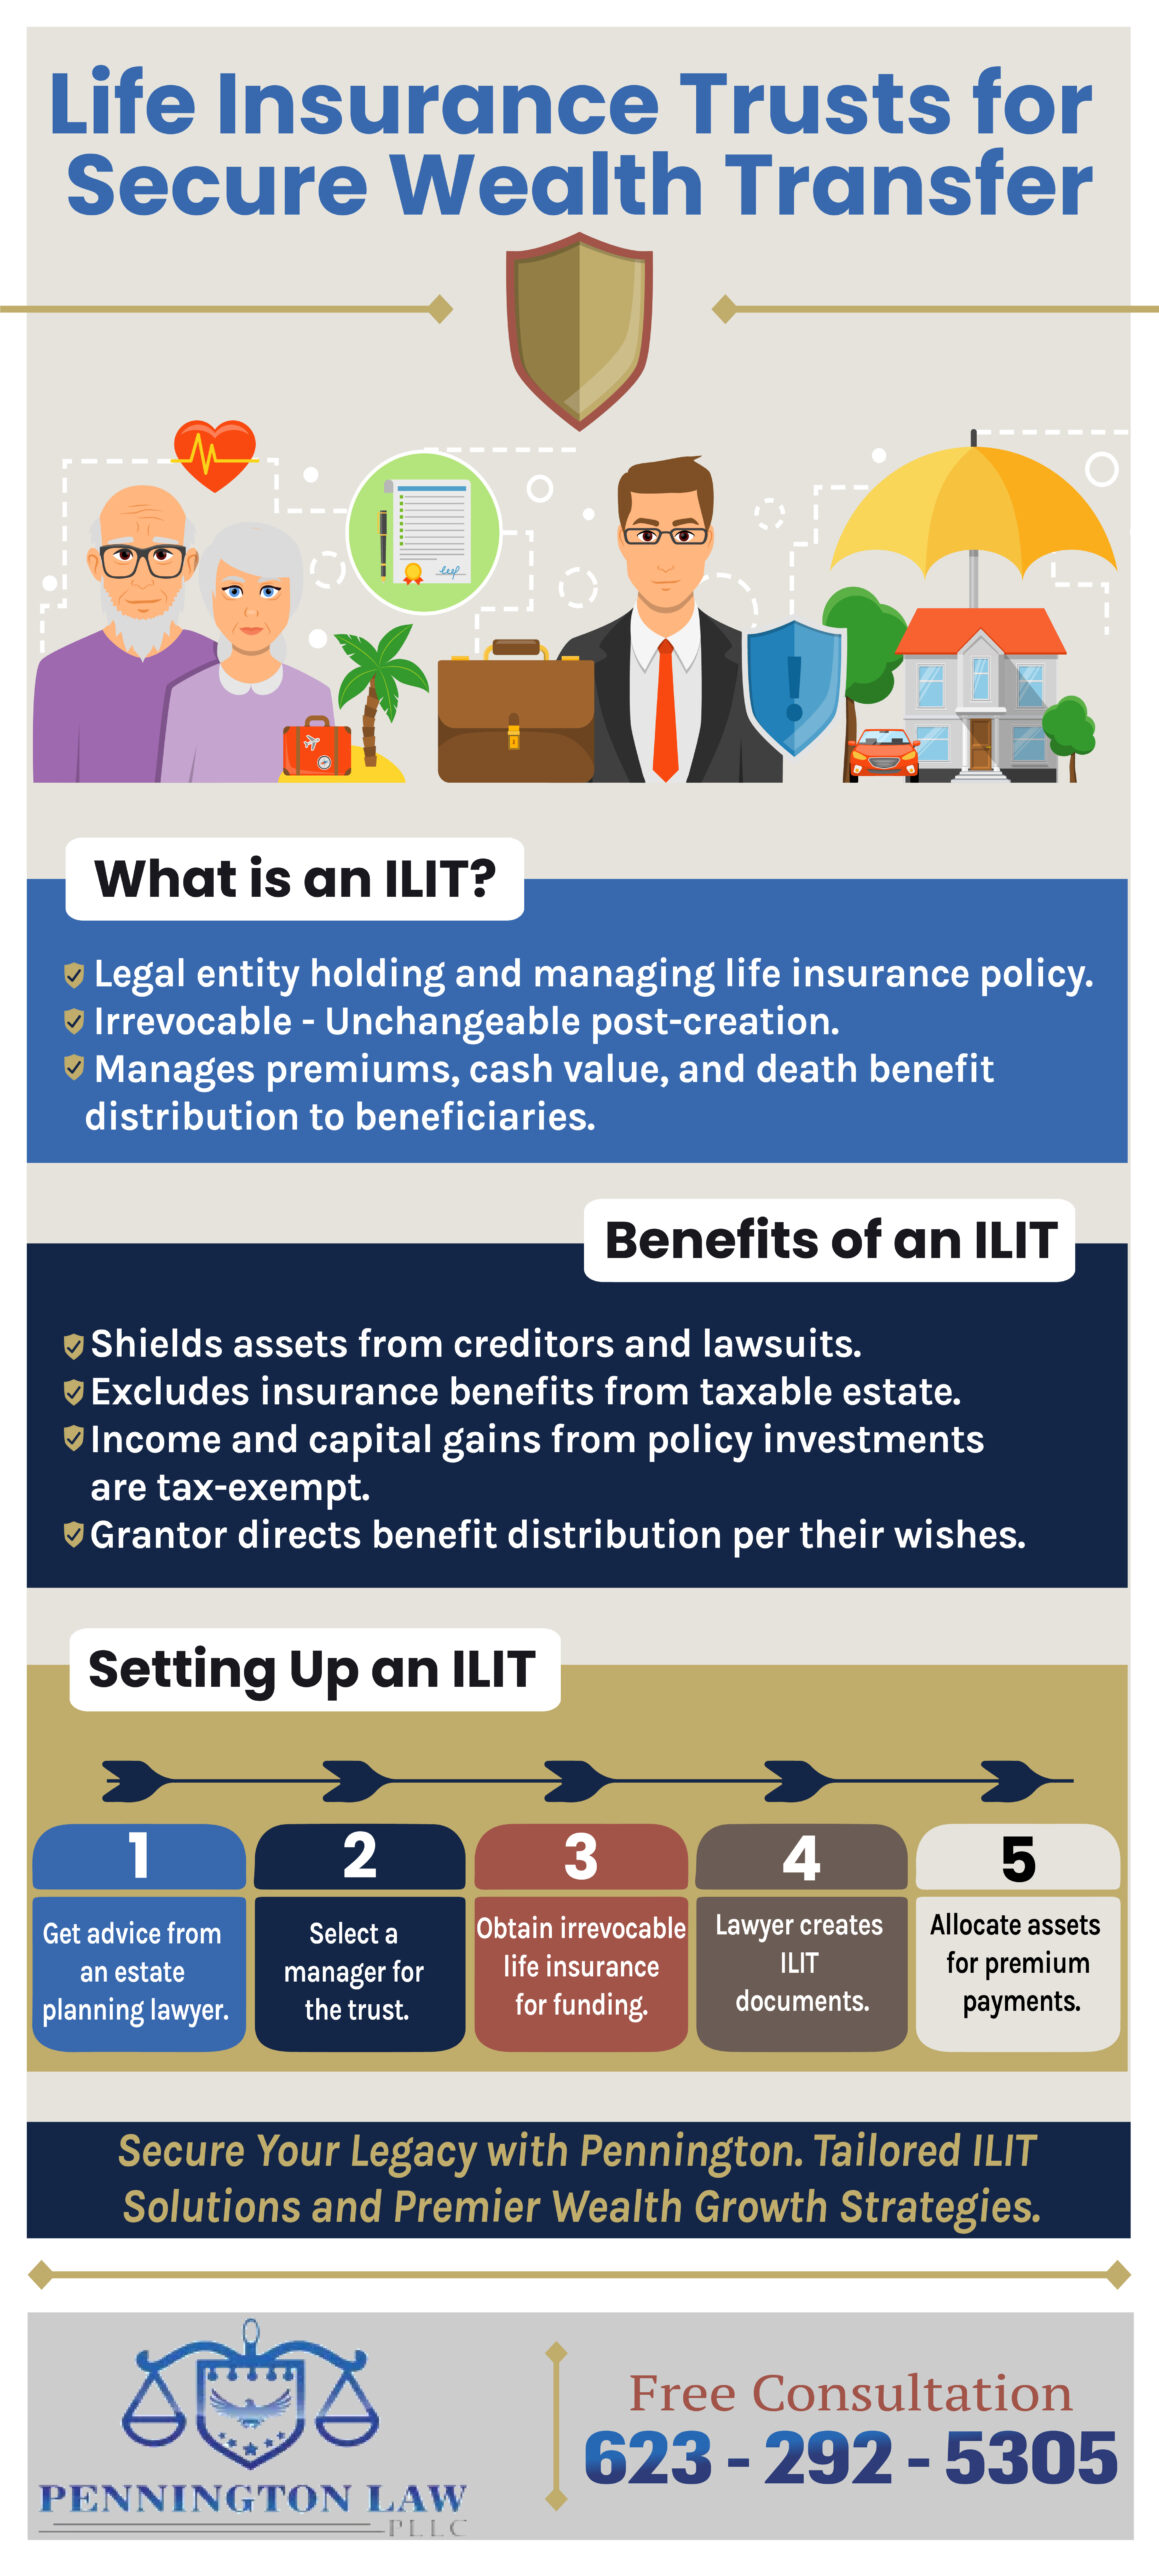
An irrevocable trust is a sophisticated legal instrument used to remove assets from a grantor’s taxable estate. Once assets are transferred into the trust—such as cash, securities, or life insurance policies—the grantor generally relinquishes control over them. In standard estate planning, an Irrevocable Life Insurance Trust (ILIT) is a common tool designed to hold a life insurance policy, ensuring that death benefits are excluded from the insured’s gross estate for federal estate tax purposes.
The integrity of such a trust relies on its adherence to fiduciary standards and the specific intent for which it was created. When a trust is established—such as the Delaris M. Barclay Irrevocable Trust—the document must clearly outline the powers of the trustee and the rights of the beneficiaries. Problems arise not from the existence of the trust itself, but when the trust is repurposed as a conduit for arrangements that fall under the category of stranger-originated life insurance.
Defining Stranger-Originated Life Insurance (STOLI)
Stranger-originated life insurance, often referred to as investor-owned life insurance, occurs when an investor induces an individual to take out a large life insurance policy with the intent of transferring the policy to the investor once the contestability period expires. In these arrangements, the investor typically pays the premiums, and the insured receives an upfront payment or a share of the death benefit.
The legal and ethical vulnerability of these arrangements lies in the requirement of "insurable interest." Insurance laws require that the party purchasing the policy—or the beneficiary—must stand to suffer a financial loss upon the death of the insured. If there is no such interest, the policy is essentially a wagering contract, which is generally unenforceable under public policy.
Identifying Risk Factors in Trust-Based Insurance Structures
When an irrevocable trust is involved in what might be characterized as a STOLI scheme, several red flags often appear. Financial advisors and legal professionals look for specific patterns that distinguish a legitimate estate planning vehicle from a predatory arrangement:
- Premium Financing Without Proven Net Worth: If a trust enters into a premium financing arrangement where the loan is non-recourse, and the lender is also a beneficiary or the source of the funds, it suggests the trust is being used as a pass-through for investors.
- The Disconnect Between Coverage and Need: A legitimate ILIT is usually funded to provide liquidity for estate taxes or family support. If the face value of the policy significantly exceeds the needs of the beneficiaries or the estate, it indicates a speculative motive.
- Rapid Transfer of Beneficial Interests: If the beneficiaries of the trust are changed shortly after the policy is issued, or if an investor is appointed as a successor trustee, it may indicate a transfer of the policy's economic benefit to a third party.
Regulatory and Legal Challenges
The regulatory landscape regarding STOLI has evolved significantly over the past two decades. Most states have enacted specific legislation that voids policies deemed to lack an insurable interest at the inception of the contract. Courts have frequently ruled that even if the policy is held within a trust, the underlying purpose of the transaction can be scrutinized to determine if it violates state insurance codes.
For trustees managing a trust like the Delaris M. Barclay Irrevocable Trust, the legal duty is to ensure the assets remain protected. If a trustee participates in an arrangement that is later determined to be a prohibited STOLI transaction, they may face allegations of breach of fiduciary duty. This can lead to the invalidation of the policy by the insurance carrier, resulting in the loss of both the premium investments and the anticipated death benefit.
Comparing Legitimate ILITs vs. Speculative Arrangements
To understand how these arrangements are viewed, it is helpful to contrast the intent and structure of a traditional ILIT with that of a STOLI-exposed trust.
| Feature | Legitimate ILIT | STOLI-Exposed Trust |
|---|---|---|
| Primary Goal | Estate liquidity and tax mitigation | Speculative investment return |
| Funding Source | Personal wealth or gifting | Investor-provided non-recourse loans |
| Beneficiaries | Family members and heirs | Third-party investors |
| Insurable Interest | Clear and inherent | Non-existent or fabricated |
| Regulatory Standing | Protected by standard tax law | Frequently voids contract at death |
Navigating Compliance and Due Diligence
For beneficiaries or successor trustees dealing with an existing trust, the process of verifying the legitimacy of the insurance assets is paramount. This typically requires a forensic audit of the policy’s origination documents.
- Review the Application History: Determine if the premium payments were made by the grantor, the trust, or an outside entity. Any direct payment from an outside investor is a major indicator of non-compliance.
- Audit the Loan Documentation: If the trust utilized premium financing, review the terms of the loan. Loans that are non-recourse and provided by entities linked to life settlement firms are high-risk.
- Evaluate Professional Roles: Identify if the individuals involved in setting up the trust had historical links to firms that specialize in life settlements rather than estate planning.
- Consult Legal Counsel: Given the jurisdictional variations in insurance law, obtain an opinion from an attorney specializing in trust litigation and insurance regulation to assess the risk of the policy being challenged by the carrier.
Common Misconceptions
There is often confusion between "Life Settlements" and "STOLI." A life settlement is a legitimate secondary market transaction where an existing policy—originally purchased for valid personal or business reasons—is sold by the owner to a third party. STOLI, conversely, is predatory at the point of sale. The distinction is in the intent at inception. If a trust was created specifically to initiate a policy for the purpose of selling it to an investor, it is a STOLI arrangement. If a policy was held for several years for estate planning and the owner decides to sell it due to changing financial circumstances, it is generally considered a life settlement.
Frequently Asked Questions
What happens if an insurance company voids a policy due to STOLI? If a policy is found to be a wagering contract lacking insurable interest, the carrier may rescind the policy. This usually means the return of premiums paid, but the death benefit is forfeited, rendering the trust’s primary asset worthless.
Can a trust be rehabilitated if it was used in a STOLI arrangement? Rehabilitation is difficult. Once the insurable interest violation is established, the contract is often void from its inception. If the trust has other assets, it may be possible to settle with the carrier, but the insurance policy itself is rarely salvageable.
Why are non-recourse loans considered a red flag? A non-recourse loan in this context means the lender cannot go after the borrower’s other assets if the loan is not repaid. In a STOLI scheme, the only collateral is the policy. This structure allows investors to profit if the insured dies early while incurring no personal risk if they do not.
How do regulators discover these arrangements? Carriers often perform "incontestability audits" and death claim reviews. If the pattern of premium payments or the financial status of the applicant at the time of purchase appears inconsistent with the coverage amount, the carrier will investigate the true source of the premiums and the involvement of outside parties.
Next Steps for Stakeholders
If you are a trustee or beneficiary associated with the Delaris M. Barclay Irrevocable Trust, your immediate priority should be the preservation of evidence. Gather all correspondence related to the original purchase of any insurance policies, the source of initial premium payments, and the identity of any third-party lenders. Do not attempt to modify the trust or surrender the policy without obtaining professional legal counsel, as these actions could be misinterpreted or inadvertently trigger a challenge from an insurance carrier. Engaging a forensic accountant or a legal expert in life insurance regulation is the most prudent step to determine the trust’s standing and mitigate potential liabilities.

Image Gallery
Select an image to open it in a new tab.




Mateo Castillo
Decentralized Finance and E-Payments Strategist
