How to Appeal Auto Insurance Claims Effectively
Appealing an auto insurance claim requires a systematic approach involving the collection of contradictory evidence, a formal written dispute, and a clear understanding of your policy’s specific coverage limits. To succeed, you must move beyond subjective frustration and provide the insurer with verified technical or documentary proof that their initial assessment was based on inaccurate information or an incomplete review of the facts.
Understanding the Claims Denial Process
When an insurance carrier denies a claim or offers a settlement lower than the estimated repair costs, they typically issue a "denial of coverage" or an "explanation of benefits." This document is your most important starting point. It outlines the specific policy provision, exclusion, or factual interpretation the adjuster used to reach their decision.
Before initiating an appeal, you must distinguish between a denial based on coverage and a denial based on valuation. A coverage denial implies the policy does not pay for the specific type of damage sustained, while a valuation dispute involves a disagreement over the cost of repairs or the market value of a totaled vehicle. Identifying which of these categories your claim falls into will dictate the tone and technical requirements of your appeal letter.
Essential Documentation for Your Appeal
Evidence is the foundation of any successful appeal. Insurance companies rely on standardized estimating software—such as CCC Intelligent Solutions or Mitchell International—to determine repair costs. If your repair facility is quoting higher prices, the discrepancy often lies in the labor hours, parts procurement, or the inclusion of necessary diagnostic steps that the insurer omitted.
To build an effective counter-argument, gather the following:
- The Original Denial Letter: This identifies the specific rationale for the company's decision.
- Independent Estimates: Obtain at least two written quotes from reputable repair shops that use OEM (Original Equipment Manufacturer) parts versus the insurer’s preferred aftermarket parts.
- Photographic and Video Evidence: High-resolution imagery of the damage, taken from multiple angles, that directly contradicts the adjuster’s assessment.
- Vehicle Maintenance Records: If the insurer is questioning the pre-accident condition or "wear and tear" of the vehicle, service receipts can prove the vehicle was well-maintained.
- Police Reports: If the dispute concerns liability, the official crash report serves as the baseline, though it is not always legally binding in insurance arbitration.
Step-by-Step Guide to Filing an Internal Appeal
Every insurer has a formal internal review process. Skipping this step often results in the premature dismissal of your case.
- Contact Your Adjuster: Before sending a formal letter, speak with the assigned adjuster. Occasionally, a mistake in data entry is the cause of a denial. Ask them to explain exactly what documentation is missing that could change their decision.
- Draft a Formal Dispute Letter: Address your appeal to the insurance company's "Claims Appeals Department." Reference your claim number, the date of the incident, and the specific reason for your disagreement. Keep the tone professional, objective, and evidence-based. Avoid emotional language, as it does not influence the technical guidelines the company follows.
- Include a Comparison Table: Summarize the differences between the insurance company’s assessment and your independent findings to make the data easy for the supervisor to digest.
- Request a Peer Review: Explicitly ask for the decision to be reviewed by a senior adjuster or a claims supervisor who was not involved in the initial decision.
- Maintain a Communication Log: Record the name of every representative you speak with, the date, time, and a summary of the conversation.
Comparing Methods of Dispute Resolution
| Method | Best For | Pros | Cons |
|---|---|---|---|
| Internal Appeal | Coverage disputes, minor valuation errors | Free, maintains business relationship | Time-consuming, company bias |
| Appraisal Clause | Valuation of total loss/high repair costs | Independent, binding, professional | Can be expensive to hire your own appraiser |
| State Insurance Commissioner | Unfair claims practices, bad faith | External oversight, regulatory pressure | Does not guarantee a payout, slow |
| Legal Action | Severe bodily injury, denied liability | Finality, potential for damages | High legal fees, protracted litigation |
When to Utilize the Appraisal Clause
Most standard auto insurance policies contain an "Appraisal Clause." If you and your insurer cannot agree on the amount of loss, either party can demand an appraisal. Under this process, you hire an independent appraiser, and the insurance company hires their own. If those two appraisers cannot agree, they hire an "umpire." The agreement of any two of these three parties becomes binding. While this is a powerful tool for resolving disputes over the value of a totaled car, be aware that you will be responsible for the cost of your chosen appraiser and half of the umpire’s fee.
Escalating to Regulatory Bodies
If the internal appeal process fails and you believe the insurance company is acting in bad faith—such as intentionally misinterpreting policy language or ignoring documented evidence—you may file a complaint with your state’s Department of Insurance (DOI).
In 2026, most state DOI portals offer online submission forms. When filing a complaint, ensure you include copies of all correspondence between you and the insurer. The DOI will not necessarily force the insurer to pay your claim, but they will mandate that the insurer responds to your specific complaints. This often triggers a secondary, more thorough review by the company’s legal or compliance department, which may result in a reversal of their previous decision.
Common Mistakes to Avoid
- Accepting Preliminary Payments: If you accept a check marked as "full and final settlement," you may be legally barring yourself from further appeals. If you dispute the amount, do not cash the check until you have clarified with your agent that doing so will not close the claim.
- Missing Filing Deadlines: Insurance policies carry "statutes of limitations" for filing proofs of loss or appeals. Check your policy documents for these time windows, as missing them can lead to an automatic denial.
- Ignoring Policy Exclusions: Review your policy for "exclusions" (e.g., standard wear and tear, mechanical breakdown, or non-covered drivers). Appealing an item that is explicitly excluded by the contract language is rarely successful and wastes resources.
Frequently Asked Questions
Can I appeal a claim if the insurance company has already sent a check? Yes, but you must be extremely cautious. Do not deposit a check if it is described as a "final settlement" unless you are certain you agree with the amount. If you have already deposited it, you may still be able to request a "supplemental claim" if you discover further damage that was not apparent during the initial inspection.
What is the "Appraisal Clause" and how do I trigger it? It is a formal provision in most policies that allows for a third-party resolution for valuation disputes. To trigger it, you must send a formal, written request to your insurance company via certified mail, stating that you wish to invoke the appraisal clause and identifying your chosen appraiser.
How long do insurance companies have to respond to an appeal? State regulations vary, but most jurisdictions require an acknowledgment of a complaint within 10–15 business days. Your specific policy or state’s "Unfair Claims Settlement Practices Act" will define the legally mandated response times.
Is it worth hiring a public adjuster for an auto claim? Public adjusters are more common in property claims. For auto insurance, they are less common because the total value of the claim is often not high enough to justify their fee, which is usually a percentage of the final recovery. Consult one only if the dispute involves a high-value, exotic, or collectible vehicle.
What constitutes "bad faith" in insurance? Bad faith occurs when an insurer fails to conduct a reasonable investigation, ignores evidence that supports your claim, or misrepresents policy provisions to avoid payment. This is a legal standard; if you suspect bad faith, you should consult with a consumer protection attorney rather than attempting to handle it through standard appeals.
Recommended Next Actions
If your claim has been denied, your immediate next step is to request a formal written explanation from the adjuster if one has not already been provided. Without that document, you cannot formulate a targeted rebuttal. Once received, review your policy contract—specifically the definitions and exclusions sections—to ensure your argument is grounded in the language of the agreement. If the claim value is significant, document every interaction meticulously and prepare a summary package of your evidence before requesting an escalation to a supervisor.
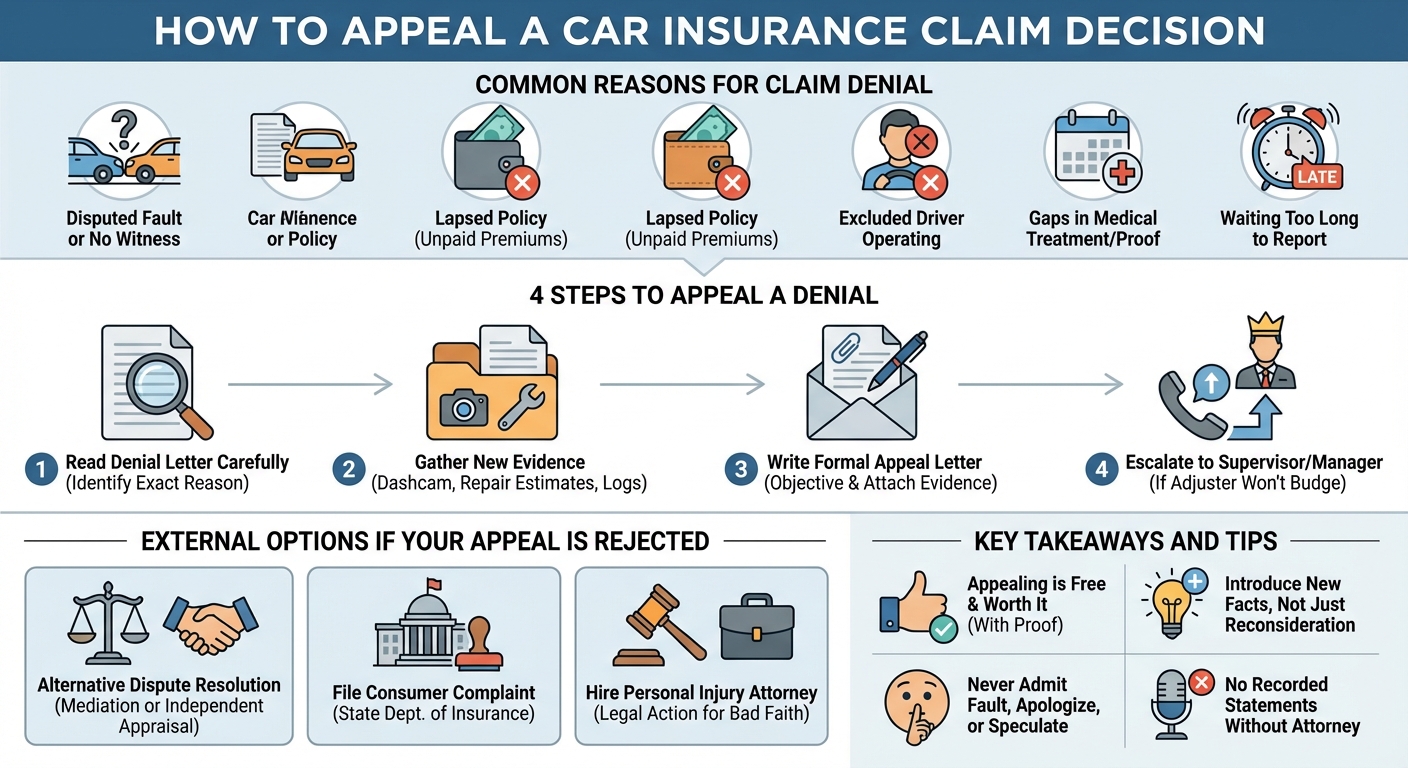
Image Gallery
Select an image to open it in a new tab.
Zara El-Hashem
Sociocultural Dynamics and Academics Writer
