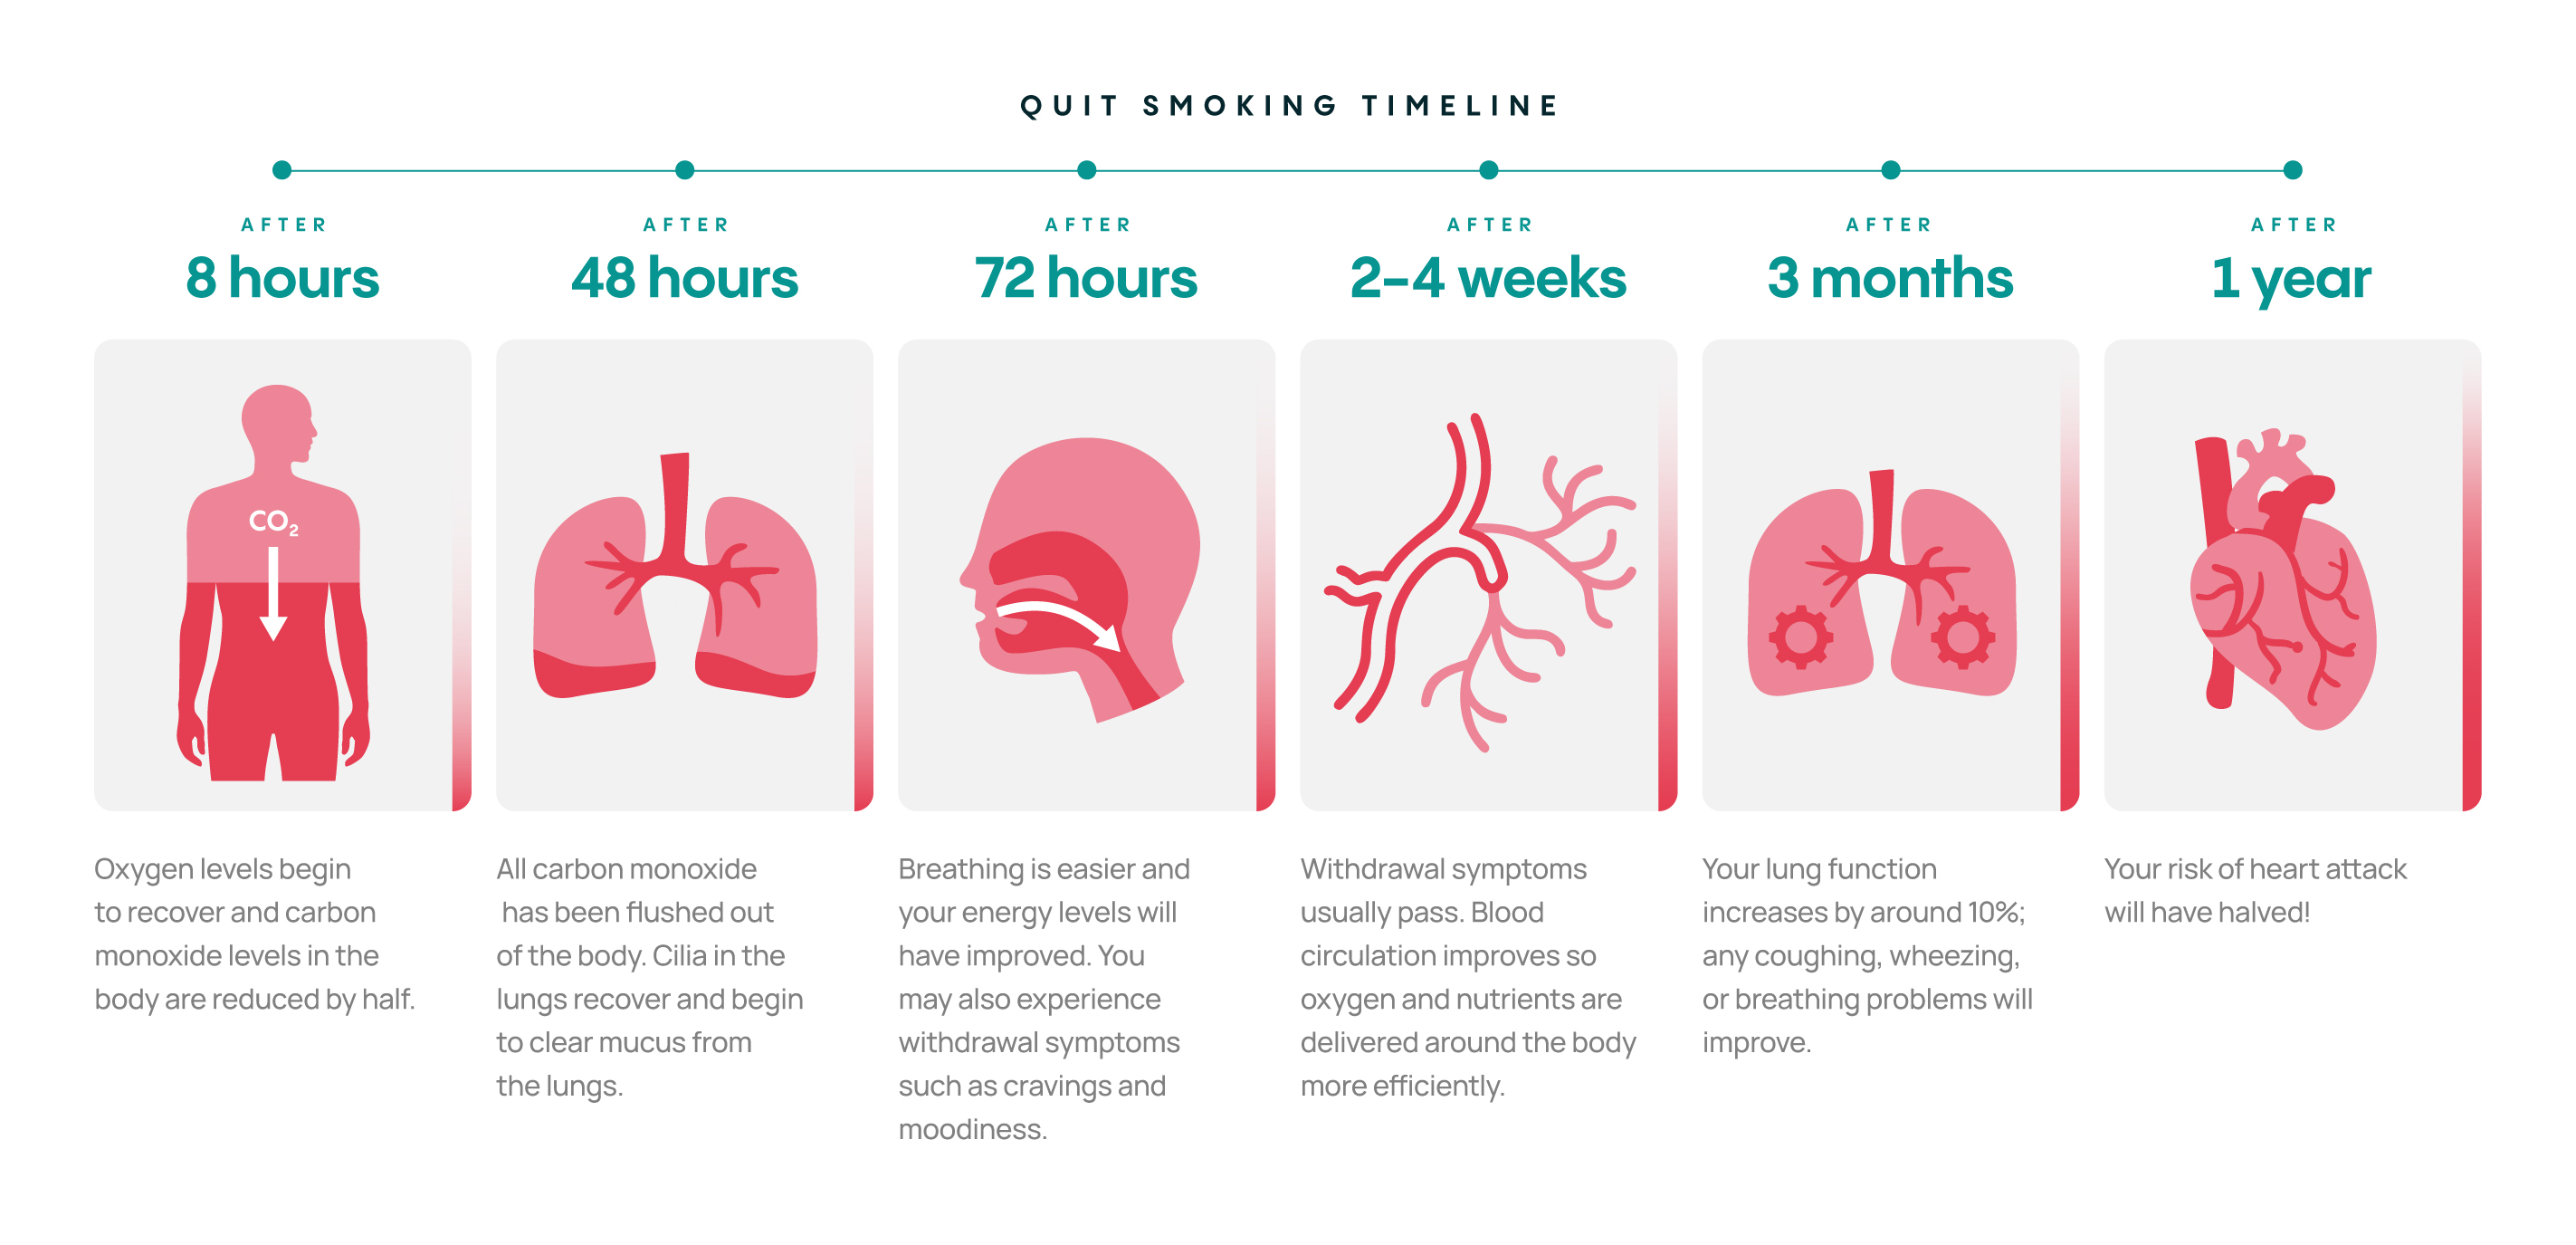
When applying for life insurance after quitting smoking, most major insurance carriers require you to be completely tobacco-free for at least one to two years to qualify for standard non-smoker rates. However, the exact timeline and classification depend heavily on the type of nicotine product used, the frequency of use, and the results of your medical examination.
Understanding Underwriting Classifications for Tobacco Users
Life insurance underwriting is a risk-assessment process. Insurance companies analyze mortality tables to determine how likely a policyholder is to pass away during the term of the policy. Because cigarette smoking and the use of other tobacco products significantly increase the risk of developing chronic illnesses—such as cardiovascular disease, chronic obstructive pulmonary disease (COPD), and various forms of cancer—underwriters place tobacco users into specialized, high-cost rate classes.
When you transition from a smoker to a non-smoker, you are essentially asking the insurance company to re-evaluate your statistical risk profile. To secure the most affordable life insurance rates—often categorized as Preferred Best, Preferred, or Standard Non-Smoker—carriers must verify that your body is entirely free of nicotine and that you have established a sustained pattern of cessation.
Insurance carriers do not just look at whether you smoke traditional cigarettes. They evaluate all nicotine delivery mechanisms under distinct underwriting guidelines. Understanding how different products affect your application timeline is the first step toward securing an affordable policy.
Traditional Cigarettes, Cigars, and Pipes
Cigarette smokers face the strictest underwriting rules in the industry. While a few niche companies might offer standard non-smoker rates after 12 months of complete cessation, the vast majority of top-tier life insurance providers require a full two-year (24 months) clean period before they will grant their best non-smoker health classes.
Cigar and pipe smokers sometimes encounter slightly more flexible guidelines, provided their usage is infrequent (e.g., an occasional celebratory cigar). If you only smoke one or two cigars a month and can pass a cotinine test, some carriers may classify you as a non-smoker immediately, though they will often require you to sign an occasional-use tobacco rider or questionnaire. Daily cigar or pipe smoking, however, is typically treated the same as cigarette smoking.
E-Cigarettes, Vapes, and Nicotine Replacement Therapy
A common misconception among applicants is that electronic cigarettes, vape pens, nicotine patches, and nicotine gums are exempt from tobacco underwriting rules. In reality, life insurance underwriters view nicotine as nicotine, regardless of how it enters your body.
If you currently use e-cigarettes or nicotine replacement therapy (NRT), you will almost always be classified as a smoker for life insurance purposes. To qualify for non-smoker rates while using cessation aids, you must complete your NRT regimen, cease all vaping, and wait out the mandatory 12-to-24-month verification window. Using patches or gums during the underwriting process will trigger a positive nicotine test, resulting in smoker rates.
---\n
The Nicotine Detection Window vs. Underwriting Waiting Periods
It is crucial to distinguish between chemical detection windows and insurance underwriting waiting periods. Many applicants assume that if they can pass a standard drug test, they are immediately eligible for non-smoker life insurance rates. This is a costly misunderstanding.
- Cotinine Detection Window: Cotinine is a primary metabolite of nicotine that stays in your system for a relatively short time. In routine medical exams, cotinine can typically be detected in urine for up to 4 days, in blood for up to 2 days, in saliva for up to 4 days, and in hair follicles for up to 90 days.
- Underwriting Waiting Period: Even if your body is completely free of cotinine after a week of quitting, life insurance companies enforce a retrospective waiting period—usually 12 to 24 months. This requirement guards against "temporary quitting," where an applicant stops smoking just long enough to pass the medical exam before resuming the habit.
| Metric / Test Type | Biological Detection Window | Underwriting Waiting Requirement |
|---|---|---|
| Urine / Saliva Test | 2 to 4 days | N/A (Tests current status only) |
| Blood Test | 1 to 2 days | N/A (Tests current status only) |
| Hair Follicle Test | Up to 90 days | N/A (Rarely used, but available) |
| Standard Non-Smoker Rate | N/A | Minimum 12 to 24 months |
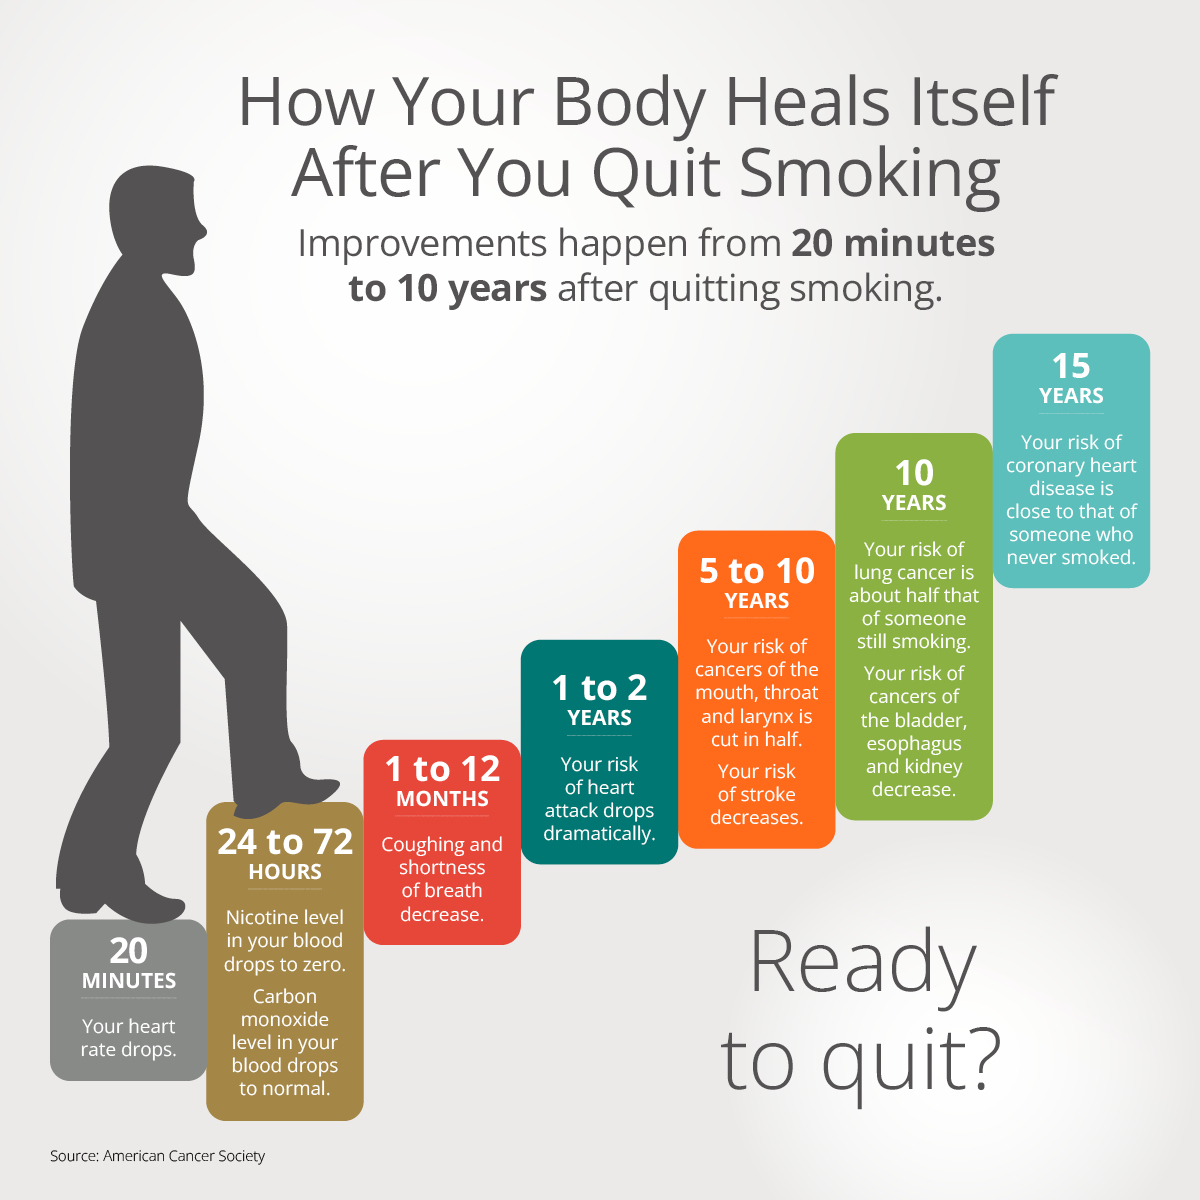
What Happens During the Medical Exam and Lab Screening?
When you apply for life insurance, the carrier will almost always require a paramedical exam, which is paid for by the insurance company. A licensed medical professional will visit your home or office to record your height, weight, blood pressure, and pulse, and to collect blood and urine samples.
The laboratory analysis is comprehensive and looks specifically for cotinine. Because cotinine is processed through the liver and excreted via the kidneys, urine and blood panels easily reveal whether nicotine has been consumed recently.
- False Positives and Environmental Exposure: Non-smokers occasionally worry about failing a cotinine test due to secondhand smoke. While heavy secondhand smoke exposure can occasionally elevate cotinine levels slightly, it rarely reaches the threshold required to trigger a positive result on a standard life insurance cutoff test.
- Consumable Products: Certain foods, such as tomatoes, potatoes, eggplants, and cauliflowers, contain trace amounts of nicotine, but not enough to register as a positive cotinine result on an insurance screening.
- Consequences of a Positive Test: If you state on your application that you have been smoke-free for two years, but the lab detects cotinine in your blood or urine, the application will be flagged for misrepresentation. The carrier will either automatically re-rate your policy into the expensive smoker category or decline the application outright.
---\n
Interim Options: Getting Coverage While You Wait
Waiting one to two years to secure life insurance can leave your family unprotected during a vulnerable window. Fortunately, you do not have to wait until you reach non-smoker status to purchase a policy. You have several strategic options to bridge the gap:
1. Purchase a Policy Now at Smoker Rates, Then Re-Apply Later
The most prudent financial strategy for many recent quitters is to buy a term life insurance policy immediately at smoker rates. While your premiums will be higher than desired, locking in coverage protects your family today against unexpected tragedies. Once you have successfully crossed the 12- or 24-month milestone, you can contact your insurer or shop the open market for a new policy at lower non-smoker rates, then cancel your old policy.
2. Opt for Convertible Term Life Insurance
When shopping for interim coverage, look specifically for a convertible term life insurance policy. This feature allows you to convert your term policy into a permanent life insurance policy (such as whole life or universal life) at a later date without undergoing a new medical exam. While this does not automatically drop your rates to non-smoker status by itself, it ensures that you cannot be denied coverage or rated up further if your health declines while you are waiting out your smoke-free timeline.
3. Consider Guaranteed Issue or Simplified Issue Policies
If you need immediate coverage and want to avoid medical exams entirely, simplified issue or guaranteed issue policies are available. However, these policies typically offer lower face values (often capped at $25,000 to $50,000) and come with higher premium costs because the insurer assumes a higher risk without the benefit of medical records. They are generally used as a last resort if health issues compound your smoking history.
---\n
Steps to Successfully Transition to Non-Smoker Life Insurance Rates
Navigating the application process after quitting smoking requires careful timing and documentation. Follow this structured roadmap to ensure you secure the best possible rates:
- Verify Your Exact Quit Date: Underwriters require precision. Write down the exact month, day, and year of your last cigarette or nicotine use. Inconsistencies between your application and your medical records will cause delays.
- Consult an Independent Insurance Broker: Do not rely on a captive agent who represents only one insurance company. An independent broker can shop across dozens of carriers to find the ones with the most lenient underwriting guidelines for former smokers (for example, companies that grant non-smoker rates at 12 months rather than 24 months).
- Review Your Medical Records: Ensure that your primary care physician has documented your smoking cessation in your medical chart. Underwriters frequently request attending physician statements (APS) during the underwriting review to verify your health history.
- Schedule the Paramedical Exam Only When Confident: Do not schedule your exam until you are entirely certain that you can pass the cotinine screening. If you experience a relapse, postpone the application process until you have re-established a clean timeline.
- Maintain Good General Health: Smoking cessation often triggers lifestyle changes such as weight gain. Underwriters evaluate your build (height-to-weight ratio), cholesterol levels, and blood pressure alongside your smoking status. Keep these metrics optimized to secure a top-tier health class.
---\n
Frequently Asked Questions
Can I get non-smoker life insurance rates if I only smoke cigars occasionally?
Some life insurance carriers offer non-smoker rates to occasional cigar smokers, but criteria are strict. You typically must smoke no more than one to 12 cigars per year, disclose the usage honestly on your application, and test negative for cotinine during your medical exam. If you smoke cigars weekly, you will be classified as a tobacco user.
Do nicotine patches or e-cigarettes count as smoking for life insurance?
Yes. Life insurance underwriters test for the presence of nicotine and its metabolite, cotinine, in your body. Whether you get nicotine from a cigarette, a vape, a patch, or a piece of gum, the chemical result is the same. You must be completely free of all nicotine products for the required 12-to-24-month waiting period to qualify for non-smoker rates.
What happens if I relapse after getting a non-smoker life insurance policy?
Once your life insurance policy is successfully issued and in force, your rates are locked in for the duration of the term (in the case of level-term insurance). If you relapse and start smoking again a year into your policy, the insurance company cannot retroactively raise your rates or cancel your coverage based on that relapse, provided you answered the application questions truthfully at the time of purchase.
Can my life insurance rates drop automatically after I quit smoking?
Generally, no. Your insurance rates are bound to the health classification assigned when the policy was originally underwritten. To lower your premiums after quitting, you will typically need to complete a new application, undergo a fresh medical exam, and satisfy the carrier's 12-to-24-month waiting period.
Are marijuana smokers classified the same as tobacco smokers?
Not necessarily. Many modern life insurance carriers view marijuana use much more leniently than tobacco use. Depending on the frequency of use and the state where you reside, occasional or even regular marijuana users can sometimes qualify for standard non-smoker rates, provided they do not mix cannabis with tobacco.
---\n
Next Actions for Applicants
If you have recently quit smoking and want to secure life insurance, your immediate next step is to evaluate your timeline against the 12-to-24-month industry standard. If you have been smoke-free for less than a year, consult with an independent insurance broker to compare the cost of buying an interim term policy now versus waiting for lower rates. Gather your medical records, verify your exact quit date, and choose a policy structure that protects your financial dependents while you complete your smoke-free journey.
Image Gallery
Select an image to open it in a new tab.
Simon Caldwell
Enterprise Technology and Systems Editor
