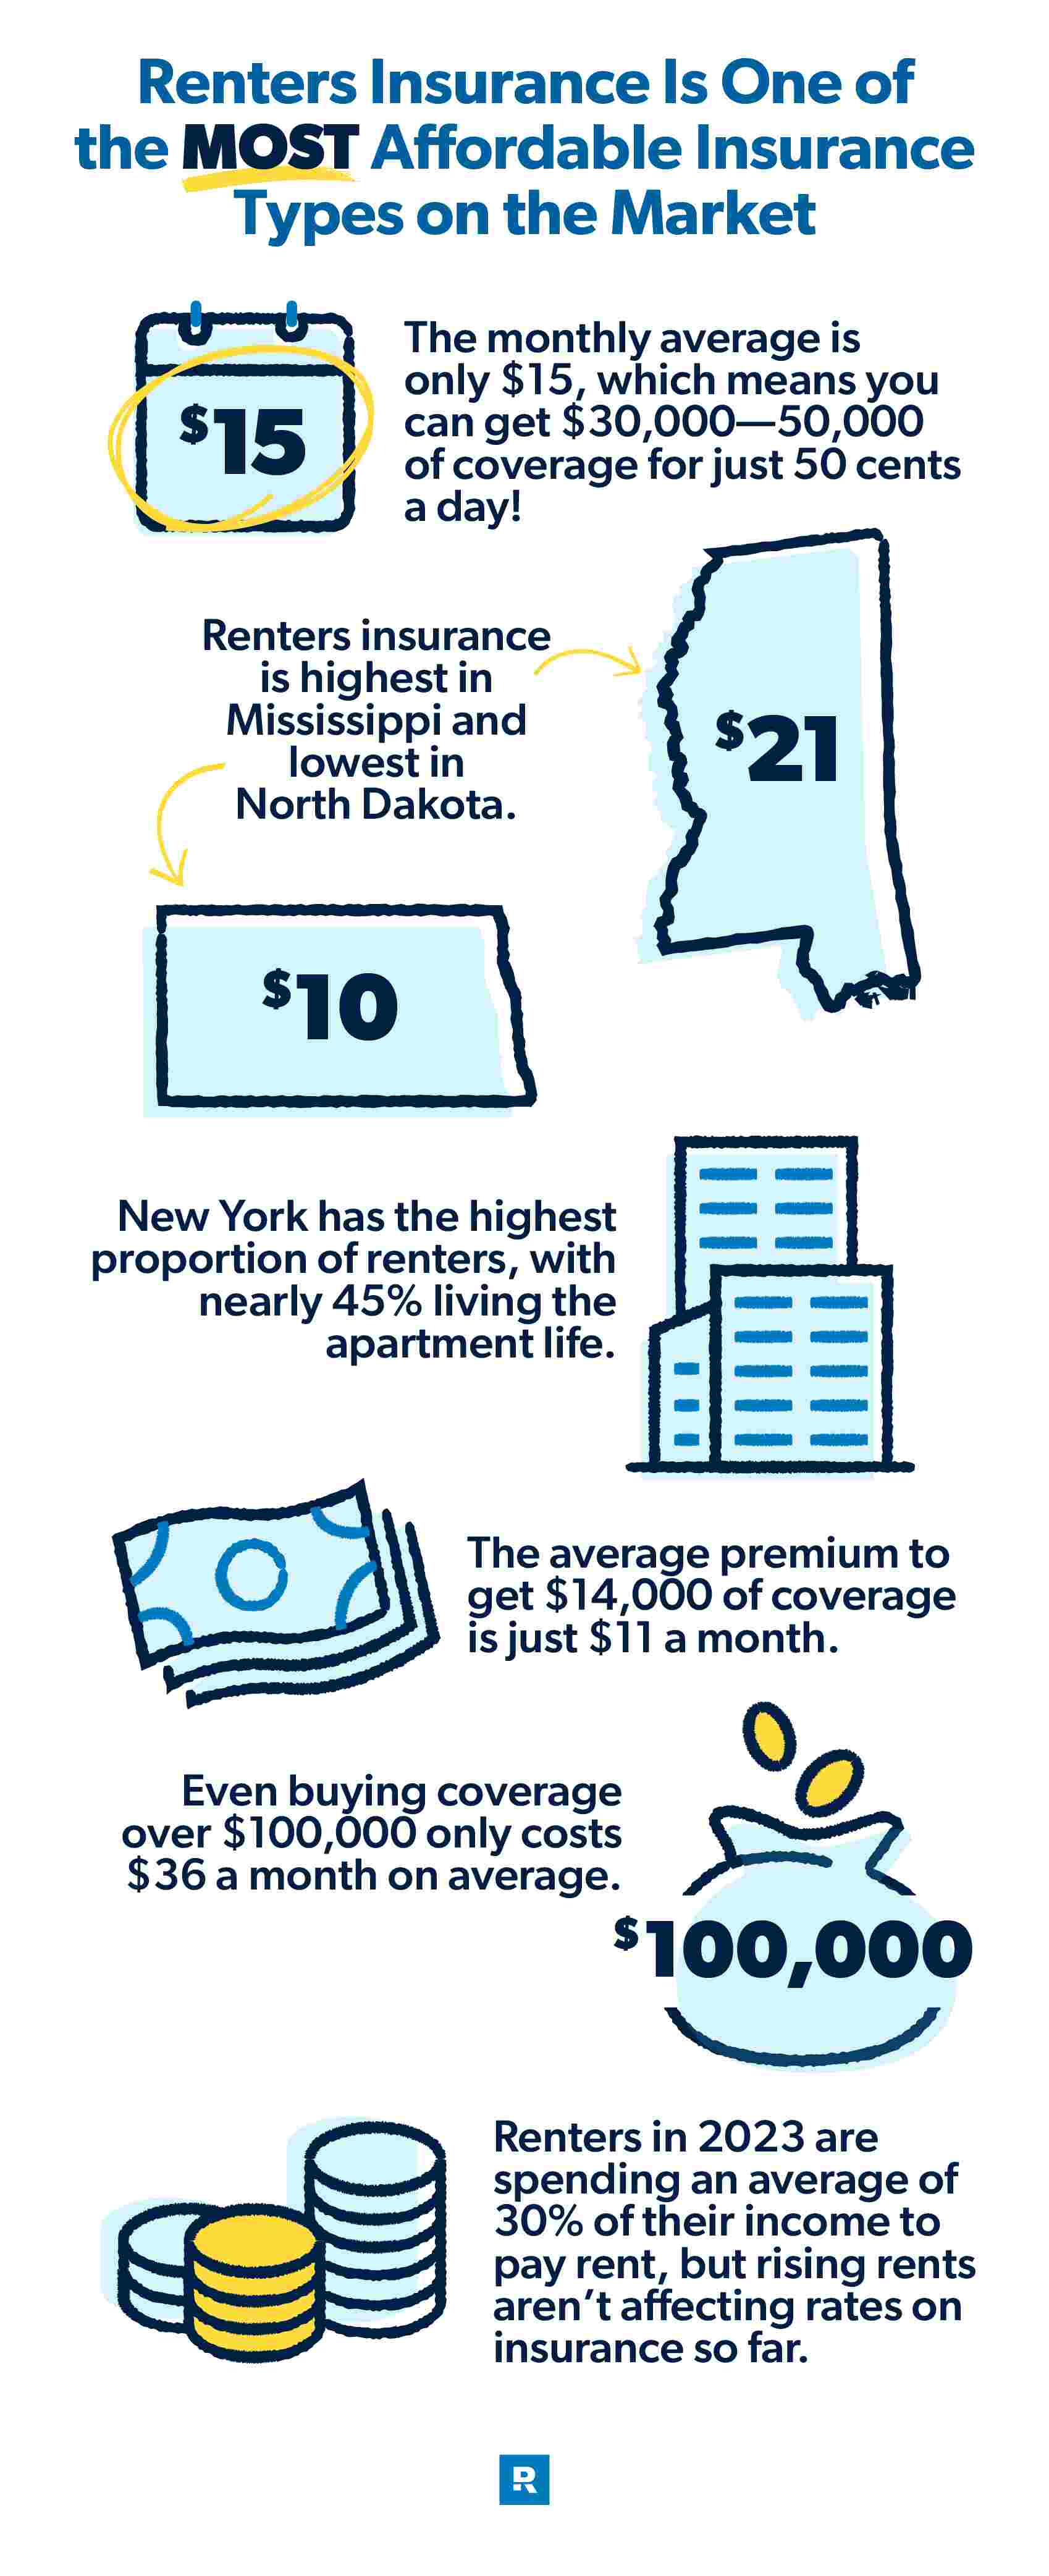
For budget-conscious renters in New Jersey, the cheapest renters insurance in 2026 typically starts at approximately $10 to $15 per month. Providers like Lemonade, NJM, and Toggle lead the market by offering customizable, low-limit policies that satisfy landlord requirements while protecting personal assets against fire, theft, and liability claims.
In a state with some of the highest cost-of-living metrics in the country, finding affordable renters insurance in New Jersey is a necessity for financial stability. Whether you are leasing a studio in Jersey City or a suburban apartment in Cherry Hill, your landlord’s insurance policy only covers the physical building—not your furniture, electronics, or personal liability. This guide examines the most cost-effective providers in the Garden State for 2026, the specific factors that influence NJ premiums, and how to maximize your coverage without breaking your monthly budget.
The Landscape of Renters Insurance in New Jersey
New Jersey is a unique market for insurance. Regulated by the New Jersey Department of Banking and Insurance (DOBI), the state mandates strict guidelines on how insurers can set rates and handle claims. For budget renters, this regulation is generally a benefit, as it prevents predatory pricing and ensures that even the lowest-cost policies provide a baseline level of protection.
As of 2026, the average cost of renters insurance in New Jersey remains slightly above the national average due to the state’s population density and the higher replacement value of goods in the Northeast. However, "budget" renters can still find exceptionally low rates by opting for "Actual Cash Value" (ACV) policies or by selecting higher deductibles.
Why Renters Insurance is Essential for Budgeting
Budgeting is about risk management. For a renter living paycheck to paycheck, a $2,000 theft or a kitchen fire could be financially catastrophic. Renters insurance acts as a "firewall" for your savings. For the price of a couple of cups of coffee per month, you transfer the risk of a five-figure loss to an insurance company. Furthermore, most NJ landlords now require a minimum of $100,000 in liability coverage as a condition of the lease.
Top Providers for the Cheapest Renters Insurance in NJ (2026)
The following companies have consistently offered the most competitive rates for basic coverage in the New Jersey market throughout 2026.
1. Lemonade: The Best for Tech-Savvy Budgeting
Lemonade remains a dominant force for budget renters in New Jersey because of its peer-to-peer business model and AI-driven underwriting. By streamlining the application process through an app, they reduce overhead costs and pass those savings to the consumer.
- Average Budget Rate: $10–$12 per month.
- Best Feature: "Giveback" program where unclaimed premiums go to charities, and the "Zero Everything" add-on which can eliminate deductibles for a small fee.
- Suitability: Ideal for young professionals in Hoboken or Jersey City who want a policy that can be managed entirely from a smartphone.
2. NJM Insurance Group: The Local Powerhouse
Originally the New Jersey Manufacturers Insurance Company, NJM is a staple for Garden State residents. While it was once restricted to certain employees, it is now open to the general public. NJM is frequently cited for its high customer satisfaction and competitive pricing for those who bundle their renters policy with auto insurance.
- Average Budget Rate: $12–$16 per month.
- Best Feature: Dividend potential. NJM often returns a portion of premiums to policyholders when the company performs well financially.
- Suitability: Best for long-term NJ residents who prefer a local company with physical offices and a strong reputation for claims processing.
3. Toggle (by Farmers): The Most Customizable
Toggle offers a "subscription" style of insurance that is perfect for budget renters who don’t own a lot of furniture but have specific items—like a high-end laptop or a bicycle—that they need to protect. You can "toggle" certain coverages on and off, allowing you to pay only for what you truly need.
- Average Budget Rate: $11–$14 per month.
- Best Feature: The "Credit Lift" feature, which reports your on-time insurance payments to credit bureaus, potentially helping you build credit while being insured.
- Suitability: Excellent for college students at Rutgers or Seton Hall who have limited assets but need liability and specific tech protection.
4. State Farm: The Best for Personal Service
While often thought of as a premium carrier, State Farm’s renters insurance rates in New Jersey are surprisingly low when you opt for basic limits. Their vast network of local agents can help budget renters find every available discount.
- Average Budget Rate: $14–$18 per month.
- Best Feature: Inflation protection. Their policies automatically adjust coverage limits based on the current cost of goods, ensuring you aren't underinsured.
- Suitability: Best for renters who want a "human connection" and the ability to walk into an office to discuss their policy.

Understanding Coverage Components for Budget Renters
To get the cheapest rate, you must understand what you are paying for. Most NJ policies are divided into four main categories:
- Personal Property: Covers your belongings (clothes, furniture, electronics). Budget policies often start at $10,000 to $15,000 in coverage.
- Personal Liability: Protects you if you are sued for accidentally causing bodily injury or property damage to others. The NJ standard is $100,000.
- Loss of Use (Additional Living Expenses): If your apartment becomes uninhabitable due to a covered peril (like a fire), this pays for hotel stays and meals.
- Medical Payments to Others: A smaller fund (usually $1,000) to pay for a guest’s medical bills if they are injured in your home, regardless of fault.
Actual Cash Value (ACV) vs. Replacement Cost Value (RCV)
This is the most critical decision for a budget renter.
- ACV pays out what your items are worth today (depreciated value). It is the cheaper option.
- RCV pays out what it costs to buy the item new today. It is roughly 10% to 15% more expensive but offers significantly better protection. For the absolute cheapest policy, ACV is the way to go, but be aware that a five-year-old laptop may only yield a $200 payout under ACV.
2026 Comparison Table: NJ Budget Renters Insurance
| Provider | Starting Monthly Premium | Standard Deductible | Key Advantage for Budget Renters |
|---|---|---|---|
| Lemonade | $10 | $500 | Fastest claims process; very low entry price. |
| NJM | $12 | $500 | Highly rated local service; potential dividends. |
| Toggle | $11 | $100 - $1,000 | Highly customizable; allows "per-item" coverage. |
| State Farm | $14 | $500 | Large discount for bundling with auto insurance. |
| Allstate | $16 | $500 | "Claim-Free Rewards" can lower future costs. |
Rates based on a standard 2026 profile for $15,000 personal property / $100,000 liability coverage in a mid-density NJ zip code.
Factors That Influence Your Renters Insurance Premium in NJ
Insurance companies use complex algorithms to determine your risk level. In New Jersey, the following factors have the most significant impact on your monthly bill:
1. Geographic Location (The Zip Code Factor)
Renters in Newark, Camden, or Paterson may face higher premiums than those in Warren or Hunterdon counties. This is due to higher statistics for theft and vandalism in urban centers. Conversely, coastal areas like Asbury Park or Atlantic City may see slightly higher rates due to the risk of storm damage, though renters insurance specifically excludes "rising water" flood damage (which requires a separate FEMA policy).
2. Credit-Based Insurance Scores
In New Jersey, insurers are permitted to use your credit history as a factor in setting your premium. According to the Insurance Information Institute (III), individuals with higher credit scores are statistically less likely to file claims. If you are a budget renter with a lower credit score, companies like Toggle or Lemonade may be more forgiving than traditional legacy carriers.
3. Your Deductible Choice
The deductible is the amount you pay out of pocket before the insurance kicks in. In 2026, the standard deductible is $500. By raising your deductible to $1,000, you can often lower your monthly premium by 15% to 25%. However, a budget renter should only do this if they actually have $1,000 in an emergency fund.
4. Safety Features of the Building
New Jersey fire codes are strict, but older buildings may lack modern suppression systems. If your apartment has a monitored fire alarm, a burglar alarm, or a sprinkler system, most NJ insurers will provide a 5% to 10% discount.
Strategies to Secure the Lowest Rates
If you are looking to drive your costs down to the absolute minimum in 2026, follow these expert strategies:
- Bundle with Auto Insurance: This is the single most effective way to save. Even if the renters policy costs $15 a month, the "multi-policy discount" might take $20 off your car insurance, effectively making the renters insurance free.
- Pay Annually: Most NJ insurers charge a "convenience fee" for monthly payments (ranging from $1 to $5). Paying the full year upfront can save you up to $60 annually.
- Opt for Paperless Billing: It sounds small, but many companies offer a $1 or $2 monthly discount for choosing electronic statements and autopay.
- Ask about Professional or Alumni Discounts: NJM and other providers often have partnerships with New Jersey-based employers, unions, or universities (like the NJEA or Rutgers Alumni).
Common Mistakes to Avoid When Seeking Cheap Insurance
In the pursuit of the lowest price, budget renters often fall into traps that leave them vulnerable:
- Underestimating the Value of Assets: Many renters think, "I only have old furniture; it’s worth nothing." However, if you had to replace your entire wardrobe, kitchenware, and electronics all at once, the cost would likely exceed $10,000.
- Ignoring the Liability Limit: While $100,000 is the standard, increasing it to $300,000 often costs less than $1 extra per month. In a litigious state like New Jersey, that extra protection is worth the cost of a candy bar.
- Assuming Roommates are Covered: In NJ, a renters policy typically only covers the "named insured" and their relatives. Your roommate usually needs their own separate policy. Sharing a policy is possible with some carriers, but it can lead to complications during claims.
- Neglecting the "Pet" Factor: If you own a dog, you must disclose it. Some "cheap" policies exclude certain breeds (like Pit Bulls or Rottweilers). Failing to disclose a pet can result in a denied liability claim if a bite occurs.
FAQ: Renters Insurance in New Jersey
Does New Jersey law require renters insurance?
No, the state of New Jersey does not legally mandate renters insurance. However, the majority of private landlords and property management companies in NJ include a clause in the lease requiring tenants to carry a minimum amount of liability insurance (usually $100,000) and to list the landlord as an "Interested Party" on the policy.
Does renters insurance cover flood damage in NJ?
Standard renters insurance policies in New Jersey cover water damage from burst pipes or overflowing bathtubs, but they do not cover damage from "rising water" (flood) or storm surges. If you live in a basement apartment or a flood-prone area like the Meadowlands or the Jersey Shore, you should look into a separate policy through the National Flood Insurance Program (NFIP).
How do I file a claim if my budget provider is online-only?
Digital-first companies like Lemonade use AI to process claims. You typically take a video of yourself explaining the loss and upload photos of the damage or receipts. For budget renters, this often results in a faster payout than traditional companies, sometimes within minutes for simple claims like a stolen bicycle.
Can I get renters insurance if I have a poor credit score in NJ?
Yes, but you may pay a higher premium. New Jersey allows insurers to use "credit-based insurance scores." If your credit is poor, look for companies that emphasize "usage-based" or "customizable" insurance, as they may weigh other factors more heavily.
Will my premium go up if I file one claim?
In New Jersey, a single claim can lead to a premium increase upon renewal, or the loss of a "claims-free discount." For small losses that are only slightly above your deductible (e.g., a $600 loss with a $500 deductible), it is often more cost-effective for a budget renter to pay out of pocket rather than filing a claim.
Final Recommendation for NJ Renters
To find the cheapest renters insurance in NJ for 2026, start by obtaining a quote from Lemonade to establish a price floor. Then, check with NJM or your current auto insurance provider to see if a bundling discount can beat that price.
For the best balance of cost and protection, select a $500 deductible, ensure you have Replacement Cost Value (not Actual Cash Value) for your property, and set your liability at $100,000. This configuration typically provides the most comprehensive protection for the lowest possible monthly investment, ensuring that a single accident doesn't derail your financial future in the Garden State.
Image Gallery
Select an image to open it in a new tab.


Akira Tanaka
International Academic Trends Correspondent
