New York Life Insurance Structured Settlement: Definition and Key Considerations
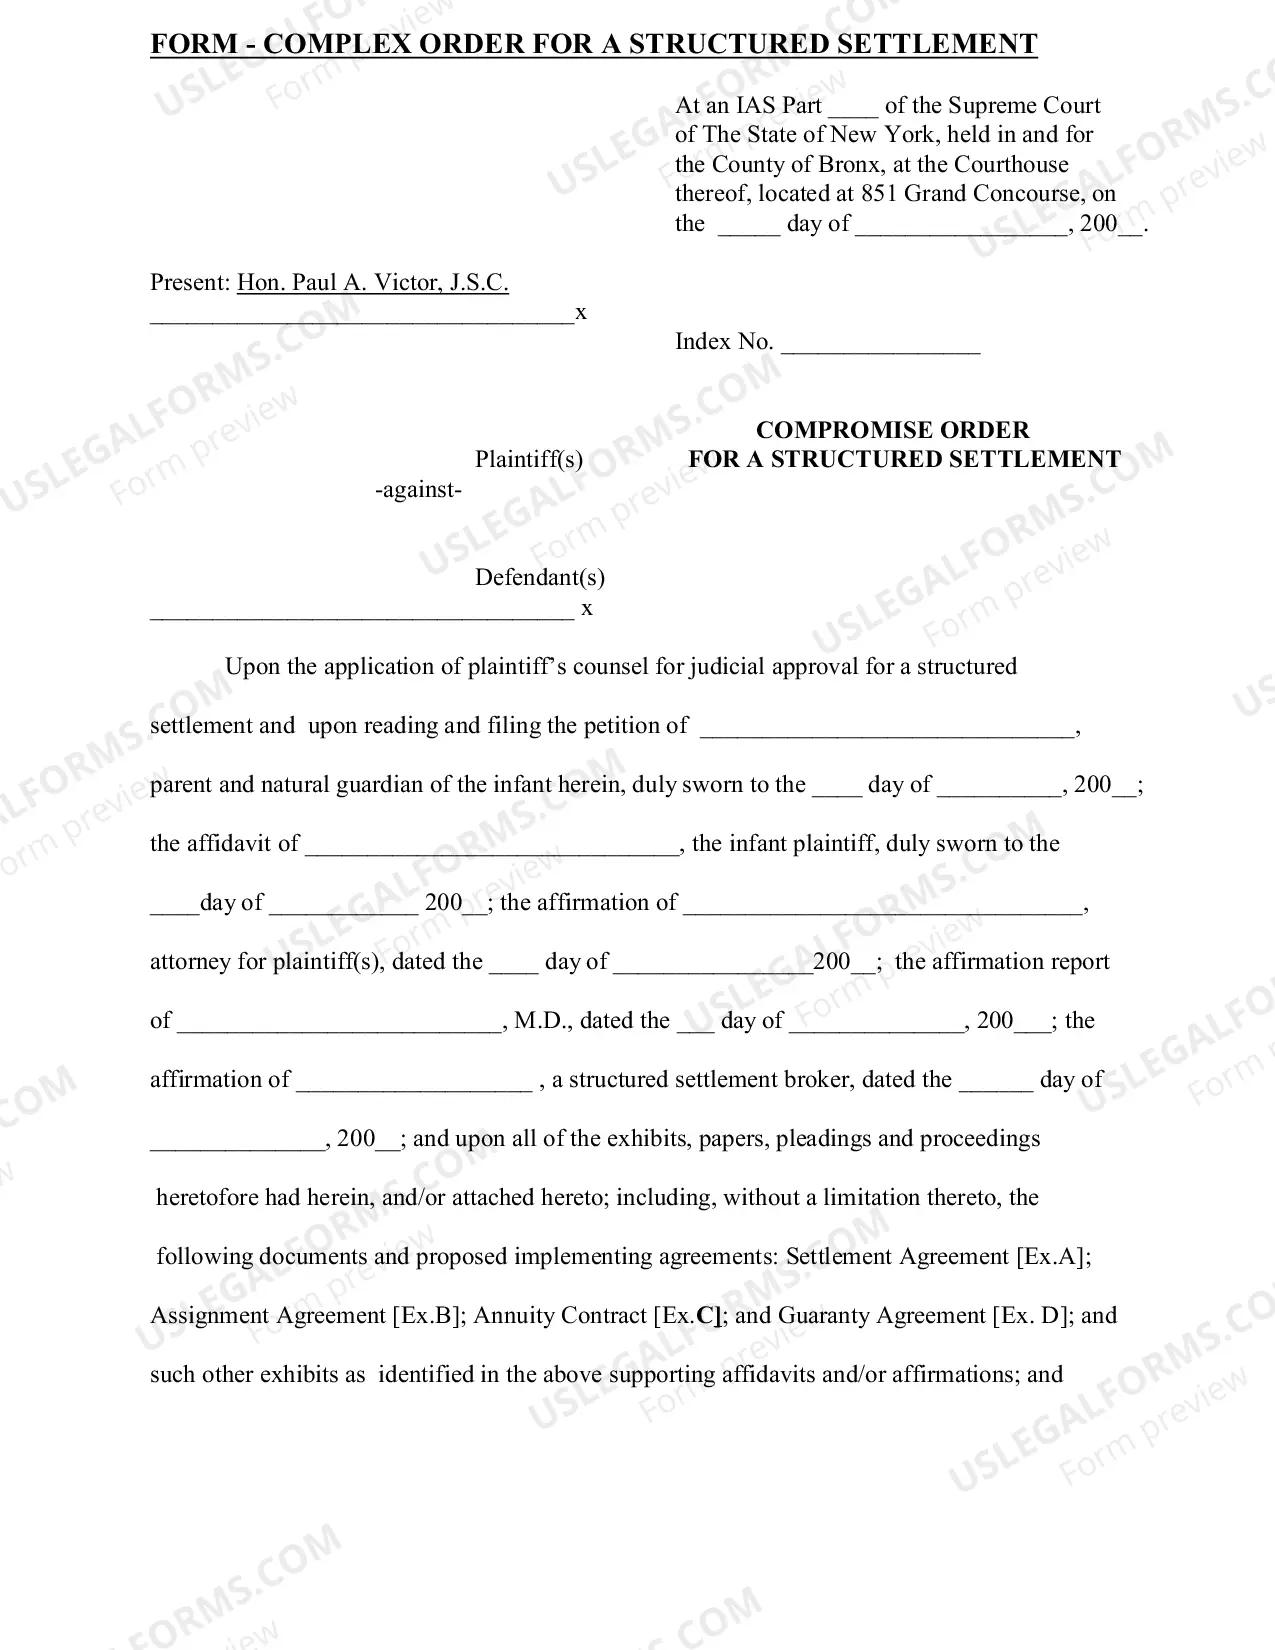
A New York Life insurance structured settlement is a specialized financial arrangement used primarily in personal injury and wrongful death cases. It allows a claimant to receive a portion or the entirety of their settlement through a series of periodic, tax-free payments funded by an annuity issued by New York Life. This structure provides long-term financial security compared to a single lump-sum payout.
Structured settlements represent a fundamental shift in how legal resolutions are managed. Instead of receiving a large windfall that may be quickly depleted, the injured party receives guaranteed income over a set period—or even a lifetime. New York Life, as one of the oldest and most financially stable mutual life insurance companies in the United States, plays a critical role as the annuity provider, ensuring that these future obligations are met with the highest degree of reliability.
Defining the Structured Settlement Framework
To understand a New York Life structured settlement, one must first understand the legal mechanism of the "structured settlement" itself. Originating from federal tax legislation in the late 1970s and early 1980s, these arrangements were designed to protect injured parties from the "dissipation" of funds. Statistics historically showed that many recipients of large lump-sum settlements exhausted their funds within a few years due to poor investment choices, predatory lending, or simple overspending.
In a typical New York Life structured settlement, the defendant (the party at fault) or their liability insurer agrees to pay the claimant. However, instead of writing a check for the total amount, they transfer the obligation to a "qualified assignment" company—often a subsidiary of New York Life, such as New York Life Annuity and Settlement Options Corporation (NYLAS). NYLAS then purchases an annuity from New York Life Insurance Company to fund the specific payment schedule agreed upon by the claimant.
This tripartite arrangement is essential for maintaining the tax-exempt status of the payments under the Internal Revenue Code. Because New York Life is a mutual company, its primary focus is on long-term stability and policyholder interests, which makes it a preferred choice for plaintiffs seeking a "set-and-forget" financial safety net.
The Role of New York Life in the Settlement Market
New York Life is a dominant force in the structured settlement industry. As of 2026, the company continues to leverage its "AAA" or equivalent ratings from major credit agencies to attract large-scale legal settlements. When a plaintiff chooses New York Life, they are essentially buying into a promise that spans decades.
Financial Strength and Reliability
The most critical consideration for any structured settlement is the "claims-paying ability" of the life insurance company. Because a settlement might last 40, 50, or 60 years, the risk is not in the market's performance, but in the company's solvency. New York Life consistently maintains the highest possible ratings from:
- A.M. Best: A++ (Superior)
- Fitch: AAA (Exceptionally Strong)
- Moody’s: Aaa (Exceptional)
- Standard & Poor’s: AA+ (Very Strong)
These ratings indicate that New York Life has the capital reserves necessary to fulfill its obligations even during severe economic downturns. For a person with a permanent disability who relies on these payments for medical care, this institutional stability is the primary "key consideration."

Key Considerations for Claimants and Attorneys
Deciding to structure a settlement through New York Life involves several technical and personal factors. It is not merely a matter of choosing a payment date; it is about designing a financial architecture that survives the claimant's changing needs.
1. Tax-Free Growth and Payments
The most significant advantage of a structured settlement is found in Internal Revenue Code Section 104(a)(2). For cases involving physical injury or physical sickness, the entirety of the periodic payments—including the interest that grows over time—is 100% exempt from federal and state income taxes.
If a claimant takes a $1,000,000 lump sum and invests it in a standard brokerage account, they must pay taxes on any dividends or capital gains earned. In contrast, if that $1,000,000 is used to purchase a New York Life structured settlement annuity, every penny paid out over the years is tax-free. In many cases, this can result in a 25% to 35% higher net yield compared to traditional investments.
2. Customization of Payment Streams
New York Life offers high degrees of flexibility in how payments are scheduled. Unlike a standard pension, a structured settlement can be designed with:
- Level Payments: The same amount every month for life.
- Step-Up Payments: Payments that increase by a certain percentage (e.g., 3% annually) to combat inflation.
- Lump-Sum "Bumps": Larger payments scheduled at specific intervals (e.g., $50,000 every five years for a new vehicle or home repairs).
- Deferred Starts: Payments that begin only when the claimant reaches retirement age or when a minor child turns 18.
3. The Irrevocability Factor
One of the most vital "key considerations" is that once a structured settlement is finalized and the annuity is issued by New York Life, the terms are generally irrevocable. You cannot call New York Life three years later and ask to "cash out" the annuity or change the payment dates.
This rigidity is a legal requirement to preserve the tax-free status. While there is a "secondary market" where companies offer to buy settlement payments for a lump sum (often referred to as factoring), these transactions usually involve steep discounts and require court approval under the Structured Settlement Protection Acts (SSPA) found in most states. Therefore, the original design must be handled with extreme care.
4. Qualified Assignments and Security
When New York Life handles a settlement, they typically use a "Qualified Assignment" under IRC Section 130. This process legally transfers the payment obligation from the defendant to a New York Life assignment company. This is beneficial for the claimant because it removes the credit risk of the defendant (who might be a small trucking company or a local hospital) and replaces it with the credit risk of a multi-billion dollar insurance institution.
Comparing Structured Settlements vs. Lump Sums
Choosing between a New York Life annuity and a traditional lump sum requires a balanced look at liquidity versus security.
| Feature | New York Life Structured Settlement | Traditional Lump Sum |
|---|---|---|
| Tax Treatment | 100% Tax-Free (under IRC 104(a)(2)) | Only the initial principal is tax-free; gains are taxable. |
| Market Risk | None; payments are guaranteed by NYL. | High; subject to stock/bond market volatility. |
| Management Fees | None (built into the annuity pricing). | Ongoing fees for financial advisors or trust officers. |
| Liquidity | Low; payments are fixed and hard to change. | High; funds can be accessed at any time. |
| Safety | High; protected by NYL's AAA-rated surplus. | Dependent on individual investment choices. |
| Creditor Protection | High; usually exempt from most garnishments. | Variable; depends on state law and asset shielding. |
Technical Depth: The Qualified Assignment Process
The "Qualified Assignment" is the engine that makes the New York Life structured settlement work. For the payments to be tax-exempt, the claimant cannot have "constructive receipt" of the money used to buy the annuity. If the defendant gives the money to the claimant and then the claimant buys the annuity from New York Life, the tax-free status is lost.
Instead, the defendant pays the "assignment fee" to New York Life Annuity and Settlement Options Corporation. This subsidiary then takes on the legal duty to pay the claimant. Because NYLAS is a special-purpose vehicle, it is designed to hold these obligations safely. To ensure the money is there, NYLAS buys an annuity from its parent company, New York Life Insurance Company. The claimant is designated as the "payee," and the annuity is the "funding asset."
This structure is highly regulated. In the event of an insurance company insolvency (which has never happened to New York Life), state guaranty associations provide an additional layer of protection, though New York Life's capital position makes this a remote concern.
Common Pitfalls to Avoid
While New York Life provides a robust product, the effectiveness of the settlement depends on the strategy used during negotiations.
- Underestimating Inflation: If a claimant signs up for a flat $2,000 monthly payment for life in 2026, that $2,000 will have significantly less purchasing power in 2056. Including a Cost of Living Adjustment (COLA) of 2% or 3% is an essential consideration for long-term settlements.
- Ignoring Immediate Needs: Claimants often structure too much of their settlement. It is usually wise to take a "hybrid" approach: a lump sum for immediate needs (debts, home modifications, legal fees) and a New York Life structure for future income.
- Failing to Coordinate with Public Benefits: For claimants receiving Medicaid or Supplemental Security Income (SSI), a structured settlement payment might count as "income," potentially disqualifying them from these programs. In such cases, the New York Life payments should be directed into a Special Needs Trust (SNT) to preserve benefit eligibility.
The 2026 Economic Context
In the current 2026 financial landscape, interest rates have stabilized after the volatility of the early 2020s. This stability allows New York Life to offer competitive internal rates of return on their annuities. For plaintiffs, this means the "spread" between a lump sum investment and a structured settlement is more favorable than it was during the "zero-rate" era.
Furthermore, New York Life has integrated more modern reporting tools. Payees can now monitor their upcoming schedules and tax documents (though most are 100% tax-exempt) through secure digital portals, providing a level of transparency that was previously lacking in the insurance industry.
Frequently Asked Questions
What happens if I die before all payments are made?
This depends on how the settlement was designed. If you choose a "Life Only" annuity, payments stop upon death. However, most New York Life settlements include a "Period Certain" (e.g., Life with 20 years certain). If the payee dies within that 20-year window, the remaining guaranteed payments go to their designated beneficiaries, still tax-free.
Is New York Life better than a structured settlement from another company?
"Better" is subjective, but New York Life is among the "Big Four" providers (alongside companies like Berkshire Hathaway, Prudential, and MetLife). Its unique status as a mutual company means it is owned by its policyholders, which often results in a more conservative investment philosophy that prioritizes long-term safety over short-term stock prices.
Can I sell my New York Life structured settlement if I have an emergency?
Yes, it is possible through the secondary market, but it is rarely recommended. You would sell your future payments to a factoring company in exchange for a lump sum today. However, you will receive significantly less than the present value of those payments, and you must get a judge to sign off on the deal by proving it is in your "best interest."
Does New York Life charge annual management fees?
No. Unlike a mutual fund or a managed bank account, there are no ongoing management fees or "load" charges taken out of your monthly checks. The administrative costs are factored into the initial purchase price of the annuity by the defendant or their insurer.
Can a structured settlement cover medical expenses for a "Workers' Comp" case?
Yes, New York Life often provides annuities for Workers' Compensation Medicare Set-Aside Arrangements (WCMSA). This ensures that funds are available specifically for future Medicare-covered medical expenses related to the injury, preventing the claimant from losing Medicare coverage.
Practical Recommendation
When considering a New York Life structured settlement, your first action should be to consult with a Certified Structured Settlement Consultant (CSSC) or a plaintiff-loyal settlement planner. Unlike a general financial advisor, these specialists understand the nuances of IRC Section 104(a)(2) and the specific requirements of the qualified assignment process.
You should request a "benefit illustration" from New York Life that shows multiple scenarios: one with inflation protection, one with deferred payments, and one with a series of lump-sum "balloons." Compare these internal rates of return against what you could reasonably expect from a conservative investment portfolio, keeping in mind that the New York Life payout is guaranteed and tax-free, whereas market investments carry risk and tax liabilities.
Finally, ensure that any settlement agreement explicitly names New York Life Insurance Company (or its authorized assignment subsidiary) as the provider. This ensures you are backed by one of the strongest balance sheets in the financial world, providing peace of mind for the duration of your recovery and beyond.
Image Gallery
Select an image to open it in a new tab.


Ingrid Bjornson
Global Cyber Policy and Regulation Analyst
