Understanding Cincinnati Life Non-Med Term Insurance: A Comprehensive 2026 Guide
Cincinnati Life non-med term insurance is a specific life insurance offering that utilizes accelerated underwriting to provide coverage without requiring a physical medical examination. By leveraging real-time data from prescription histories, motor vehicle records, and the Medical Information Bureau, Cincinnati Life evaluates the risk of qualified applicants instantly, often resulting in policy issuance within days rather than months.
The landscape of life insurance in 2026 emphasizes speed and consumer convenience without sacrificing the financial stability offered by legacy carriers. For many individuals, the traditional process of scheduling a paramedical exam—involving blood draws, urine samples, and height/weight measurements—is a significant barrier to securing protection. The Cincinnati Life Insurance Company, a subsidiary of Cincinnati Financial Corporation, addresses this by offering "no-exam" options within its LifeHorizons Term portfolio. This guide explores the technical requirements, benefits, and operational mechanics of securing non-medical term insurance through Cincinnati Life.
The Evolution of Non-Medical Underwriting in 2026
Historically, "non-med" insurance was synonymous with "simplified issue" policies, which often carried higher premiums and lower coverage limits because the insurer had less data about the applicant's health. In 2026, the industry has transitioned toward Accelerated Underwriting (AU). Cincinnati Life’s approach is a sophisticated version of AU, where the "non-med" component is a reward for applicants who meet specific health and lifestyle criteria.
Unlike guaranteed issue policies that accept almost everyone at a high cost, Cincinnati Life’s non-med term insurance is fully underwritten using digital data. The company uses algorithmic risk scoring to determine if a physical exam can be waived. If the digital data matches the self-reported information on the application and indicates a low risk, the medical exam is bypassed entirely. This allows the consumer to access "Preferred" or even "Preferred Plus" rates—traditionally reserved for the healthiest individuals—without the inconvenience of a needle poke.
Eligibility and Requirements for Non-Med Approval
Not every applicant is eligible for the non-medical path. Cincinnati Life maintains strict guidelines to ensure the integrity of its risk pool, which in turn keeps premiums competitive for all policyholders. As of 2026, the eligibility criteria typically hinge on three primary factors: age, coverage amount, and medical history.
Age and Coverage Limits
For the 2026 policy year, Cincinnati Life generally offers accelerated underwriting for:
- Ages 18 to 45: Coverage amounts up to $1,000,000.
- Ages 46 to 55: Coverage amounts up to $500,000.
- Ages 56 to 60: Coverage may be available without an exam for smaller face amounts, typically capped at $250,000, depending on specific state filings and product versions.
Applicants seeking coverage above these thresholds or those outside these age brackets will almost certainly be required to undergo a traditional medical exam.
Health and Lifestyle Benchmarks
To qualify for the non-med process, an applicant must generally fall within a "Standard" or better risk class. Disqualifying factors that might trigger a requirement for a physical exam include:
- Significant Chronic Conditions: History of heart disease, stroke, cancer, or insulin-dependent diabetes.
- Body Mass Index (BMI): Applicants must fall within a specific height-to-weight ratio.
- High-Risk Activities: Involvement in hazardous hobbies like SCUBA diving at extreme depths or private aviation.
- Driving Record: Multiple major moving violations or a recent DUI/DWI.
The Application Process: Step-by-Step
Understanding the workflow of a Cincinnati Life non-med application helps set realistic expectations for the timeframe and the necessary documentation.
- Initial Quote and Needs Analysis: Working with an independent agent, the applicant determines the necessary death benefit and term length (e.g., 10, 15, 20, 25, or 30 years).
- Electronic Application (e-App): The applicant completes a digital questionnaire. This includes detailed questions about personal medical history, family health history, and lifestyle habits.
- Data Retrieval: Once the application is submitted, Cincinnati Life’s systems automatically query several databases. These include the Medical Information Bureau (MIB), which tracks previous insurance applications; Pharmacy Benefit Managers (PBMs), which provide a history of prescribed medications; and LexisNexis, for motor vehicle and public record data.
- The Underwriting Decision:
- Approval: If the data confirms the applicant’s health status, the policy is approved "as applied for" without an exam.
- Refer to Underwriter: If there is a discrepancy or a minor health issue, a human underwriter reviews the file.
- Exam Required: If the data is insufficient or indicates a higher risk, the applicant is "knocked out" of the accelerated path and must schedule a paramedical exam to continue.
- Policy Issuance: Once approved, the policy is delivered electronically (e-delivery), and coverage begins upon receipt of the first premium payment.
Product Features and Riders
Cincinnati Life’s term products are not just about the death benefit; they include several "built-in" and optional features that provide flexibility over the life of the policy.
Conversion Privilege
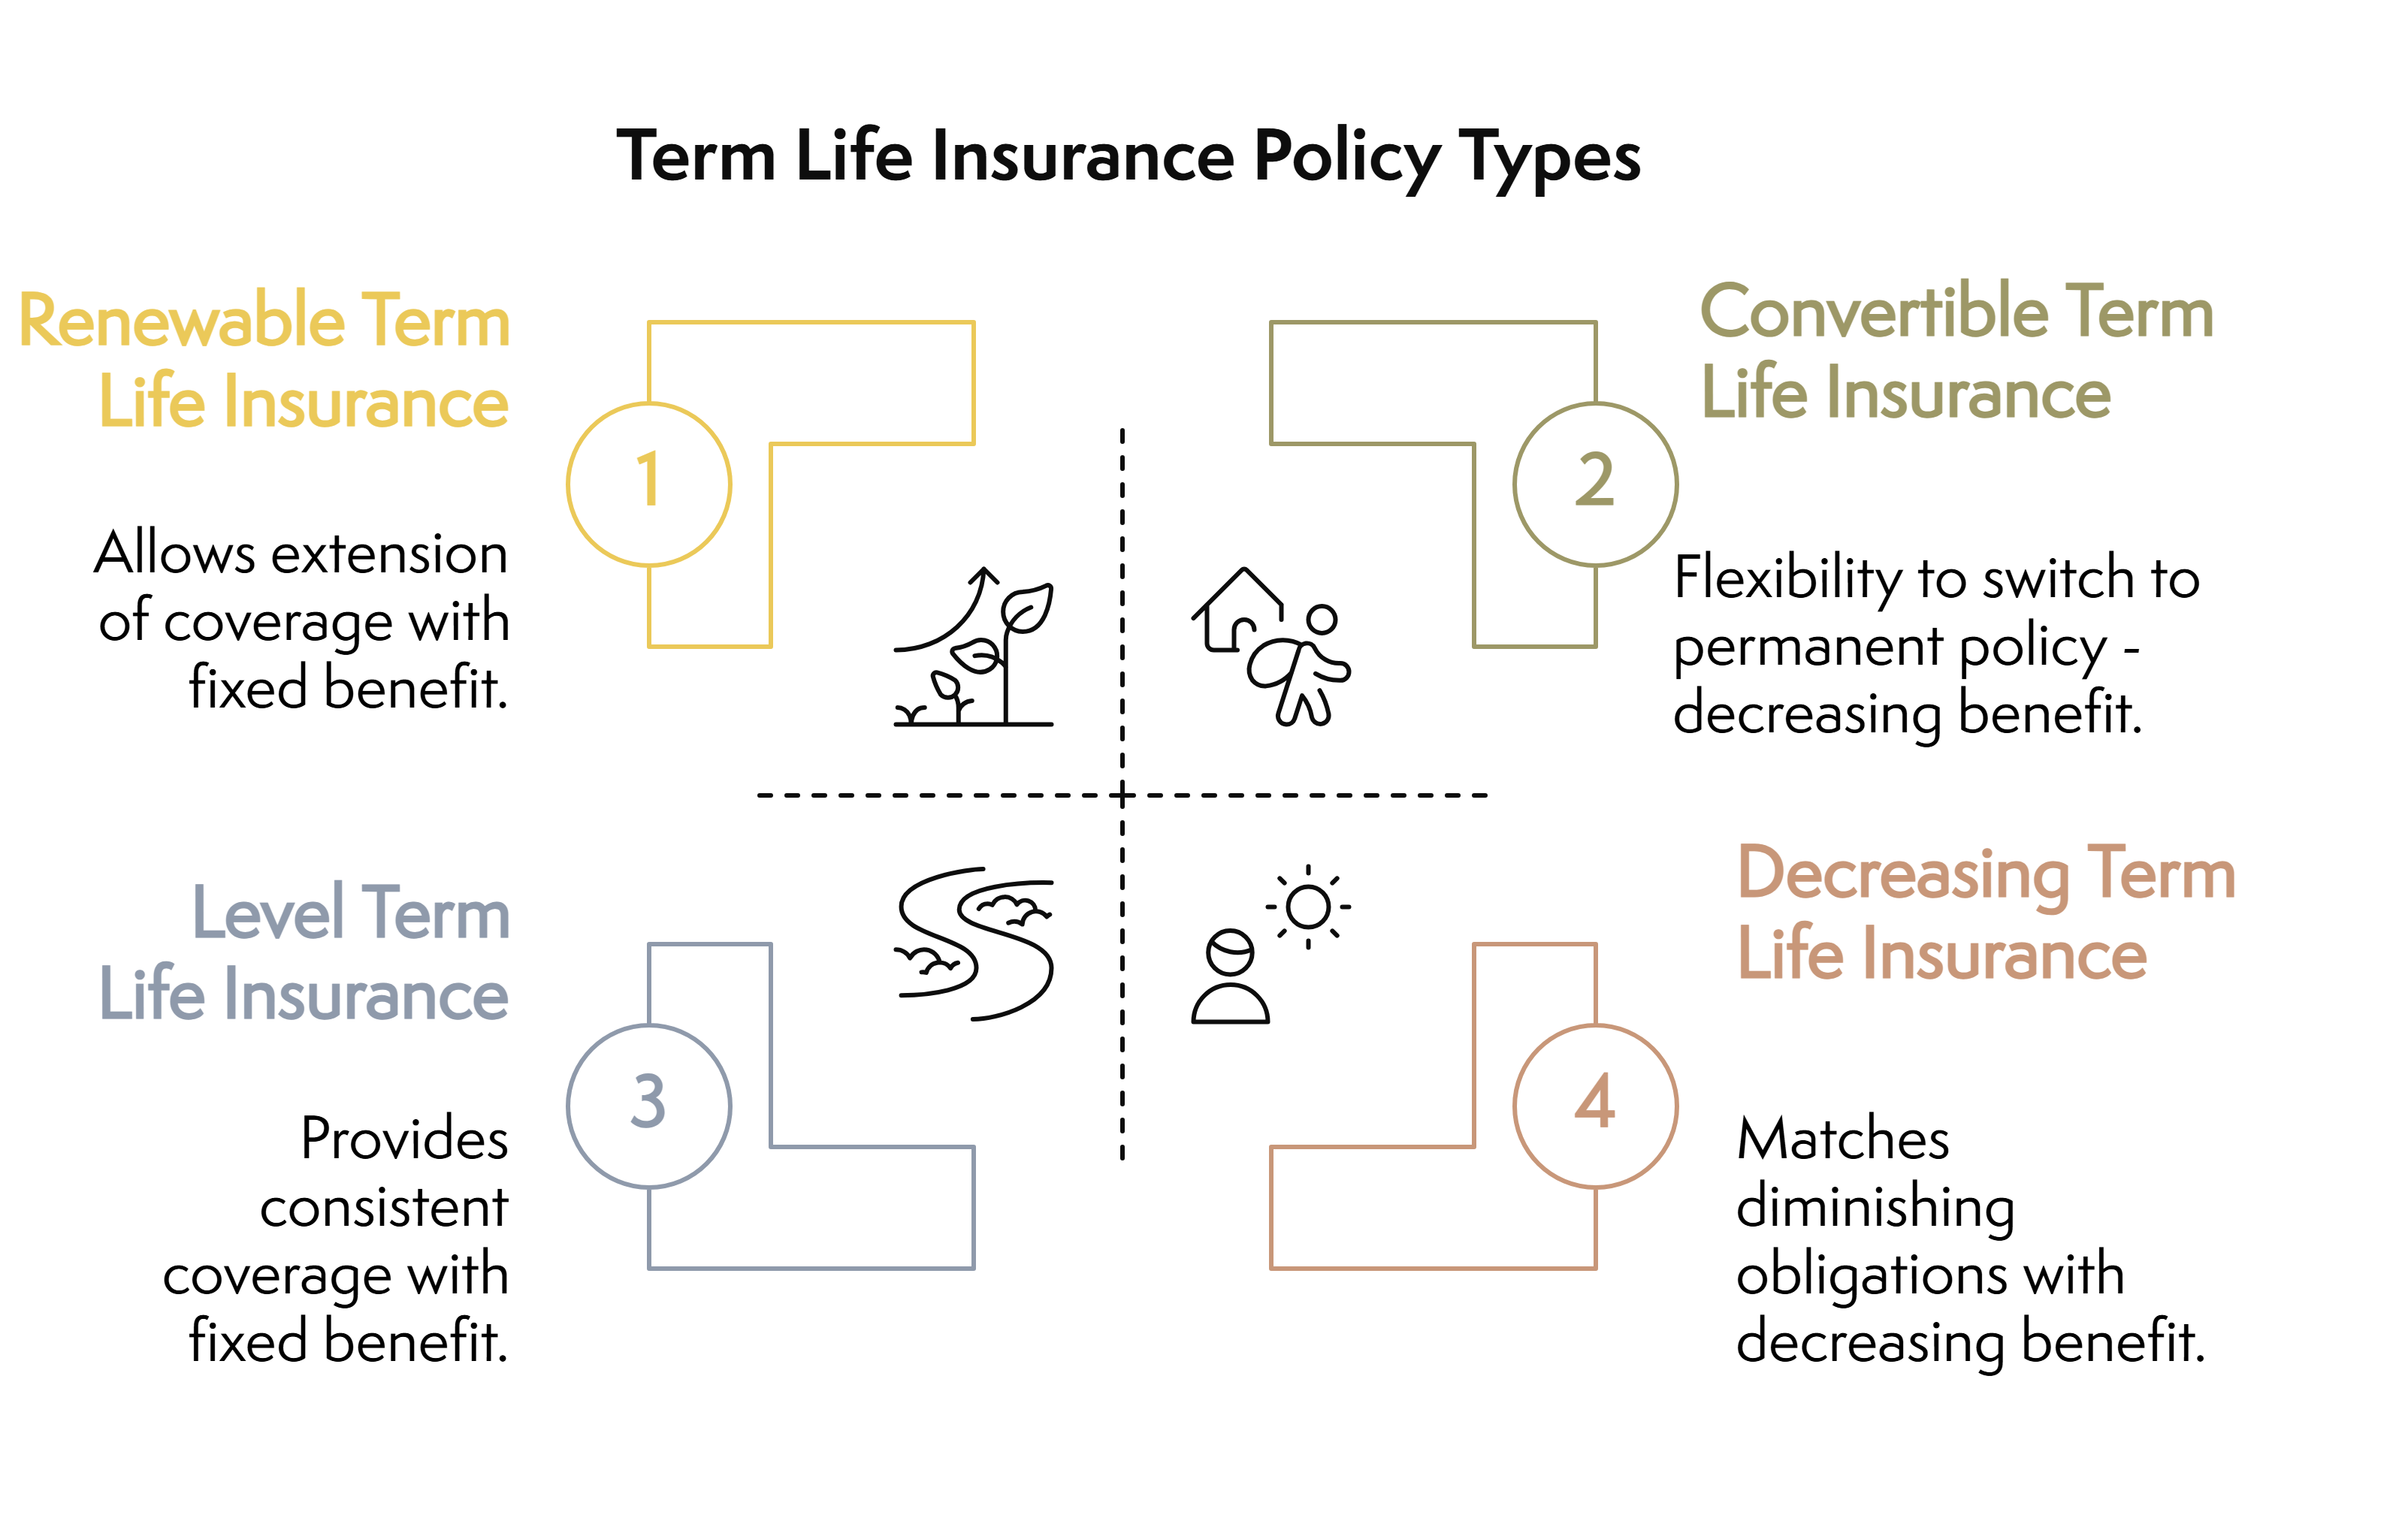
One of the most valuable aspects of a Cincinnati Life term policy is the conversion privilege. This allows the policyholder to convert their term insurance into a permanent whole life or universal life policy without proving insurability again. In 2026, this is a critical hedge against future health changes. If a policyholder develops a chronic illness during the term, they can "lock in" permanent coverage at the same risk class they had when they first bought the term policy, regardless of their current health.
Accelerated Death Benefit Rider
Most Cincinnati Life term policies include an Accelerated Death Benefit rider at no additional premium cost (though a fee may apply at the time of exercise). This allows the insured to access a portion of the death benefit if they are diagnosed with a terminal illness with a limited life expectancy (usually 12 to 24 months). This liquidity can be used to cover medical bills, hospice care, or other end-of-life expenses.
Waiver of Premium
For an additional fee, applicants can add a Waiver of Premium rider. If the insured becomes totally disabled and is unable to work, Cincinnati Life will pay the premiums on their behalf to ensure the coverage does not lapse during the period of disability.
Comparing Underwriting Methods in 2026
To understand where Cincinnati Life’s non-med term insurance fits, it is helpful to compare the three primary methods of obtaining life insurance.
| Feature | Accelerated Underwriting (Cincinnati Life) | Traditional Underwriting | Simplified/Guaranteed Issue |
|---|---|---|---|
| Medical Exam | No (for qualified applicants) | Yes (Blood, Urine, Vitmals) | Never |
| Speed to Issue | 24 hours to 7 days | 4 to 8 weeks | 24 to 48 hours |
| Maximum Coverage | Up to $1,000,000 | Virtually Unlimited | Usually capped at $50,000 |
| Cost/Premium | Low (Competitive with traditional) | Lowest (Most precise) | Very High |
| Data Usage | Extensive (MIB, Rx, MVR) | Extensive + Lab Results | Minimal |
| Best For | Healthy individuals seeking speed | Individuals with complex health | Those with severe health issues |
Advantages and Disadvantages
The Pros
- Convenience: No need to wait for a technician to visit your home or office.
- Competitive Pricing: Unlike older non-med products, 2026 accelerated underwriting provides rates nearly identical to those requiring an exam.
- Financial Strength: Cincinnati Financial Corporation consistently holds high ratings from agencies like A.M. Best (often A+ or higher), ensuring the company’s ability to pay future claims.
- Independent Agent Network: Cincinnati Life sells through independent agents who can provide personalized advice rather than using a "one-size-fits-all" call center.
The Cons
- The "Bait and Switch" Risk: Applicants might apply expecting no exam, only to be told halfway through the process that an exam is required due to an ambiguous data point.
- Strict Health Requirements: If you are even slightly overweight or have managed hypertension, you may be disqualified from the non-med path.
- Digital Footprint Necessity: Individuals who have not lived in the U.S. long or who have a "thin" digital file (little medical or credit history) may not be eligible for automated approval.
Cost Considerations and Pricing Factors
In 2026, the premium for a Cincinnati Life non-med term policy is determined by several variables. While the exam is waived, the underlying math remains grounded in actuarial science.
- Premium Frequency: Most policyholders choose monthly electronic funds transfer (EFT), but paying annually often results in a 2% to 5% discount, as it reduces administrative overhead for the insurer.
- Tobacco Status: There is a significant price gap between "Non-Tobacco" and "Tobacco" users. In 2026, many insurers, including Cincinnati Life, also look at the use of e-cigarettes and nicotine replacement therapies when determining these rates.
- Policy Fee: Like most carriers, Cincinnati Life includes a "policy fee" (usually between $60 and $100 annually) that is baked into the premium to cover the cost of maintaining the account.
- Term Length Selection: A 30-year term will have a higher monthly cost than a 10-year term because the insurer is taking on the risk of death over a much longer and older period of the insured's life.
Common Pitfalls to Avoid
When applying for Cincinnati Life non-med term insurance, certain mistakes can lead to delays or outright denials.
Non-Disclosure: The most common mistake is failing to disclose a minor medication or a past medical consultation. Because the company pulls your pharmacy and MIB records immediately, any discrepancy between the application and the digital data will trigger a "red flag." This often results in a manual underwriter requesting a full medical exam to clarify the inconsistency.
Applying for Too Much Coverage: If you are 50 years old and apply for $1,000,000 in coverage, you will automatically be moved to the traditional underwriting track. If your goal is to avoid an exam, you must stay within the published face-amount limits for your age bracket.
Ignoring the Conversion Window: Many policyholders forget that their term insurance has an expiration date. It is vital to review the policy every few years, especially if your health declines, to determine if you should exercise the conversion privilege before the window closes (often at age 70 or the end of the term, whichever comes first).
Frequently Asked Questions
Does "non-med" mean they don't check my medical history?
No. "Non-med" simply means there is no physical examination or fluid collection. Cincinnati Life still performs a comprehensive review of your medical history through digital records, including your prescription history and the Medical Information Bureau (MIB).
What happens if Cincinnati Life decides I need an exam after I apply?
If the initial data sweep reveals information that requires further investigation, you will be notified that you must undergo a paramedical exam. You are not obligated to proceed, but if you want the coverage, you must comply. The cost of this exam is paid for by Cincinnati Life.
Can I get non-med term insurance if I smoke?
Yes, but you will be charged "Tobacco" rates, which are significantly higher than "Non-Tobacco" rates. As long as you meet the other health and lifestyle criteria, you can still qualify for the accelerated underwriting process.
Is Cincinnati Life available in all states?
Cincinnati Life is licensed in most states, but product availability and specific non-med limits can vary based on state-specific insurance regulations. It is best to consult with a licensed agent in your jurisdiction to confirm current 2026 availability.
How long does the approval take?
For those who qualify for the streamlined process, approval can occur in as little as 24 to 72 hours. If a manual review is required, it may take 5 to 7 business days. This is significantly faster than the 4 to 6 weeks required for traditional underwriting.
Final Recommendation
Cincinnati Life’s non-med term insurance is an excellent solution for healthy individuals who value time and convenience. In 2026, the company’s blend of high-tech data analysis and traditional financial strength makes it a top-tier choice for families and business owners. To ensure the best outcome, applicants should be entirely transparent on their initial questionnaire and stay within the age and coverage limits defined for accelerated underwriting. If you have a complex medical history, be prepared for the possibility of a traditional exam, but for the majority of "standard" risk applicants, this non-medical path offers a frictionless way to secure essential financial protection.
Image Gallery
Select an image to open it in a new tab.


Ingrid Bjornson
Global Cyber Policy and Regulation Analyst
