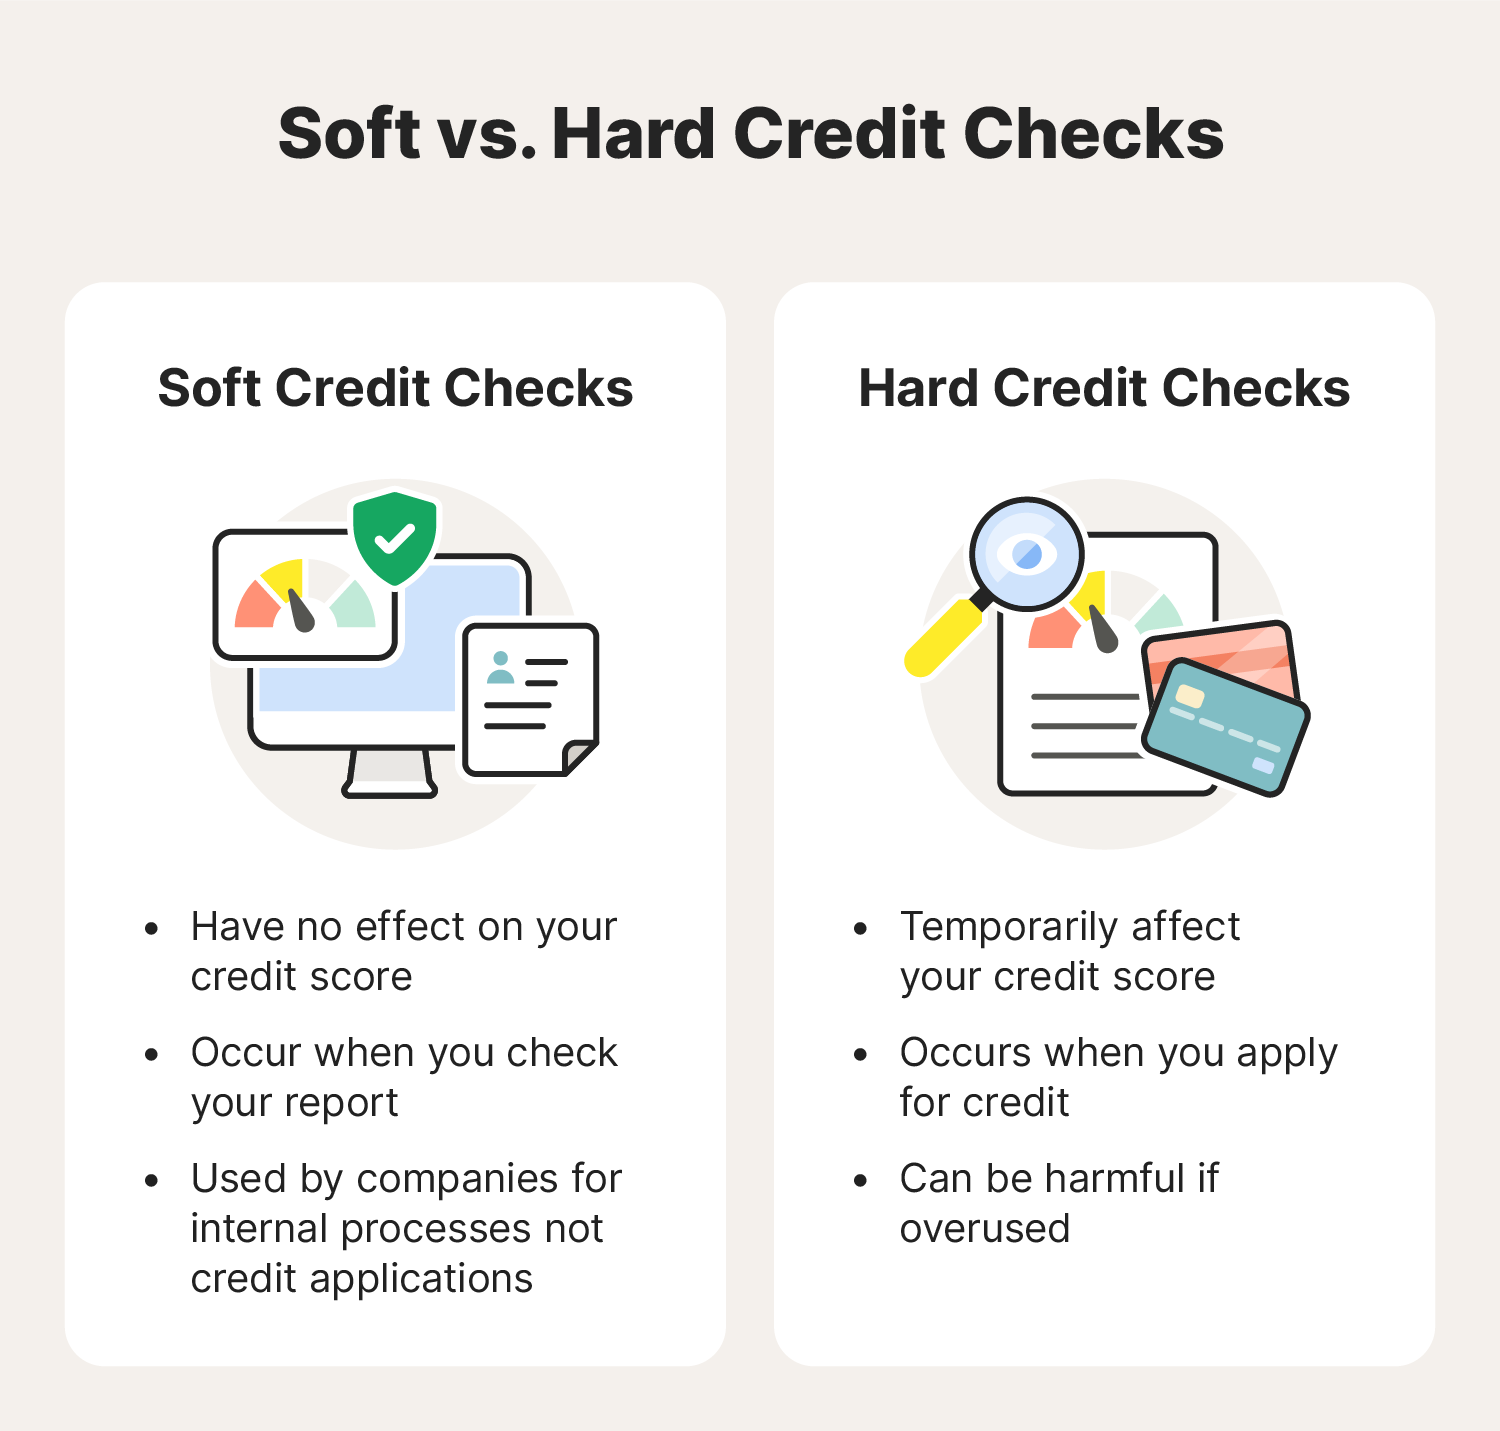
A single hard credit check, also known as a hard inquiry, typically reduces your FICO credit score by fewer than five points. While the inquiry remains visible on your credit report for 24 months, its impact on your score is temporary and usually stops affecting your credit calculation after 12 months.
In the 2026 financial landscape, understanding the nuance of credit inquiries is more critical than ever. As lenders increasingly utilize sophisticated AI-driven models to assess risk, the "New Credit" category—which includes hard inquiries—remains a stable but often misunderstood component of your financial profile. While a five-point drop might seem negligible to a borrower with a high score, those on the cusp of a higher credit tier must manage these inquiries with precision.
Understanding the Hard Credit Check
A hard credit check occurs when a financial institution, such as a lender or credit card issuer, requests to view your credit report from one of the three major credit bureaus (Equifax, Experian, or TransUnion) to make a lending decision. This typically happens when you apply for a mortgage, an auto loan, a student loan, or a new credit card.
Unlike soft inquiries, which are used for background checks or pre-approved offers, a hard inquiry indicates that you are actively seeking to take on new debt. Because statistical data shows that consumers who frequently apply for new credit are at a higher risk of default, the credit scoring models—primarily FICO and VantageScore—adjust your score downward to reflect this increased risk.
The Role of Consent in Hard Inquiries
Under the Fair Credit Reporting Act (FCRA), a lender must have a "permissible purpose" to pull your credit report. In almost every consumer scenario, this involves you providing explicit consent by submitting a formal application for credit. It is vital to recognize that your signature on a loan application serves as authorization for the lender to perform this check. In 2026, digital applications often include a mandatory checkbox that constitutes this legal authorization, making it easier for consumers to trigger a hard pull without fully realizing the immediate scoring consequences.
The Numerical Impact: How Many Points Will You Lose?
For the vast majority of consumers, a single hard inquiry will result in a drop of between one and five points. However, this is not a universal rule; the exact impact depends heavily on your unique credit profile.
Why the Impact Varies
Credit scoring is a holistic process. If you have a long credit history, multiple types of accounts, and a high score, a single hard inquiry might not move the needle at all. Conversely, a borrower with a "thin file"—someone with only one or two accounts or a very short credit history—may see a more significant drop because each new action carries more weight in the absence of a long-term track record.
Furthermore, if you have multiple hard inquiries within a short period, the impact can compound. While one inquiry is a minor blip, five inquiries in three months can signal to lenders that you are in a "credit hunger" phase, perhaps due to financial instability. This can lead to a more substantial cumulative point loss and may even lead to automatic rejections from certain high-tier lenders.
Hard Inquiry vs. Soft Inquiry: Key Differences
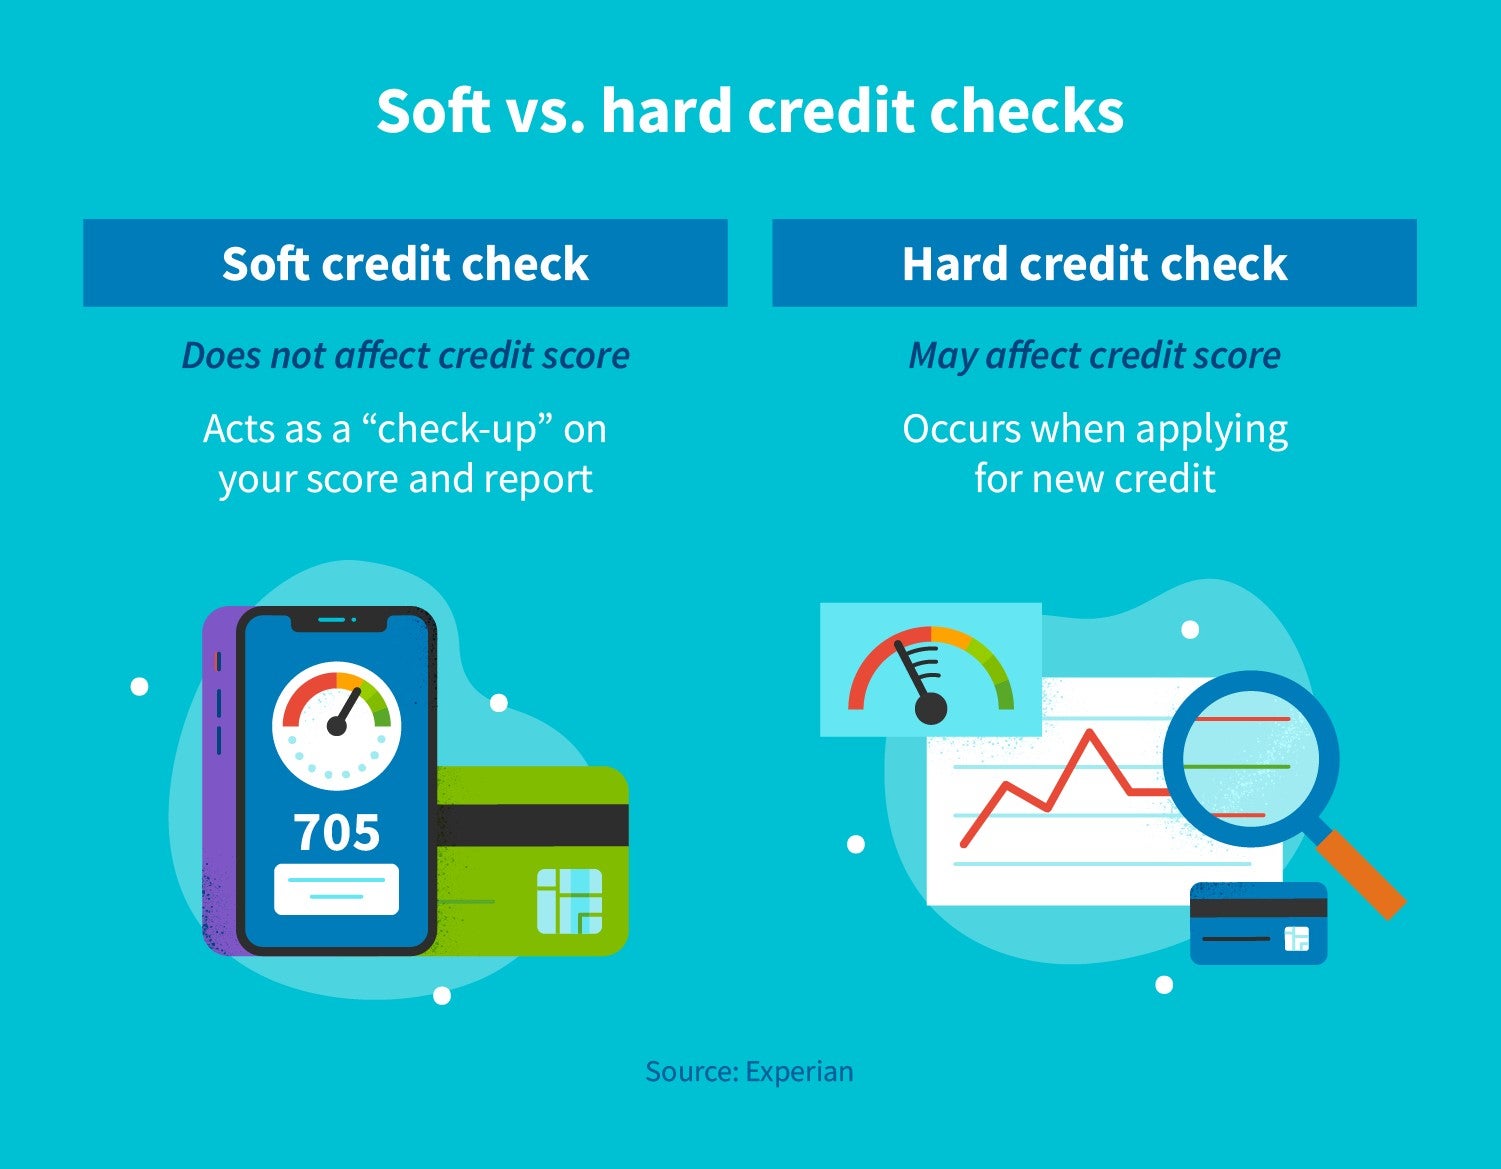
It is essential to distinguish between the two types of credit pulls, as only one affects your score. In 2026, many fintech platforms offer "soft pull" pre-approvals, allowing you to see your potential rates without any damage to your score.
| Feature | Hard Inquiry | Soft Inquiry |
|---|---|---|
| Primary Purpose | Lending decisions (Mortgages, Auto, Cards) | Pre-approvals, Identity verification, Background checks |
| Credit Score Impact | Usually -1 to -5 points | No impact |
| Visibility to Lenders | Visible to all lenders for 24 months | Visible only to you on your report |
| User Consent | Explicitly required via application | Often occurs automatically (e.g., promotional offers) |
| Common Examples | Credit card application, Mortgage application | Checking your own score, Employer background check |
The Duration of a Hard Inquiry on Your Report
A hard inquiry has two different "lifespans" that you must understand to manage your credit effectively:
- The Scoring Lifespan (12 Months): FICO and VantageScore models typically only factor hard inquiries into your credit score for the first 12 months. After one year, the inquiry is still listed on your report, but it no longer carries the weight that pulls your score down.
- The Reporting Lifespan (24 Months): According to the Fair Credit Reporting Act, credit bureaus are permitted to list hard inquiries for two years. Lenders who view your report during this second year can see that you applied for credit elsewhere, even if the inquiry is no longer affecting your numerical score.
This distinction is important for 2026 borrowers who are planning major life purchases. If you are planning to apply for a mortgage in 2027, any hard pulls you accumulate in early 2026 will be completely irrelevant to your score by the time you sit down with a loan officer.
The "Rate Shopping" Exception
The credit scoring models recognize that savvy consumers compare rates for major purchases. If you apply for a mortgage with five different lenders in a single week, the algorithms are designed not to penalize you five separate times. This is known as "rate shopping."
How Rate Shopping Windows Work
When you apply for a mortgage, auto loan, or student loan, the scoring models group all inquiries of the same type into a single event for scoring purposes, provided they occur within a specific timeframe.
- FICO Score: Depending on the version of the FICO score the lender uses, the window is typically 14 to 45 days.
- VantageScore: This model generally uses a 14-day window for all inquiry types, including credit cards, though grouping credit card inquiries is less common in older FICO models.
Note: The rate shopping exception does not apply to credit cards. Every time you apply for a different credit card, it will count as a separate hard inquiry, even if you do it on the same day.
Why Inquiries Affect Your Score: The Statistical Risk
To understand why a hard check matters, you must understand the "New Credit" category of your credit score, which accounts for approximately 10% of your total FICO score. This category evaluates how many new accounts you have opened and how many inquiries you have made.
From a lender's perspective, a sudden spike in credit applications is a red flag. Historical data from the Consumer Financial Protection Bureau (CFPB) suggests that individuals with six or more inquiries on their credit reports are significantly more likely to declare bankruptcy or fall into serious delinquency compared to those with no inquiries. Even if your intentions are purely to find a better rewards card, the algorithm interprets the behavior as a potential search for emergency liquidity.
Strategies to Minimize the Impact of Hard Checks
While hard checks are an unavoidable part of modern finance, you can manage them strategically to keep your score as high as possible.
1. Use Soft-Pull Pre-Qualification Tools
In 2026, most major credit card issuers and personal loan providers offer a "check your rate" feature. This uses a soft inquiry to determine your eligibility. Only after you accept the offer and submit the formal application does a hard pull occur. Always use these tools first to ensure you are likely to be approved before risking a hard check.
2. Space Out Your Applications
If you are building or repairing credit, avoid applying for multiple credit cards at once. A good rule of thumb is to wait at least six months between credit card applications. This allows the impact of the previous inquiry to fade and demonstrates to lenders that you are managing your credit responsibly rather than desperately seeking more.
3. Plan Major Purchases in Advance
If you know you will be applying for a mortgage or a large auto loan in the next six to twelve months, avoid opening any other new lines of credit. Even a small drop in your score from a retail store card could potentially push you into a lower "pricing tier" for your mortgage, which could cost you thousands of dollars in interest over the life of the loan.
4. Consolidate Your Shopping
When shopping for an auto or mortgage loan, do all your applications within a two-week window. This ensures you stay within the strictest "rate shopping" windows and that all the inquiries are treated as a single event by the credit scoring models.
How to Dispute Unauthorized Hard Inquiries
Occasionally, a hard inquiry may appear on your report that you did not authorize. This could be a result of a clerical error by a lender or, more seriously, a sign of identity theft.
If you find an inquiry you don't recognize:
- Verify the Source: Sometimes a company uses a different name for their credit reporting (e.g., a furniture store might use a third-party bank).
- Contact the Lender: Ask them to provide proof of your authorization. If they cannot, they are legally required to request the removal of the inquiry from the credit bureaus.
- File a Dispute: You can file a dispute directly with Equifax, Experian, or TransUnion. Under 2026 regulations, the bureaus must investigate and respond within 30 to 45 days.
- Place a Fraud Alert: If you suspect identity theft, place a fraud alert or a credit freeze on your files via the FTC identity theft portal.
Frequently Asked Questions
Does checking my own credit score count as a hard check?
No. Checking your own credit score is considered a soft inquiry. Whether you use a free service like Credit Karma, your bank's mobile app, or a paid service from myFICO, your score will not be affected. You can check your own credit as many times as you like without penalty.
Can a hard check be removed before the two-year limit?
Generally, no. If the inquiry was authorized and accurate, it must remain on your report for the full 24 months as a factual record of your credit-seeking activity. Only unauthorized or fraudulent inquiries can be removed through the dispute process.
Why did my score drop more than five points after an inquiry?
While the inquiry itself usually accounts for a small drop, the opening of a new account can cause a larger secondary drop. When a new account is added to your report, it lowers the "average age of accounts" (15% of your score) and may temporarily increase your perceived risk. The combination of the hard pull and the new account is what leads to a more noticeable decline.
Do utility and cell phone applications require a hard check?
In 2026, many utility companies and mobile service providers still perform a credit check before allowing you to open an account or finance a new device. While some have moved to soft pulls, many still perform hard inquiries. It is always wise to ask the representative which type of pull they will perform before giving your consent.
Will a hard inquiry affect my chances of getting a job?
No. While some employers perform background checks that include a credit report, these are always soft inquiries. Employers do not see your credit score, nor do their checks affect it. They are looking for signs of financial distress or history that might affect your suitability for roles involving financial responsibility, but they do not see your "hard" lending inquiries.
Final Recommendation
To minimize the impact of hard credit checks, adopt a "surgical" approach to credit applications. In 2026, data is the most valuable currency; don't give yours away through haphazard applications. Use soft-pull tools to verify eligibility, group your mortgage or auto loan shopping into a 14-day window, and allow at least six months between credit card applications. By understanding that a hard inquiry is a temporary 12-month factor, you can time your financial moves to ensure your score is at its peak when you need it most.
Image Gallery
Select an image to open it in a new tab.


Vivian Cho
Executive IT and Emerging Technologies Reporter
