
Determining the correct amount of life insurance requires a comprehensive analysis of immediate financial obligations, long-term income replacement, and future legacy goals. By utilizing a "pro" level needs-analysis approach, individuals can move beyond simple "rules of thumb" to create a mathematically sound strategy that accounts for inflation, debt liquidation, and the specific needs of surviving family members in 2026.
The Shift from Simple Ratios to Comprehensive Needs Analysis
For decades, the standard advice for life insurance was to simply multiply one’s annual salary by ten. While this provided a baseline, it rarely accounted for the nuances of modern financial lives. In 2026, with the rising costs of higher education and the complexities of multi-generational households, a more surgical approach is required. Professional financial planning software, often referred to as "Money Guide" style tools, prioritizes a "needs-based" calculation over simple ratios.
The core philosophy of a professional-grade calculation is to identify the "capital gap." This is the difference between the total financial resources your family will need over their lifetimes and the assets you currently have available. If you were to pass away today, your life insurance policy is the bridge that closes this gap.
Why the 10x Rule Often Fails
The 10x salary rule fails because it does not distinguish between a 30-year-old with three toddlers and a 55-year-old whose mortgage is nearly paid and whose children have graduated. The younger individual likely needs 20x or 30x their income to cover decades of future expenses, while the older individual might only need 5x to bridge the gap to retirement. Professional calculations factor in the "time-to-dependency," which is the number of years your beneficiaries will rely on your economic output.
The DIME Method: A Professional Starting Point
One of the most reliable frameworks used by financial professionals to organize a needs analysis is the DIME formula. This acronym stands for Debt, Income, Mortgage, and Education. Using this as a foundation allows you to categorize your family's future requirements clearly.
1. Debt (Total Non-Mortgage Obligations)
This category includes everything from credit card balances and car loans to private student loans and personal lines of credit. In a professional calculation, you should also include "final expenses." As of 2026, the average cost of a funeral, burial, and associated legal administrative fees for an estate ranges between $12,000 and $18,000. Ensuring these are covered immediately prevents your family from having to dip into daily operating funds during a period of grief.
2. Income Replacement
This is the most critical and complex part of the calculation. You are not just replacing a paycheck; you are replacing the purchasing power of that paycheck. Professional guides suggest calculating how many years your family will need support. For example, if you earn $100,000 and want to provide support until your youngest child is 22 (and they are currently 2), you are looking at a 20-year window.
However, you must account for the fact that a surviving spouse may eventually return to the workforce or receive Social Security survivor benefits. A "pro" calculation typically assumes a 60% to 80% income replacement rate, as the deceased individual’s personal expenses (food, clothing, travel) are removed from the family budget.
3. Mortgage Liquidation
For most families, the mortgage is the largest recurring expense. Eliminating this debt provides an immediate "income" to the family by removing the monthly principal and interest payment. When calculating life insurance needs, the current payoff balance—not the original loan amount—should be used. In 2026's housing market, where many homeowners hold low-interest-rate mortgages from previous years, some advisors suggest not paying off the mortgage if the insurance proceeds can be invested at a higher rate of return. However, for most, the security of a debt-free home remains the primary goal.
4. Education Funding
Education costs continue to outpace general inflation. A professional guide requires you to estimate the future cost of college for each child. This includes tuition, room, board, and supplies. If you have three children, and the projected cost of a four-year degree at a state university in 2026 is approximately $120,000 per child, you must add $360,000 to your total insurance need.

The Human Life Value (HLV) Approach
While the DIME method is goal-oriented, the Human Life Value (HLV) approach is economic-oriented. This method calculates the total earnings an individual is expected to produce during their remaining working years, minus taxes and personal consumption, and then discounts that total to "present value."
In 2026, the HLV is particularly useful for high-earning professionals whose families have lifestyle expectations tied to future promotions and bonuses. The formula looks like this:
- Total Annual Earnings: Include salary, bonuses, and employer contributions to retirement plans.
- Deductions: Subtract income taxes, Social Security taxes, and the individual's personal maintenance costs.
- Remaining Work Life: Number of years until planned retirement.
- Discount Rate: A professional advisor uses a discount rate (often 3% to 5%) to determine how much a future dollar is worth today.
This approach ensures that the insurance benefit is large enough that, if invested, it could replicate the deceased’s net earnings for the rest of their career.
Accounting for Existing Assets and "Blackout Periods"
A professional-grade calculation is not just about what you need, but also about what you already have. You must subtract your current liquid and semi-liquid assets from your total "needs" sum to find the actual insurance requirement.
Social Security Survivor Benefits
Many people overlook the role of the Social Security Administration (SSA). If you have minor children, they and your surviving spouse may be eligible for monthly survivor benefits. These benefits can significantly reduce the amount of private life insurance needed. However, these benefits often stop when the youngest child turns 16 (for the spouse) and 18/19 (for the child), leading to a "Blackout Period" until the spouse reaches retirement age. A professional guide will map out these income gaps year-by-year.
Liquid Assets
Include the following in your subtractions:
- Current life insurance policies (especially individual policies, as employer-sponsored coverage is often lost if you change jobs).
- Savings and checking account balances.
- Brokerage accounts.
- Retirement accounts (401k, IRA), though these should be handled carefully due to potential tax implications upon withdrawal.
Comparing Professional Calculation Methods
The following table compares three common methodologies used by financial planners to determine the appropriate death benefit.
| Method | Primary Focus | Best For | Complexity |
|---|---|---|---|
| Simple Multiplier | Annual Income | Quick estimates and "baseline" checks. | Low |
| DIME Formula | Specific Obligations | Families with high debt and young children. | Moderate |
| Needs Analysis (Capital Gap) | Comprehensive Cash Flow | Complex estates with diverse assets and goals. | High |
| Human Life Value (HLV) | Economic Worth | High-earners and those in their peak earning years. | High |
Technical Considerations: Inflation and Taxability
In 2026, ignoring inflation is a critical error in life insurance planning. If you determine your family needs $5,000 a month today, that same $5,000 will have significantly less purchasing power in fifteen years. Professional guides apply a 2% to 3% inflation adjustment to future income needs.
Furthermore, while life insurance death benefits are generally received income-tax-free under Internal Revenue Code Section 101(a), the earnings on those proceeds (if invested) are taxable. If your family receives a $2 million payout and invests it, they will owe taxes on the dividends and capital gains. A professional "Money Guide" approach factors in this "tax drag" to ensure the net income remains sufficient.
Common Pitfalls to Avoid in Your Calculations
- Underestimating the Value of a Stay-at-Home Parent: If a non-working spouse passes away, the surviving working spouse will face massive increases in childcare, housekeeping, and transportation costs. A professional guide assigns a "replacement value" to these services, often requiring $500,000 to $1 million in coverage for the stay-at-home parent.
- Relying Solely on Group Life Insurance: Most employers provide 1x or 2x salary in coverage. This is a "perk," not a plan. If you are diagnosed with a terminal illness and lose your job, you often lose this coverage exactly when you need it most.
- Forgetting the "Finality" of Term Insurance: If you buy a 20-year term policy to cover your mortgage, but then refinance to a new 30-year mortgage ten years later, you will have a 10-year gap where your mortgage is unprotected.
- Neglecting Estate Taxes: For very high-net-worth individuals, the death benefit itself could increase the size of the estate to a point where it triggers federal or state estate taxes. In such cases, professional advisors use Irrevocable Life Insurance Trusts (ILITs) to keep the proceeds outside the taxable estate.
Professional Tools and Resources
While you can perform a basic needs analysis on paper, utilizing tools that align with the FINRA (Financial Industry Regulatory Authority) standards or Life Happens, a non-profit organization dedicated to insurance education, can provide more accuracy. These organizations offer calculators that mirror the logic used by "Money Guide Pro" software, accounting for the nuances of 2026 tax law and economic projections.
Frequently Asked Questions
1. How often should I recalculate my life insurance needs?
Financial professionals recommend a review every three years or whenever a "major life event" occurs. These events include marriage, divorce, the birth or adoption of a child, a significant change in income, or the purchase of a new home. In 2026, given the volatility of the economy, an annual "check-up" is often preferred to ensure inflation hasn't rendered your current coverage inadequate.
2. Should I include my 401(k) or IRA when subtracting assets?
Yes, but with caution. Retirement assets are intended for your own retirement. If your spouse uses those funds to pay off a mortgage today, they may face a massive shortfall in their own senior years. Most professional guides recommend leaving retirement assets out of the "subtraction" phase to ensure the surviving spouse remains on track for their own retirement.
3. Does a "Pro" calculation favor Term or Whole Life insurance?
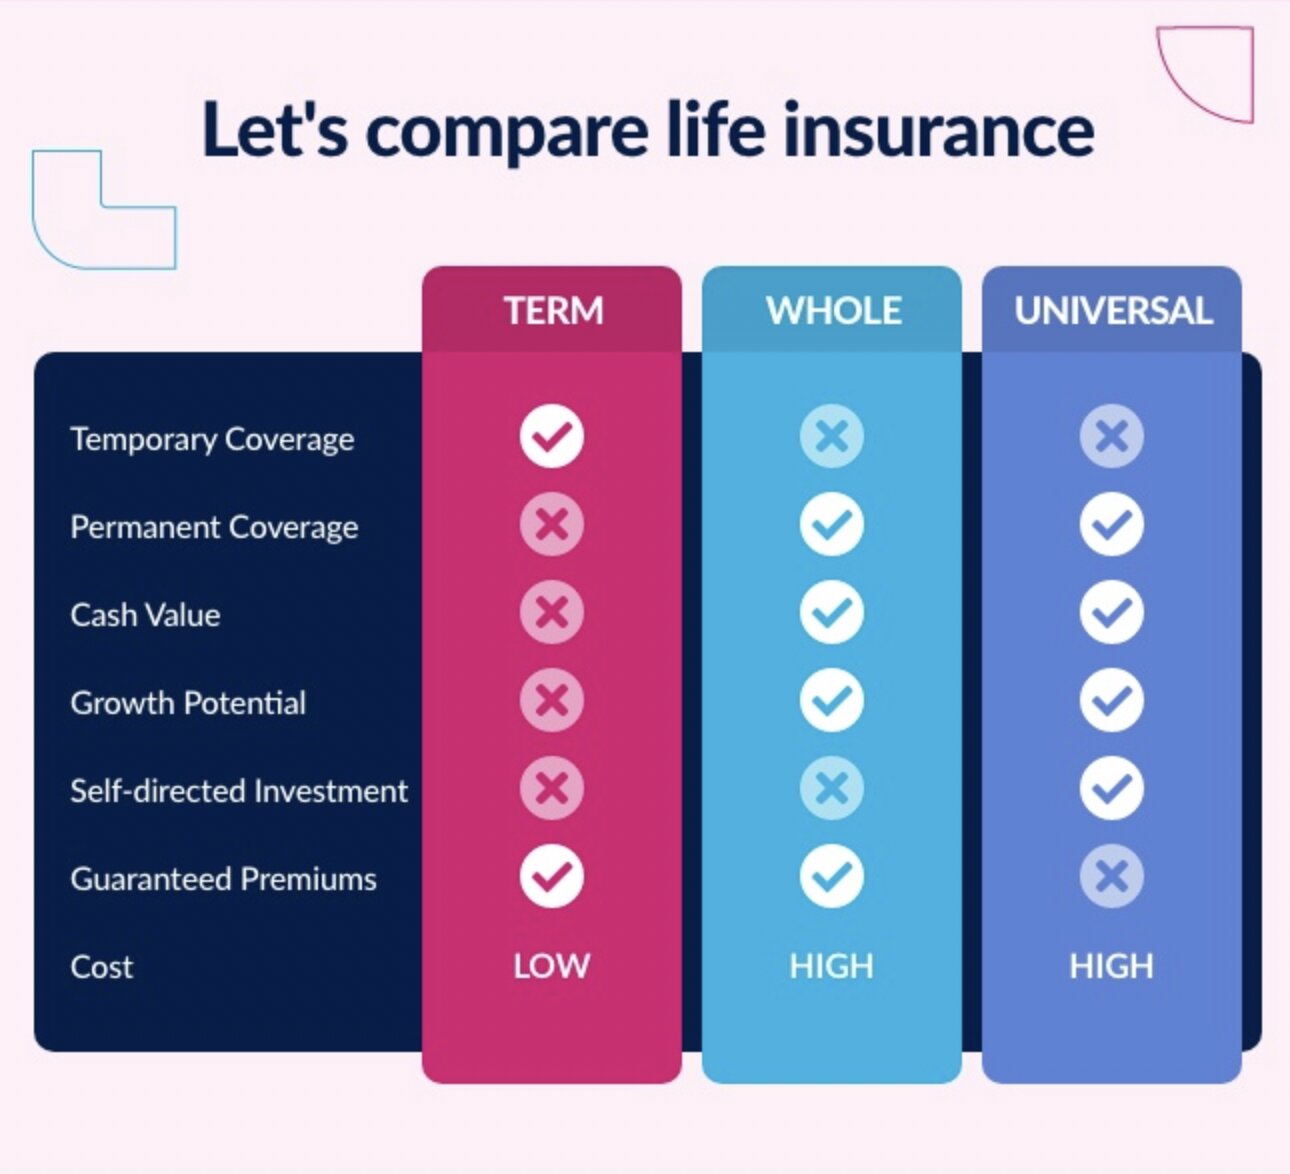
A professional calculation is product-agnostic; it tells you how much you need, not what kind. Generally, term insurance is used to cover temporary needs (mortgage, children’s education), while permanent insurance (Whole Life or Universal Life) is used for permanent needs (estate taxes, final expenses, or lifelong dependents). Most "Money Guide" style plans result in a "laddered" approach using both.
4. How do interest rates in 2026 affect my calculation?
Interest rates are a double-edged sword. Higher rates mean that a smaller lump sum of life insurance can generate more annual income for your family. Conversely, if rates are low, you need a much larger death benefit to produce the same income stream. A professional analysis uses a conservative "expected rate of return" to ensure the family isn't left short if the market underperforms.
5. What is the "Capital Retention" vs. "Capital Liquidation" method?
Capital Retention means the family lives only on the interest generated by the insurance payout, leaving the principal intact. This requires a much larger policy. Capital Liquidation means the family spends both the interest and the principal over a set period (e.g., 30 years), eventually hitting zero. Most professional calculations use a modified liquidation approach to keep premiums affordable.
Final Recommendation: Your Next Steps
To calculate your life insurance needs like a professional in 2026, begin by documenting your total debt and the number of years your family will need income replacement. Subtract your current liquid savings and any existing individual life insurance policies. Because of the complexities of inflation, Social Security blackout periods, and tax implications, it is highly recommended to use a professional-grade needs-analysis calculator or consult with a Certified Financial Planner (CFP) who can run a Monte Carlo simulation. This ensures that your coverage amount is not just a guess, but a mathematically verified safety net for your family's future.
Image Gallery
Select an image to open it in a new tab.
Declan O'Connor
Higher Education and Campus Culture Reporter
