When purchasing a vehicle in New York, the sales tax is calculated based on the combined state and local tax rates of the county where the buyer resides, typically ranging from 7.00% to 8.875% of the vehicle’s purchase price. This tax is paid directly to the Department of Motor Vehicles (DMV) when registering the car, and it applies to both dealership purchases and private sales, with specific rules governing trade-ins, manufacturer rebates, and out-of-state acquisitions.
Understanding the true cost of purchasing a vehicle involves looking past the sticker price to account for state levies, local municipal surcharges, and administrative fees. For residents of New York State, navigating the automotive sales tax system requires careful attention to geographic location, transaction type, and statutory exemptions. Whether you are buying a brand-new sedan from a franchise dealership in Westchester County or purchasing a used pickup truck from a private seller in Erie County, the final financial obligation is determined by a precise legislative formula. This guide breaks down every variable affecting car sales tax in New York to help you accurately forecast your total vehicular expenses.
The Core Formula: How New York State Calculates Vehicle Sales Tax
At its foundational level, New York State imposes a baseline 4.0% state sales tax on most retail purchases, including motor vehicles. However, the calculation does not stop there. Local jurisdictions—including counties and certain cities—levy their own additional sales taxes. When combined, the state and local tax rates create the final percentage applied to your vehicle purchase.
To determine what the sales tax on a car in New York costs, you must identify the exact municipality where you maintain your permanent residence (your tax jurisdiction), not necessarily the location where you bought the vehicle. For example, if you live in New York City, the combined state and local sales tax rate is a flat 8.875% (4.0% state tax plus 4.875% New York City local tax). If you live in a different county, such as Monroe County, the combined rate sits at 8.0%.
The mathematical formula is straightforward:
$$\text{Total Sales Tax} = \text{Taxable Purchase Price} \times (\text{State Tax Rate} + \text{Local Tax Rate})$$
If you purchase a car for $30,000 in a jurisdiction with an 8.0% total tax rate, your baseline tax calculation yields $2,400. However, determining the exact "Taxable Purchase Price" involves several statutory adjustments, including trade-in allowances and manufacturer incentives, which can lower your overall out-of-pocket tax burden.
Geographic Variations: New York State Sales Tax Rates by Region
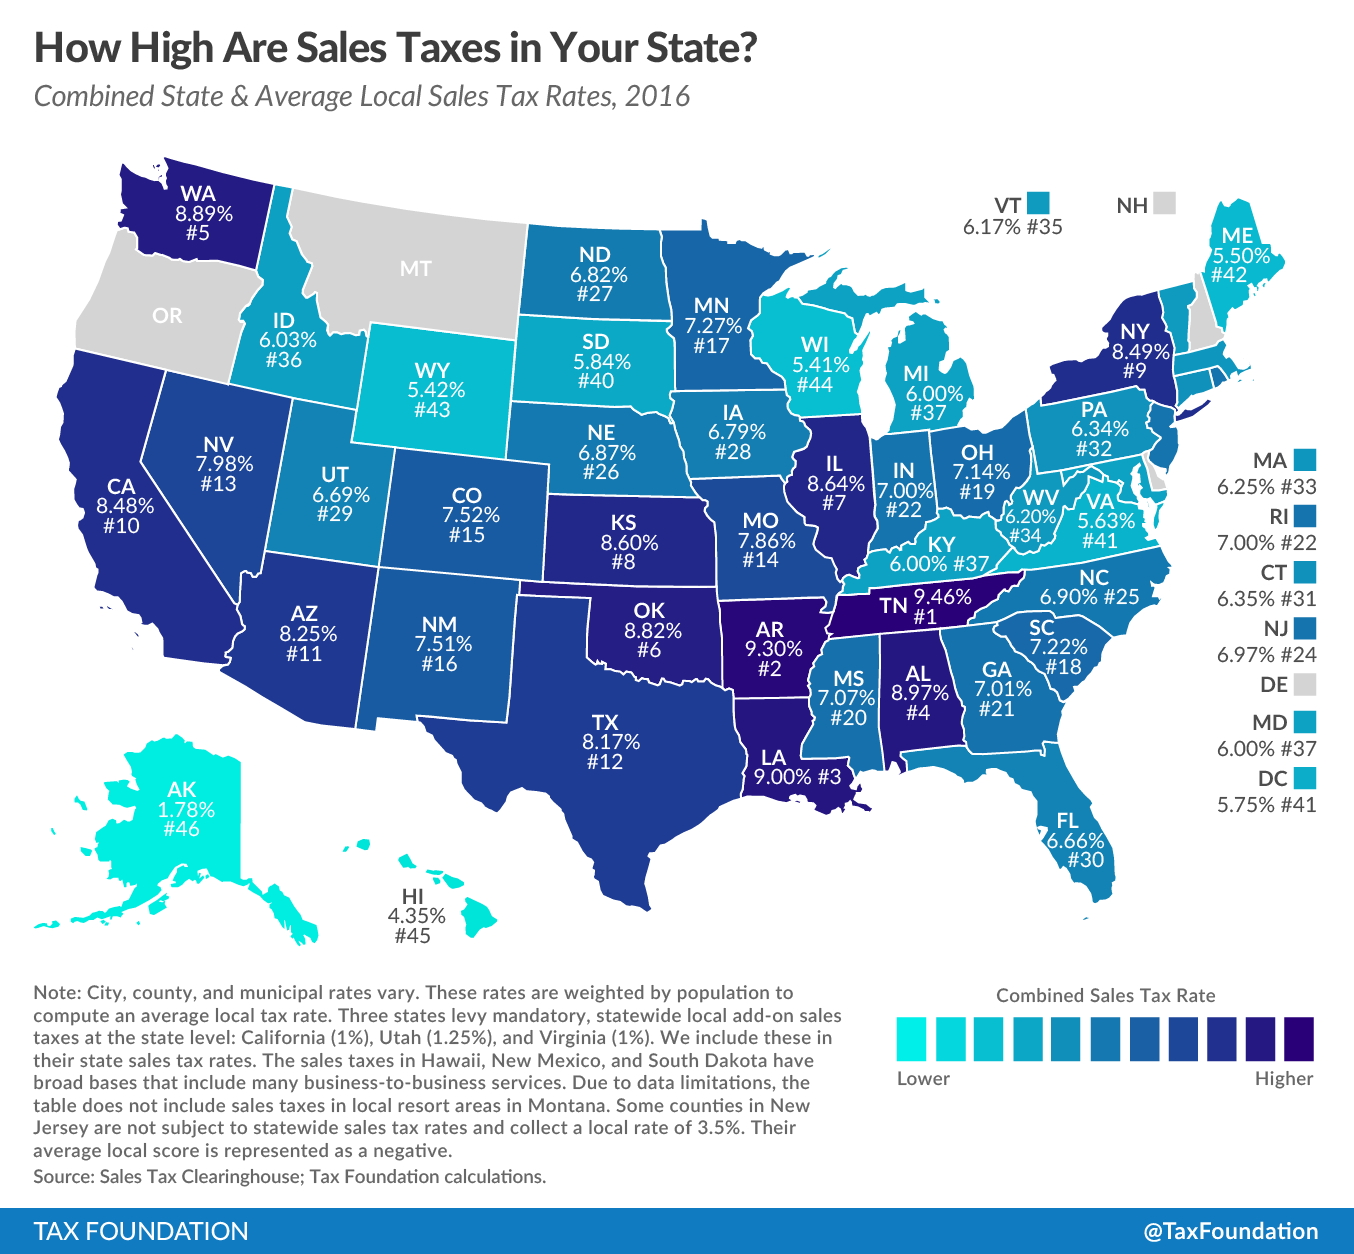
Because local county and municipal governments set their own tax additions, the sales tax rate varies significantly across the state. The table below illustrates the combined state and local sales tax rates for select major counties and municipalities across New York.
| County or Municipality | State Tax Rate | Local Tax Rate | Combined Sales Tax Rate |
|---|---|---|---|
| New York City (All 5 Boroughs) | 4.0% | 4.875% | 8.875% |
| Westchester County | 4.0% | 3.375% | 7.375% |
| Nassau County | 4.0% | 4.625% | 8.625% |
| Suffolk County | 4.0% | 4.625% | 8.625% |
| Erie County | 4.0% | 4.750% | 8.750% |
| Monroe County | 4.0% | 4.000% | 8.000% |
| Albany County | 4.0% | 4.000% | 8.000% |
| Onondaga County | 4.0% | 4.000% | 8.000% |
When budgeting for a vehicle, always verify the current local tax rate associated with your specific ZIP code through the New York State Department of Taxation and Finance to avoid underestimating your registration costs at the DMV.
Dealership Purchases Versus Private Sales
The method by which you acquire your vehicle directly influences how and when sales tax is collected, though the percentage rate remains tied to your home address.
Buying from a Licensed Dealership
When you purchase a vehicle from a licensed New York dealership, the dealer is legally authorized—and typically required—to collect the sales tax and DMV registration fees directly at the point of sale. The dealership handles the paperwork, submits the sales tax to the state, and issues temporary plates while processing your permanent registration.
- The Advantage: The process is streamlined, ensuring you do not have to calculate the tax manually or visit the DMV office separately to pay it before driving off the lot.
- Itemization: On your purchase invoice, look closely at the line items. Dealership documentation fees, electronic filing fees, and registration costs are separate from the sales tax and are not subject to the vehicle sales tax percentage.
Buying from a Private Seller
When purchasing a used car from a private individual, the transaction does not include automatic tax collection at the point of exchange. Instead, you must pay the sales tax directly to the DMV when you bring the paperwork in to register the vehicle in your name.
- Required Documentation: To calculate the tax, you and the seller must complete Form DTF-802 (Statement of Transaction - Sale or Gift of Motor Vehicle). Both parties must sign this form, certifying the actual purchase price.
- The Fair Market Value Rule: The New York State Department of Taxation and Finance cross-references reported private sale prices against the average retail value of the vehicle (often referenced via standard valuation guides like the National Automobile Dealers Association pricing). If you report a purchase price significantly below fair market value—or claim you bought the car for $1—the DMV and tax authorities will not simply accept it. Unless you can prove the vehicle suffered severe mechanical damage or structural defects (supported by repair estimates or salvage titles), the sales tax will be calculated based on the official fair market value rather than your bargain purchase price.
Adjustments that Lower Your Taxable Base
Fortunately, New York State law allows for certain deductions that reduce the total amount upon which your sales tax is calculated. Understanding these rules can save buyers hundreds or thousands of dollars.
Trade-In Allowances
If you trade in your old vehicle to a licensed dealer as part of the purchase of a new or used car, New York State allows a trade-in tax credit. The trade-in value of your old vehicle is subtracted from the purchase price of the new vehicle before the sales tax is calculated.
- Example: If you buy a $35,000 car and receive a $10,000 trade-in allowance for your old vehicle, your sales tax is calculated on the net difference of $25,000. Assuming an 8.0% tax rate, this saves you $800 in cash compared to a standard transaction without a trade-in.
- Private Sale Limitation: Note that trade-in tax credits generally only apply to transactions handled through registered dealers. Selling your car privately and buying another car privately does not yield the same localized tax netting unless structured through specific dealer-assisted trade-in programs.
Manufacturer Rebates and Incentives
How manufacturer rebates affect sales tax depends entirely on who issues the discount and how the transaction is structured.
- Manufacturer Rebates (Cash Back): If a manufacturer offers a cash rebate that is applied directly as a down payment or price reduction at the time of purchase, New York tax law typically treats this as a reduction of the sales price. Consequently, you pay sales tax on the discounted price after the rebate is deducted.
- Dealer Discounts: Discounts provided directly by the dealership also reduce the taxable purchase price.
Special Circumstances: Out-of-State Purchases, Gifts, and Military Exemptions
Certain non-standard vehicle acquisitions require careful application of New York tax guidelines to ensure compliance and avoid double taxation.
Out-of-State Purchases
If you live in New York and purchase a vehicle from a dealer in another state (such as New Jersey, Connecticut, or Florida), you are still subject to New York State and local sales tax based on your New York residence.
- Credit for Taxes Paid Elsewhere: If you paid sales tax to another state at the time of purchase, New York allows a credit for that tax, provided it was legally required and paid to that state. If the out-of-state tax rate was lower than your New York local rate, you will owe the difference to the New York DMV upon registration. If the other state's tax rate was higher, New York will not refund the difference, but you will not owe additional state tax.
Vehicle Gifts
Transferring a vehicle as a gift within New York State can exempt the recipient from paying sales tax, but strict evidentiary rules apply.
- Immediate Family Exception: Exemption from sales tax is typically granted if the vehicle is transferred as a gift between spouses, parent and child, sibling, or grandparent and grandchild.
- Form Requirements: To claim this exemption, the parties must submit Form DTF-802, properly checking the gift box, and provide proof of relationship if requested. If the vehicle is gifted by a non-family member, sales tax must be paid based on the vehicle's current fair market value.
Military Personnel Exemptions
Active-duty military personnel stationed in New York who are legal residents of another state often enjoy specific tax relief regarding motor vehicle purchases, governed by the Servicemembers Civil Relief Act (SCRA) and New York tax codes. Non-resident military members should consult local base legal assistance offices or the Department of Taxation and Finance to verify their precise exemption status when registering vehicles acquired during service.
Common Mistakes to Avoid When Calculating and Paying New York Car Tax
Navigating state and local tax laws involves several pitfalls that can lead to unexpected expenses, registration delays, or audits by the tax department.
- Failing to Account for Local Surcharges: Many buyers look only at the 4.0% state tax rate and are shocked when their DMV bill includes local county surcharges that push the total past 8.0%. Always calculate using your exact county-level combined rate.
- Underreporting Purchase Prices on Private Sales: Attempting to evade sales tax by writing an artificially low price on a bill of sale for a private transaction is illegal. The New York Department of Taxation and Finance routinely audits vehicle registrations with disparate values, resulting in back taxes, interest, and statutory penalties.
- Forgetting Document and Registration Fees in the Upfront Cash Budget: Sales tax is only one component of the mandatory fees due at registration. Buyers must also budget for title fees, license plate fees, and inspection fees, which vary depending on vehicle weight and type but add separate costs to the ledger.
- Misidentifying the Tax Jurisdiction: Registering a vehicle using a commercial address, a relative's address in a different county, or an outdated former address to secure a lower local tax rate constitutes tax fraud. Tax jurisdiction is determined by your primary legal residence.
Summary Checklist for New York Vehicle Buyers
To ensure a smooth purchasing and registration process while accurately accounting for New York car sales tax, follow these steps:
- Identify Your Tax Jurisdiction: Determine the exact combined state and local tax rate for your residential ZIP code.
- Review the Purchase Agreement: Ensure trade-in allowances and manufacturer rebates are properly credited to lower your taxable subtotal.
- Gather Private Sale Paperwork: If buying used from an individual, complete Form DTF-802 accurately using realistic market valuations.
- Prepare for DMV Fees: Set aside sufficient funds to pay the sales tax and mandatory administrative fees simultaneously during registration.
Image Gallery
Select an image to open it in a new tab.
Lars Thomsen
Global Labor Markets and Economic Strategy Editor
