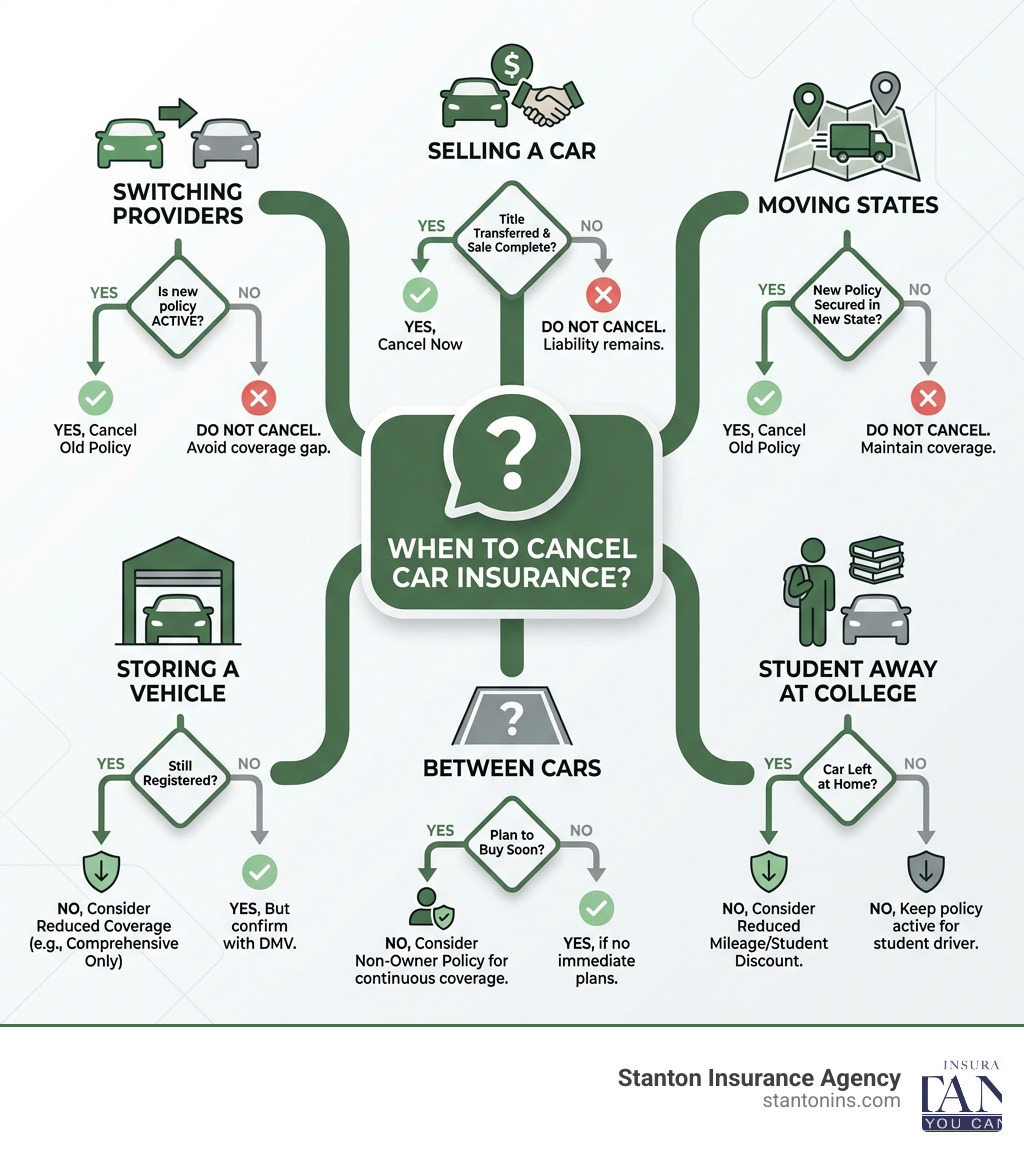
To properly cancel auto insurance, you must first secure a replacement policy to avoid a coverage lapse. Once your new coverage is active, contact your current insurer to request cancellation on a specific date, ideally matching your new policy's start date. Always obtain written confirmation and verify if any premium refunds are owed.
Navigating the cancellation of an auto insurance policy requires more than simply stopping your monthly payments. In 2026, the insurance landscape remains strictly regulated, and a mishandled cancellation can lead to significant financial and legal repercussions, including hiked premiums, state-mandated fines, or even the suspension of your driver’s license. Whether you are switching to a more affordable provider, selling your vehicle, or moving to a region with different requirements, following a structured protocol is essential to protect your "continuous coverage" status.
The Golden Rule: Avoid the Insurance Lapse
The most critical factor when canceling auto insurance is ensuring there is no gap—even for a single day—between your old policy and your new one. In the eyes of insurance carriers and state Departments of Motor Vehicles (DMV), a lapse in coverage signals a high-risk profile.
Why Lapses Are Costly
When you allow a policy to lapse, you lose your "continuous insurance" history. When you eventually apply for a new policy, insurers will often categorize you as a high-risk driver, leading to significantly higher premiums. Furthermore, most states utilize electronic verification systems that notify the DMV the moment a policy is terminated. If the state does not see a new policy on file immediately, they may flag your registration as invalid.
The Overlap Strategy
The proper way to transition is to set the effective date of your new policy to the same day as the cancellation of your old one. Some experts recommend a one-day overlap (where both policies are active) to ensure there is absolutely no room for error during the data transmission between the insurer and state databases.
Step-by-Step Process for a Proper Cancellation
Canceling a policy is a formal contractual change. While many modern insurers allow you to initiate this through a mobile app or web portal in 2026, the underlying legal requirements remain the same.
1. Research and Secure New Coverage
Before contacting your current agent, shop for a new policy. Use the National Association of Insurance Commissioners (NAIC) Consumer Insurance Search Tool to verify the reputation of any new company you are considering. Once you have selected a provider and passed their underwriting process, receive your new policy number and effective date.
2. Review Your Current Policy’s Cancellation Clause
Not all policies are created equal. Some contracts include a "cancellation fee" or a "short-rate" penalty if you cancel before the term ends. Review your policy declarations page or contact your agent to ask:
- Is there a flat fee for mid-term cancellation?
- Does the company use pro-rata or short-rate math for refunds?
- Is a written notice required, or is a phone call sufficient?
3. Contact Your Current Insurer
Notify your insurance company of your intent to cancel. You should provide them with:
- Your policy number.
- The exact date and time you want the coverage to end (e.g., 12:01 AM on the effective date).
- Your reason for canceling (this helps them code the cancellation correctly in their system).
- Proof of new insurance (if requested).
4. Request a Formal Cancellation Letter
Do not take a verbal confirmation as the final word. Request a "Cancellation Confirmation" or a "Notice of Cancellation" in writing. This document serves as your legal proof that the contract ended at your request and not due to non-payment. This distinction is vital for your future credit and insurance scores.
Understanding Refunds and Final Payments
One of the primary motivations for a proper cancellation is the recovery of "unearned premiums." If you paid your six-month or annual premium in full upfront, the insurer is legally obligated to return the portion of the premium that covers the remaining period of the policy.
Pro-Rata vs. Short-Rate Refunds
- Pro-Rata: This is the most consumer-friendly method. The insurer divides your total premium by the number of days in the term and charges you only for the days you were covered. If you cancel exactly halfway through the term, you get 50% of your money back.
- Short-Rate: Some insurers apply a penalty (often 10% of the remaining premium) for canceling early. This covers the administrative costs of processing the early termination.
The Risk of "Stopping Payment"
A common and dangerous mistake is simply canceling your "Auto-Pay" at the bank or ignoring the bill. This is not a proper cancellation. If you stop paying, the insurer will eventually cancel your policy for non-payment. A "cancellation for non-payment" stays on your insurance record for years and is a major red flag for every other carrier, often resulting in an automatic denial of coverage or a massive increase in rates.
Special Considerations for Financed or Leased Vehicles
If you do not own your car outright, the cancellation process involves a third party: the lienholder or leasing company.
Notifying the Lender
Your finance contract likely requires you to maintain specific levels of comprehensive and collision coverage. When you cancel or switch policies, your insurer is required to notify the lienholder. If you cancel without a replacement, the lender may purchase "force-placed insurance." This is a basic policy that protects the lender's interest in the car but offers you no liability protection and is significantly more expensive than a standard policy.
Minimum Coverage Requirements
When switching, ensure your new policy meets the "loss payee" requirements of your lender. Most lenders require a deductible no higher than $500 or $1,000. If your new policy has a $2,500 deductible to save money, you may be in technical default of your loan agreement.
State-Specific Requirements and the DMV
Every state has its own rules regarding the notification of insurance termination. In 2026, many states have moved to real-time digital reporting.
| State Action | Requirement Detail |
|---|---|
| Electronic Reporting | Most states require insurers to report cancellations within 24–48 hours. |
| License Plate Return | In states like New York or North Carolina, you may be required to return your license plates to the DMV before canceling the insurance if the vehicle is not being re-insured. |
| SR-22 Filings | If you have a high-risk "SR-22" or "FR-44" filing, your insurer must notify the state immediately upon cancellation. A lapse here can lead to immediate license revocation. |
| Verification Audits | Some states perform random audits. If you cannot provide proof of insurance for a specific date in the past, you may face fines exceeding $500. |
Practical Comparison of Cancellation Methods
Depending on your insurer, you may have several ways to initiate the process. Each has its pros and cons regarding speed and documentation.
| Method | Speed | Pros | Cons |
|---|---|---|---|
| Mobile App/Portal | Instant | Fast, easy to do 24/7, digital trail. | May not allow for specific nuance or fee negotiation. |
| Phone Call | Moderate | Can ask questions about refunds and fees. | Risk of "save" attempts by agents; no immediate paper trail. |
| Certified Mail | Slow | Best legal protection; provides a physical receipt of delivery. | Takes several days; feels outdated for 2026. |
| In-Person | Moderate | Direct interaction; can get a signed receipt on the spot. | Requires a trip to an agency office; limited to local agents. |
Common Scenarios for Cancellation
The "proper way" can shift slightly depending on why you are ending the coverage.
Selling the Vehicle
If you sell your car, do not cancel the insurance until the title has been legally transferred and the plates are removed. If the new owner test-drives the car or gets into an accident before the paperwork is finalized, you could still be held liable if your insurance is already defunct.
Moving Out of State
Insurance is state-specific. You cannot simply keep your old policy when you move to a new state. You must secure a policy in your new state that meets their specific minimum limits, then cancel the old policy. Ensure you also update your address with the previous insurer so they can mail your refund check.
Storing a Vehicle
If you are going on a long deployment or will not be driving for several months, do not cancel entirely. Instead, ask for "Comprehensive-Only" or "Storage Coverage." This keeps the policy active (avoiding a lapse) but removes the expensive liability and collision portions while the car is safely parked.
Frequently Asked Questions
Can I cancel my insurance at any time?
Yes, you have the legal right to cancel your auto insurance policy at any time. You do not have to wait until the end of the policy term or the renewal date. However, as noted previously, canceling mid-term may result in a "short-rate" fee depending on your carrier’s specific terms.
How long does it take to get a refund after canceling?
In 2026, most major insurers process refunds within 7 to 14 business days. If you paid via credit card, the refund is typically credited back to that card. If you paid by check or electronic fund transfer (EFT), the company may issue a paper check or a direct deposit. Always verify your current mailing address with the company before the final cancellation.
Will canceling my insurance hurt my credit score?
A proper cancellation does not affect your credit score. Insurance companies do not report policy terminations to credit bureaus unless there is an outstanding unpaid balance. However, as mentioned, "canceling by non-payment" can lead to your account being sent to a collections agency, which will severely damage your credit.
What if my insurance company cancels me first?
If an insurer initiates the cancellation (usually due to a high number of claims or a DUI), the "proper way" to handle it is to find a "non-standard" or "high-risk" insurer immediately. You usually have a 30-day notice period. Use this time to secure new coverage so there is no gap on the day their coverage ends.
Do I need to notify the DMV myself?
In most jurisdictions, the insurance company handles the notification electronically. However, it is your responsibility to ensure the state has the correct information. If you receive a "Notice of Intent to Suspend" from the DMV, you must provide them with your new policy information immediately to prove you maintained continuous coverage.
Recommendation for Next Actions
The most effective way to ensure a seamless transition is to synchronize your dates. Once you have found a new provider, call your current insurer and state: "I would like to schedule a formal cancellation of my policy effective [Date] at 12:01 AM, as I have secured alternative coverage." Follow up by logging into your online portal 48 hours later to download the formal "Notice of Cancellation" and verify the amount of your pending refund. If you are moving or selling the car, check your local DMV website specifically for "License Plate Surrender" rules to avoid an administrative fine.
Image Gallery
Select an image to open it in a new tab.
Mateo Castillo
Decentralized Finance and E-Payments Strategist
