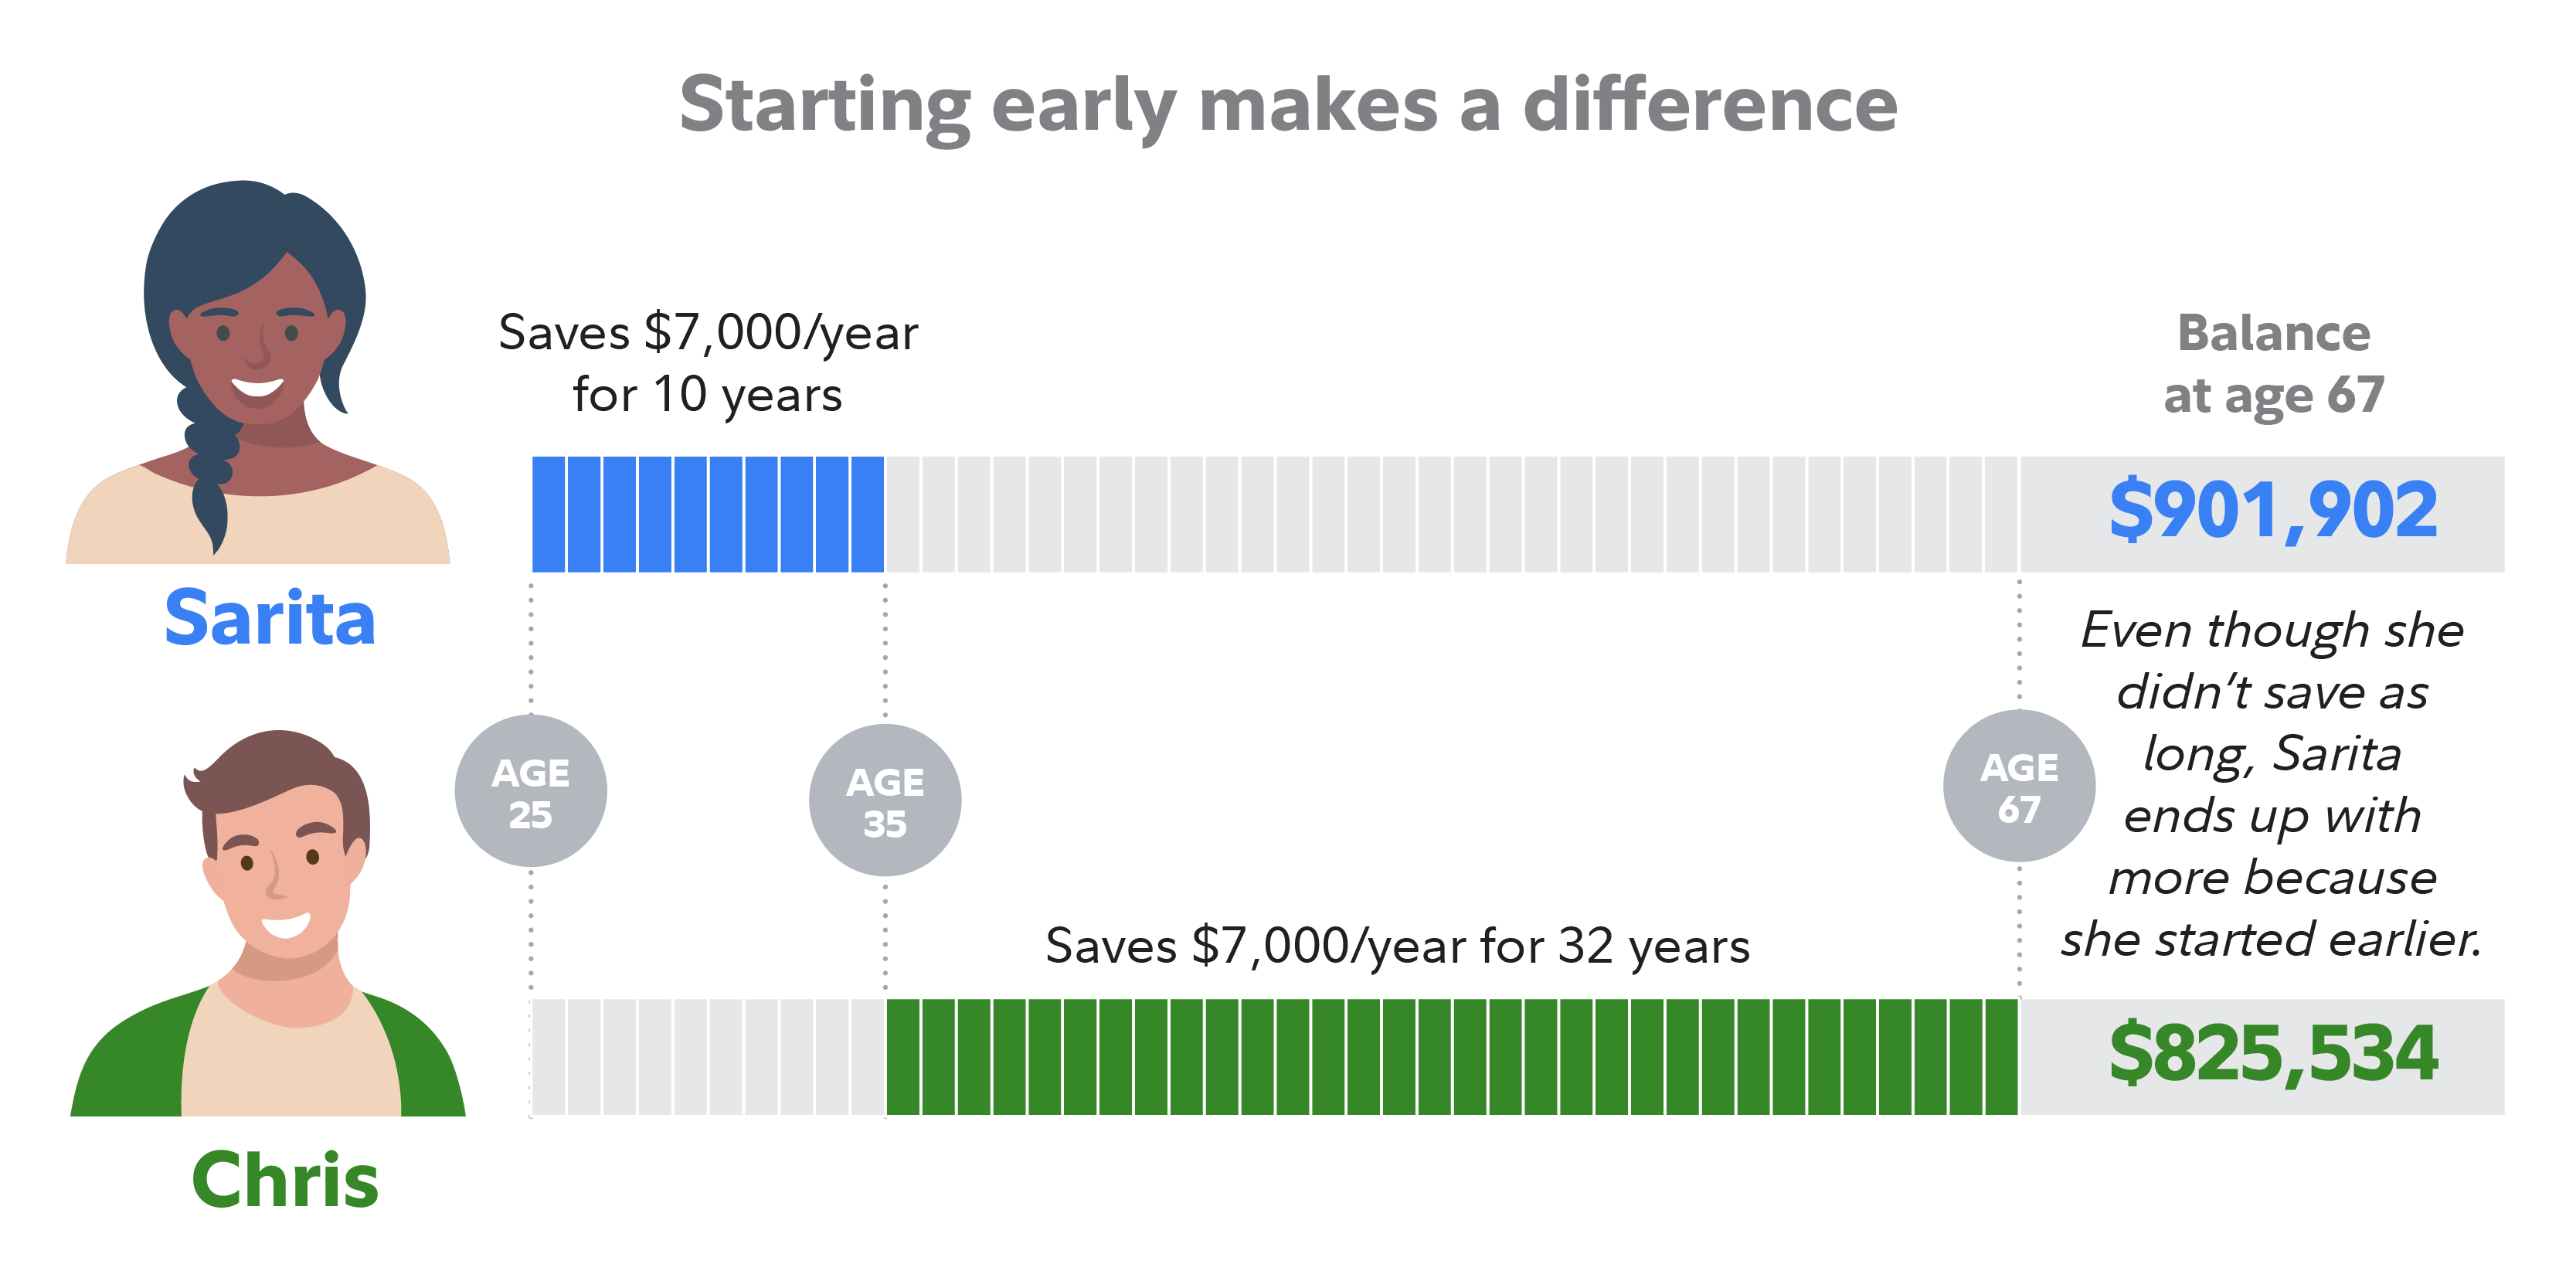
Opening an Individual Retirement Account (IRA) with Fidelity Investments is a straightforward process that allows you to start tax-advantaged saving for your retirement goals. Whether you are a beginner looking to understand the fundamentals of tax-deferred growth or a seasoned investor seeking to consolidate assets, Fidelity offers a digital-first approach to account creation. To open an account, you must provide personal identification, employment details, and tax documentation, then select the specific IRA type—Traditional, Roth, or Rollover—that best aligns with your financial strategy.
Understanding Your IRA Options at Fidelity
Before you initiate the application, it is essential to distinguish between the primary types of IRAs offered by Fidelity. Your choice will impact how your contributions are taxed and when you can access your funds without penalty.
- Traditional IRA: Contributions to a Traditional IRA are often tax-deductible in the year they are made, depending on your income level and whether you or your spouse are covered by a workplace retirement plan. Your investments grow tax-deferred, meaning you do not pay taxes on capital gains or dividends while the money remains in the account. You will pay ordinary income tax on withdrawals during retirement.
- Roth IRA: Contributions to a Roth IRA are made with after-tax dollars, meaning there is no immediate tax deduction. However, the primary benefit is that your investments grow tax-free, and qualified withdrawals during retirement are also tax-free. This is often a preferred strategy for individuals who expect to be in a higher tax bracket in the future.
- Rollover IRA: If you are leaving a job and have a 401(k) or 403(b) plan with a previous employer, a Rollover IRA allows you to transfer those assets into a Fidelity account without incurring immediate taxes or early withdrawal penalties. This consolidation often provides more investment choices and lower administrative costs.
Prerequisites for Account Opening
To open an account efficiently, you should gather the necessary information before starting the online application. Fidelity, like all financial institutions, is required by federal regulations (including the USA PATRIOT Act) to verify the identity of every account holder to prevent fraud and money laundering.
- Personal Identification: You will need a valid government-issued photo ID, such as a U.S. driver’s license or passport.
- Social Security Information: Your Social Security Number (SSN) or Individual Taxpayer Identification Number (ITIN) is mandatory for tax reporting purposes.
- Employment Details: Be prepared to provide the name and address of your employer. If you are retired or unemployed, you can provide that status, but you must still provide the necessary personal identifiers.
- Funding Source: While you can open an account with a $0 minimum balance, most users choose to link a bank account immediately to facilitate transfers. You will need your bank’s routing number and your personal account number.
Step-by-Step Enrollment Process
The digital workflow at Fidelity is designed to guide you through the process in under ten minutes, provided you have your documentation ready.
- Navigate to the Official Portal: Go to the Fidelity Investments website and locate the "Open an Account" button, typically found in the main navigation menu.
- Select Your Account Type: You will be prompted to choose from the available options: Traditional, Roth, or Rollover. If you are unsure, Fidelity provides a brief "Help Me Choose" tool that asks about your current tax situation and retirement timeline.
- Enter Personal Data: Input your legal name, residential address, phone number, and email. Ensure this information matches your tax filings exactly to avoid verification delays.
- Disclosures and Regulatory Review: Carefully read the account disclosures. This section includes details on the Customer Agreement, privacy policies, and the nature of market risks associated with investing.
- Funding the Account: You can fund the account via Electronic Funds Transfer (EFT) from a linked bank account, a direct wire transfer, or by initiating a transfer of assets from another financial institution.
- Investment Selection: Opening the account is only the first step. Once the account is open, you must log in to the dashboard to select the specific securities (stocks, bonds, ETFs, or mutual funds) you wish to hold within the IRA. If you prefer a hands-free approach, Fidelity offers managed accounts, such as Fidelity Go, which automate asset allocation based on your risk profile.
Comparative Overview of IRA Types
The table below summarizes the core operational differences between the most common IRA structures to assist in your decision-making.
| Feature | Traditional IRA | Roth IRA |
|---|---|---|
| Tax Treatment | Tax-deductible contributions | After-tax contributions |
| Withdrawal Taxes | Taxed as ordinary income | Tax-free (qualified) |
| Required Minimum Distributions (RMDs) | Yes (starting at age 73) | None during owner's lifetime |
| Income Limits for Contributions | None (but limits apply for deduction) | Yes (based on MAGI) |
| Best For | Lowering current year tax burden | Tax-free growth for future years |
Common Pitfalls and Troubleshooting
Even with a streamlined digital process, users occasionally encounter hurdles. Understanding these common issues can save you significant time.
Verification Failures: If your identity cannot be verified electronically, Fidelity may require you to upload a digital copy of your driver's license or utility bill. This is a security safeguard and is standard practice.
Contribution Limits: Be mindful of the annual IRS contribution limits. For 2026, the combined total you can contribute to all your traditional and Roth IRAs is subject to specific caps. If you over-contribute, you will be subject to excise taxes by the IRS. It is advisable to monitor your contributions through the Fidelity account dashboard to ensure you remain within legal limits.
Missing Investment Selection: A common mistake for new investors is opening the IRA but failing to "invest" the cash. Simply depositing money into an IRA account does not put that money to work. You must select specific funds or stocks within the Fidelity platform to begin earning returns. If you are hesitant, consider researching Fidelity’s "index funds," which are frequently cited for their low expense ratios.
Frequently Asked Questions
Can I open an IRA for a non-working spouse? Yes, a "spousal IRA" allows a working spouse to contribute to an IRA in the name of a non-working spouse, provided that the couple files a joint federal income tax return and the combined contributions do not exceed the annual limits.
Does Fidelity charge a monthly fee for holding an IRA? Fidelity generally does not charge account maintenance fees for individual retail brokerage accounts or IRAs. However, individual investments held within the IRA, such as certain mutual funds or ETFs, may have their own internal expense ratios or management fees.
How long does it take for a transfer from another bank to clear? Electronic funds transfers (EFT) typically take 1 to 3 business days to clear. During this period, the funds may appear as "pending" in your Fidelity account, and you may be restricted from trading with that specific capital until the transfer is finalized.
Can I hold individual stocks in a Fidelity IRA? Yes, once you have opened your IRA, you can trade individual stocks, bonds, and a wide range of exchange-traded funds (ETFs) within the account. You are not limited to pre-packaged funds.
What happens if I change my mind about the account type? If you open the wrong type of IRA, it is generally easier to correct it immediately by contacting Fidelity’s customer service. Depending on the stage of the account, they can often facilitate a recharacterization or help you open a new account and close the incorrect one.
Next Steps and Recommendations
After you have successfully opened your IRA with Fidelity, your immediate next task should be to set up an automatic investment plan. By linking your bank account and scheduling monthly contributions, you benefit from "dollar-cost averaging," which mitigates the risk of timing the market. Ensure your beneficiary information is updated in the "Profile" section of your account to ensure your assets are distributed according to your wishes. Finally, regularly review your asset allocation—at least annually—to ensure that your investment risk remains aligned with your retirement timeline.
Disclaimer: This article is for informational purposes only and does not constitute financial, legal, or tax advice. Investing involves risk, including the loss of principal. Consult with a qualified tax professional or financial advisor regarding your specific situation before making major financial decisions.
Image Gallery
Select an image to open it in a new tab.
Zara El-Hashem
Sociocultural Dynamics and Academics Writer
