
A life insurance policy lender trust is generally a good option for high-net-worth individuals, business owners, and estate planners seeking to acquire substantial permanent life insurance without liquidating wealth-generating assets. By combining trust protection with premium financing or lender-backed collateral structures, this financial strategy allows borrowers to minimize out-of-pocket costs, optimize estate taxes, and preserve liquidity. However, it carries significant risks related to interest rate fluctuations, policy underperformance, and legal compliance.
Understanding Life Insurance Policy Lender Trusts
A life insurance policy lender trust—often structured in conjunction with an Irrevocable Life Insurance Trust (ILIT) and a commercial or private lending facility—is a specialized estate and financial strategy. In this arrangement, a trust acts as the applicant, owner, and beneficiary of a permanent life insurance policy, while a third-party lender (such as a commercial bank, private wealth institution, or institutional lender) provides financing to pay the policy’s annual premiums.
Alternatively, in some private financing contexts, a lender trust is established by a creditor or lending entity to hold a security interest in a borrower's life insurance policy as collateral for a private loan.
To evaluate whether this strategy aligns with your long-term goals, it is essential to understand the core components of the arrangement:
The Grantor (Insured): The individual whose life is insured by the policy. The grantor establishes the trust and transfers assets or collateral to satisfy lender equity requirements.
The Trust Entity: An irrevocable trust established under state law to hold ownership of the life insurance policy. Using an irrevocable trust ensures that policy proceeds remain outside the insured’s gross estate for federal estate tax purposes under Internal Revenue Code (IRC) Section 2042.
The Independent Trustee: A fiduciary (often an institutional trust company or independent attorney) who manages trust assets, executes loan documents, and oversees policy payments to prevent the grantor from retaining "incidents of ownership."
The Lender: A financial institution or private lending entity that provides the loan capital needed to fund policy premiums, securing the loan with the policy’s cash surrender value, death benefit, or outside collateral provided by the grantor.
Third-Party Lender: Funds premiums for the Permanent Life Insurance Policy and holds a collateral/security interest in the Irrevocable Policy Lender Trust.
Permanent Life Insurance Policy: Owned and held by the Irrevocable Policy Lender Trust.
Irrevocable Policy Lender Trust:
- Managed by Independent Trustee.
- Keeps Death Benefit outside Insured's Gross Estate.
- Provides Death Benefit to Trust Beneficiaries.
Grantor / Insured (Borrower): Establishes the trust and transfers outside collateral to the Irrevocable Policy Lender Trust.
Trust Beneficiaries (Family / Estate): Receives Death Benefit from the Irrevocable Policy Lender Trust.
When Is a Life Insurance Policy Lender Trust a Good Option?
A policy lender trust is not a general-market financial product; it is a sophisticated wealth preservation strategy tailored for specific financial profiles and estate objectives.
1. High-Net-Worth Estate Tax Liquidity
For individuals facing potential federal estate tax liabilities (or state-level estate and inheritance taxes), purchasing high-face-value permanent life insurance (often $5 million to $50 million+) provides liquidity to pay estate taxes without forcing the fire-sale of illiquid assets like real estate, closely held businesses, or private equity. Funding multi-million-dollar annual premiums directly out of pocket, however, can trigger significant federal gift taxes under IRC Section 2501. A lender trust minimizes taxable annual gifts by leveraging borrowed money to pay premiums.
2. Capital Retention and Opportunity Cost Optimization
Affluent investors often achieve annual internal rates of return (IRR) on their core business assets or investment portfolios that exceed the borrowing interest rates charged by premium finance lenders. Using a lender trust enables the grantor to retain capital within higher-yielding investments rather than tying up cash inside a life insurance policy's initial cash value accumulation phase.
3. Securing Large Private or Commercial Loans
In corporate succession planning, partner buyouts, or private debt transactions, lenders frequently require key person life insurance or personal guarantees secured by policy proceeds. Placing the policy within a structured lender trust provides the lender with legal security via a formal collateral assignment while preserving the remaining estate planning benefits for the borrower's heirs.
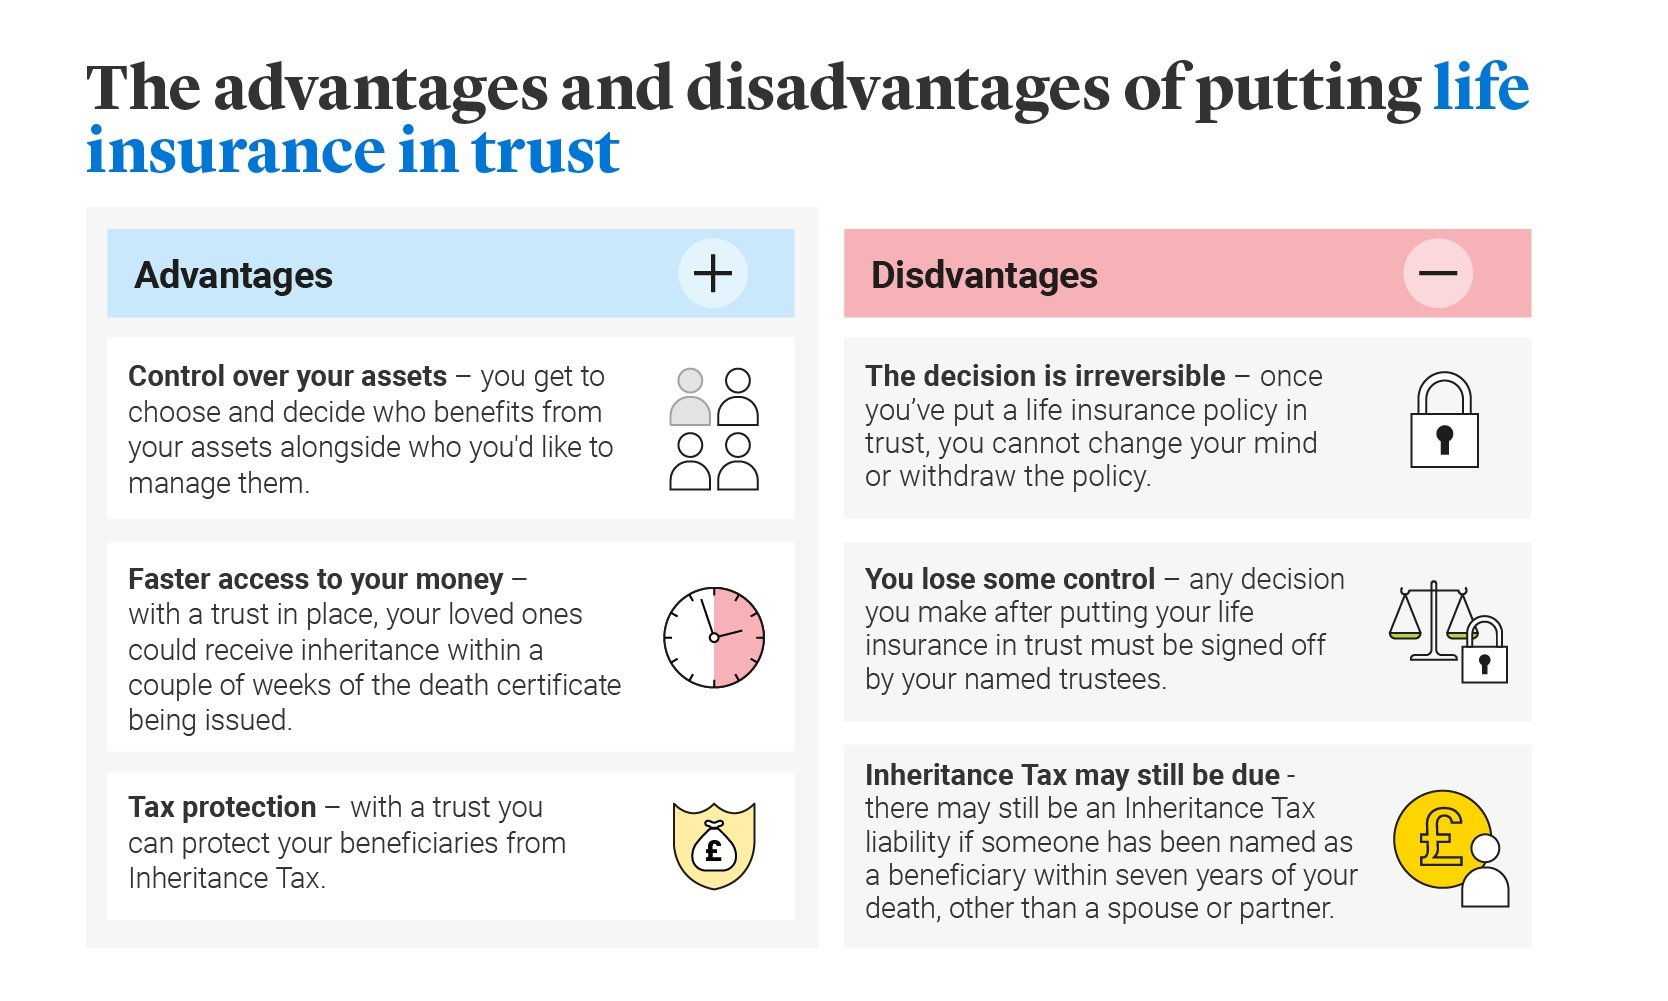
Key Advantages of Policy Lender Trusts
When properly structured and executed, a life insurance policy lender trust offers several financial, tax, and legal advantages.
Tax Efficiency and Estate Tax Exclusion
By establishing an irrevocable trust to hold the policy from inception, the policy’s death benefit is excluded from the insured’s taxable estate. Furthermore, because the lender funds the vast majority of the annual policy premiums, the grantor only needs to gift enough cash to the trust to cover interest payments or satisfy collateral shortfall requirements. These smaller transfers often fall within the annual gift tax exclusion or consume a fraction of the grantor's lifetime gift and estate tax exemption.
Asset Protection Benefits
Assets held within a properly drafted irrevocable trust generally enjoy strong protection from personal creditors, business lawsuits, and civil judgments against the grantor. Because the trust—not the insured individual—owns the policy, judgment creditors of the grantor typically cannot attach liens to the policy's cash value or force a policy surrender.
Preservation of Cash Flow
Directly purchasing a massive cash-value life insurance policy requires substantial upfront liquidity during the first 5 to 10 policy years. Financing the premiums through a lender trust reduces cash flow demands, allowing business owners and real estate investors to maintain working capital for core operational needs.
Risks, Drawbacks, and Potential Pitfalls
Despite its benefits, a life insurance policy lender trust carries significant financial and structural risks. Failure to manage these risks can lead to policy lapse, unexpected tax liabilities, or loss of outside collateral.
1. Interest Rate Volatility
Most premium financing loan agreements utilize variable interest rates tied to benchmark indices such as the Secured Overnight Financing Rate (SOFR). If interest rates rise rapidly, the cost of servicing the loan increases significantly. If the interest expense outpaces the growth rate of the policy’s cash value, the grantor must post additional cash or collateral to prevent a loan default.
2. Policy Underperformance
Permanent life insurance strategies used in lender trusts—such as Indexed Universal Life (IUL) or Variable Universal Life (VUL)—rely on market-linked returns or crediting rates to build cash value. If policy crediting rates underperform projections due to market downturns or lowered caps, the policy’s cash value growth will fail to keep pace with the accumulating debt balance.
3. Collateral Calls and Shortfalls
Lenders require the loan balance to be fully secured at all times. In the early years of a permanent life insurance policy, surrender charges reduce the net cash surrender value, creating a gap between the total loan amount advanced by the bank and the available policy collateral. The grantor must pledge outside collateral (such as letters of credit, marketable securities, or real estate) to bridge this gap. If policy performance drags or interest rates rise, the required outside collateral can scale rapidly.
4. IRC Section 2042 "Incidents of Ownership" Violations
For the death benefit to remain tax-free and outside the gross estate, the insured individual must hold no "incidents of ownership" in the policy under IRC Section 2042. If the grantor serves as trustee, retains the power to change beneficiaries, or holds direct contractual control over the loan-collateral assignment, the Internal Revenue Service (IRS) may include the entire death benefit in the insured’s gross estate.
Comparing Policy Lender Trusts to Alternative Strategies
To evaluate whether a lender trust is the right mechanism, compare it against alternative methods of acquiring life insurance and securing policy loans.
| Strategy Feature | Life Insurance Policy Lender Trust | Traditional ILIT (Self-Funded) | Direct Policy Loan (From Insurer) | Direct Bank Collateral Assignment |
|---|---|---|---|---|
| Primary Target Audience | High-Net-Worth ($10M+ net worth) | Individuals with Estate Tax Exposure | Existing Policyholders Needing Cash | Small Business Borrowers / Guarantors |
| Initial Out-of-Pocket Cost | Low to Moderate (Interest/Collateral) | High (Full Premium Payments) | None upfront (Uses existing equity) | Low (Uses existing policy) |
| Estate Tax Exclusion | Yes (If structured correctly) | Yes (If structured correctly) | No (Policy owned individually) | No (Typically owned individually) |
| Interest Rate Exposure | High (Tied to SOFR / Bank rates) | None (No loan involved) | Moderate (Fixed/Variable policy loan rate) | Moderate to High (Commercial loan rates) |
| Collateral Risk | High (Requires outside asset pledge) | None | Low (Secured solely by cash value) | High (Tied to business/personal assets) |
| Complexity & Legal Fees | High ($10,000 – $30,000+ setup) | Moderate ($3,000 – $10,000 setup) | Very Low (Standard insurer form) | Low to Moderate |
Step-by-Step Setup and Execution Process
Implementing a life insurance policy lender trust requires coordination between an estate planning attorney, an independent insurance advisor, a wealth manager, and a lender.
- Step 1: Legal & Financial Feasibility Assessment
- Step 2: Underwriting & Policy Selection
- Step 3: Drafting & Execution of the Irrevocable Trust
- Step 4: Loan Negotiation & Collateral Assignment
- Step 5: Ongoing Annual Monitoring & Stress Testing
Step 1: Legal and Financial Feasibility Assessment
Before drafting documents, perform a comprehensive stress-test analysis. Financial advisors must model the arrangement under adverse economic scenarios—including sustained high interest rates, zero-crediting policy years, and early death—to confirm that the grantor has sufficient liquid assets to meet potential collateral calls.
Step 2: Underwriting and Policy Selection
The proposed insured must undergo medical and financial underwriting with an institutional life insurance carrier. Permanent life insurance products with strong cash-value guarantees or high historical crediting stability—such as Indexed Universal Life or Whole Life policies—are typically selected.
Step 3: Drafting and Execution of the Irrevocable Trust
An experienced estate planning attorney drafts an irrevocable trust structure. The trust agreement must explicitly grant the trustee the authority to borrow funds, pledge policy assets as collateral, and pay loan interest. An independent institutional or professional trustee should be appointed to prevent any IRC Section 2042 conflicts.
Step 4: Loan Negotiation and Collateral Assignment
The trustee applies for a commercial premium finance facility with an approved lender. Once approved, the lender advances premium payments directly to the insurance company. In exchange, the trustee executes a collateral assignment agreement, giving the lender a primary security interest in the policy's cash value and death benefit equal to the outstanding loan balance.
Step 5: Ongoing Annual Monitoring and Stress Testing
The trust arrangement requires annual administrative review:
- The trustee verifies premium payments and loan interest calculations.
- The grantor transfers gift funds to the trust (utilizing Crummey powers where applicable) to pay loan interest.
- The financial team reviews annual carrier policy illustrations against bank loan balances to identify collateral gaps early.
Critical Legal and Tax Considerations
Split-Dollar Regulations (Treasury Regulations Section 1.7872-15)
If a lender trust strategy involves private split-dollar arrangements between a grantor’s family trust and a business entity, strict compliance with Treasury Regulations under 26 CFR § 1.7872-15 is required. The IRS governs whether the financing is treated as a loan regime or an economic benefit regime. Impugned or below-market interest rates can lead to unexpected income tax or gift tax recharacterizations.
Grantor Trust Status (IRC Sections 671–679)
Many lender trusts are structured intentionally as intentionally defective grantor trusts (IDGTs) for income tax purposes under IRC Sections 671 through 679. This allows the grantor to pay the trust’s income taxes without treating those payments as taxable gifts to the trust beneficiaries, enabling trust assets to grow unencumbered by income tax burdens.
Practical Recommendations: Is It Right for You?
A life insurance policy lender trust is an excellent option if you meet the following criteria:
- High Net Worth: You possess an estate valued significantly above federal and state estate tax exemption thresholds.
- Illiquid Asset Base: Your wealth is concentrated in high-performing assets (e.g., private companies, real estate holdings) that you do not wish to liquidate to pay life insurance premiums or estate taxes.
- Risk Tolerance for Leverage: You understand variable interest rates and are prepared to handle potential collateral calls during economic downturns.
- Access to Professional Advisors: You have a dedicated legal, tax, and wealth management team capable of maintaining ongoing compliance.
Conversely, a policy lender trust is not recommended if:
- Your primary goal is simple personal protection or basic income replacement.
- You lack excess unencumbered assets (such as marketable securities) to post as outside collateral.
- You are unwilling to pay high legal, administrative, and underwriting fees to establish and maintain the trust structure.
Frequently Asked Questions
What happens to the loan when the insured dies?
Upon the death of the insured, the insurance company pays the policy proceeds to the trust. Pursuant to the collateral assignment agreement, the lender receives the portion of the death benefit required to pay off the remaining loan principal and accrued interest. The remaining balance of the death benefit is distributed tax-free to the designated trust beneficiaries.
Can the bank take my personal home or business assets if the policy underperforms?
The bank can only access outside assets that were explicitly pledged as collateral under the loan agreement. If you pledged personal securities, real estate, or letters of credit to satisfy collateral shortfall requirements, the lender may seize those specific assets if the trust defaults on its loan or fails to meet a collateral call.
Can I serve as the trustee of my own policy lender trust?
It is strongly advised that you do not act as the trustee of a policy lender trust holding life insurance on your life. Serving as trustee creates "incidents of ownership" under IRC Section 2042, which causes the entire life insurance death benefit to be included in your taxable gross estate, defeating a core tax objective of the trust.
What is the exit strategy for a policy lender trust loan?
Common exit strategies include:
- Policy Cash Value Payoff: Surrendering a portion of accumulated cash value in policy years 10 to 15+ to pay off the bank loan balance.
- Grantor Liquidation Event: The grantor uses proceeds from a business sale, real estate transaction, or inheritance to pay off the trust debt.
- Death Benefit Proceeds: Maintaining the loan structure until death, at which point the policy proceeds clear the debt balance.
Is premium financing through a lender trust considered tax evasion?
No. Premium financing and irrevocable life insurance trusts are legitimate, legally recognized financial strategies grounded in established tax codes, including IRC Sections 2042, 2501, and Treasury Regulation 1.7872-15. However, strict adherence to legal formalities, market interest rates, and proper trust management is required to maintain compliance.
Summary Checklist for Decision Making
Before committing to a life insurance policy lender trust, complete this final compliance check with your advisors:
- Net Worth Check: Is your net worth sufficient to justify the administrative overhead and financial leverage involved?
- Stress Testing: Has your advisor modeled a scenario where interest rates increase by 300+ basis points while policy crediting drops to minimum guaranteed levels?
- Collateral Liquidity: Do you have sufficient unencumbered liquid assets to pledge for initial and ongoing collateral gaps?
- Independent Trustee: Have you selected a qualified third-party trustee to satisfy IRC Section 2042 rules?
- Formal Legal Opinion: Has an independent tax attorney reviewed the trust agreement and loan collateral documentation?
Disclaimer: This article is for informational and educational purposes only and does not constitute formal legal, tax, or financial advice. Estate planning and premium financing strategies involve complex legal regulations and market risks. Always consult a qualified estate planning attorney and licensed financial advisor before entering into any leveraged life insurance transaction.
EDITORIAL CATEGORY METADATA:
Image Gallery
Select an image to open it in a new tab.

Mateo Castillo
Decentralized Finance and E-Payments Strategist
