A claims management system improves handling by centralizing data, automating repetitive workflows, and enforcing standardized evaluation protocols. These platforms bridge the gap between policyholders and insurers, replacing fragmented, manual processes with real-time digital tracking, predictive analytics for fraud detection, and automated communication chains that accelerate the settlement lifecycle.
The Role of Technology in Modern Claims Processing
The insurance landscape has transitioned from paper-heavy, siloed workflows to integrated digital ecosystems. A Claims Management System (CMS) acts as the central nervous system for an insurance carrier or a Third-Party Administrator (TPA). At its core, the system serves as a repository for policy data, claimant information, incident reports, and legal documentation. By digitizing the intake process—whether through web-based portals or mobile application interfaces—the system ensures that data integrity is maintained from the moment a loss is reported.
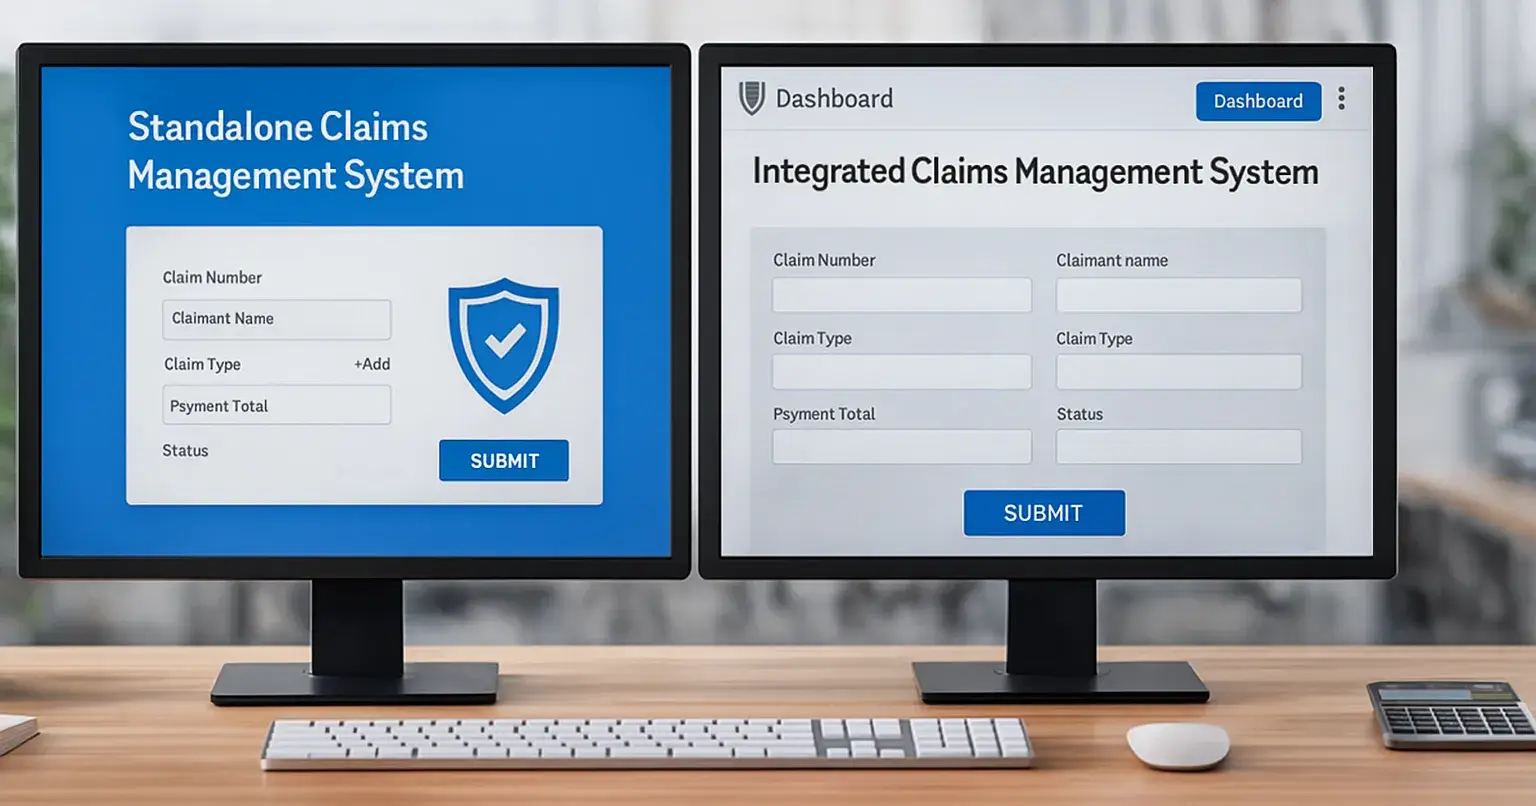
Without a dedicated CMS, insurance handling relies on manual data entry across disconnected spreadsheets and email threads. This fragmentation inevitably leads to human error, missed deadlines, and poor communication with stakeholders. A robust system mitigates these risks by providing a single source of truth that is accessible to adjusters, supervisors, and legal counsel simultaneously, regardless of their geographical location.
Core Mechanisms of Operational Improvement
The efficacy of a claims management system is driven by three primary operational pillars: automation, data centralization, and analytical insight.
Automation and Workflow Optimization
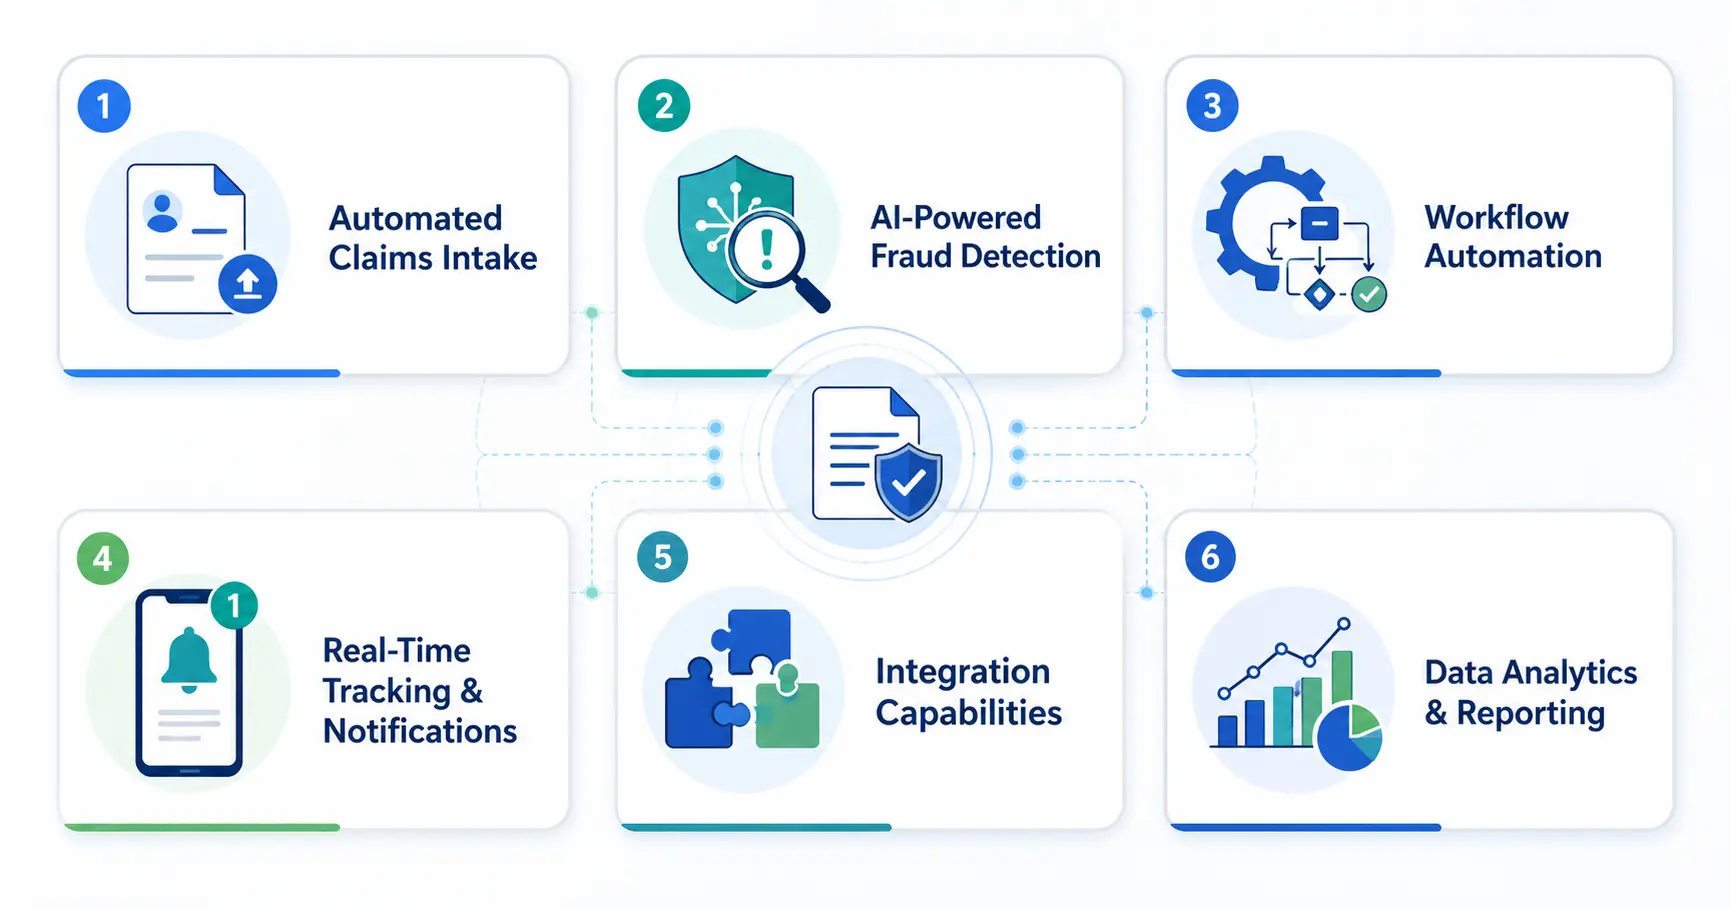
Manual tasks, such as assigning a claim to a specific adjuster based on their specialty or calculating initial reserve requirements, are prone to inefficiency. Modern systems use algorithmic routing to ensure that a claim reaches the right professional based on technical expertise, availability, and workload capacity. Furthermore, automated alerts and reminders prevent claims from stalling, ensuring that adjusters meet statutory notification deadlines and internal service level agreements (SLAs).
Centralized Data Management
The system captures every interaction—emails, phone logs, adjuster notes, and external file uploads—within a chronological timeline. This level of traceability is critical for regulatory compliance and audit readiness. When a file is audited, the CMS allows investigators to review the entire lifecycle of the claim without searching for disparate files. This creates a transparent history that protects both the insurer and the policyholder by providing clear evidence of how decisions were reached.
Analytical Insights and Fraud Detection
Sophisticated CMS platforms integrate predictive analytics to identify patterns indicative of insurance fraud. By benchmarking new claims against historical data, the system can flag inconsistencies—such as duplicate invoices or suspicious provider patterns—for manual investigation. This proactive approach saves carriers millions in indemnity payments while ensuring that legitimate claims are prioritized for rapid resolution.
Comparing Traditional vs. Automated Claims Handling
To understand the tangible impact of implementing a CMS, one must analyze the difference in processing outcomes between legacy methods and modern system-enabled environments.
| Feature | Legacy Manual Handling | Integrated CMS Handling |
|---|---|---|
| Data Intake | Paper/Manual Entry | Automated Portals/API |
| Routing | Manual Assignment | Rule-Based Automated Routing |
| Fraud Detection | Reactive/Heuristic | Predictive/Pattern Analysis |
| Communication | Phone/Mail (Unstructured) | Integrated Messaging/Real-time Updates |
| Audit Compliance | Difficult/Time-Consuming | Automated/Always-on Reporting |
| Settlement Speed | High Variance/Slow | Standardized/High Velocity |
Improving the Policyholder Experience
While the primary goal of a CMS is operational efficiency for the insurer, the benefits to the policyholder are equally significant. A frustrated customer reporting a loss needs clarity, speed, and responsiveness. When an insurer utilizes a CMS, policyholders benefit from a self-service dashboard that allows them to track the status of their claim in real time.
Transparency reduces the "information gap" that often leads to customer anxiety and frequent, time-consuming status inquiries to the call center. By allowing claimants to upload photos, police reports, and receipts directly through a secure portal, the system also reduces the administrative burden on the claimant, shortening the time between incident and payout.
Technical Requirements and Integration Challenges
Implementing a CMS is not merely a software procurement task; it is an organizational transformation. The success of the system depends on its integration with existing core banking, policy administration, and CRM (Customer Relationship Management) platforms.
- Legacy Integration: Most insurers operate on aging mainframe systems. A modern CMS must use robust APIs (Application Programming Interfaces) to pull policy coverage details and financial data without forcing a total system overhaul.
- Data Cleansing: Migrating records from older databases requires rigorous data cleaning. If the historical data is incomplete or formatted inconsistently, the automation features of the new CMS will perform poorly.
- Change Management: Even the best software will fail if adjusters and managers do not adopt it. Training programs must emphasize not just the buttons and features of the new system, but the objective benefit—such as reduced administrative load and improved accuracy—to drive internal buy-in.
Addressing Common Implementation Mistakes
A frequent error during implementation is the "feature-first" approach, where an organization attempts to replicate its legacy manual process exactly within the new digital system. This often results in "digitized chaos." Instead, organizations should use the implementation as an opportunity to audit and lean out their processes before encoding them into the software.
Another common mistake is neglecting the mobile-first requirements of the policyholder. In 2026, claimants expect to initiate and settle a claim entirely from their smartphones. If the CMS front-end is not fully responsive or lacks the ability to handle rich media (such as high-resolution video of property damage), the efficiency gains on the back end will be overshadowed by a negative user experience at the point of impact.
Legal, Financial, and Regulatory Considerations
Insurance handling is heavily governed by state and federal regulations (in the United States and similar jurisdictions globally). A CMS must be configured to adhere to these rules automatically. For example, some jurisdictions require insurers to send a written response to a claim within a specific number of days. A properly configured CMS will automatically trigger these notices, effectively shielding the insurer from regulatory fines and bad-faith litigation.
Financially, the system must maintain strict controls over reserve adjustments. If an adjuster increases a reserve beyond a certain threshold, the system should trigger a secondary approval workflow from a manager. This ensures that the company’s capital allocation is consistent with its risk appetite and liquidity requirements.
Frequently Asked Questions
How does a CMS reduce the time required to settle a claim? It reduces time by eliminating manual data hand-offs between departments. When data is captured digitally, it is immediately available to all authorized stakeholders. Automated rules also trigger the next step in the process the moment a condition is met (e.g., an invoice is uploaded), removing the downtime associated with waiting for a human to notice a task is ready.
Is cloud-based storage safe for sensitive insurance data? Yes, provided the vendor adheres to enterprise-grade security standards such as SOC 2 Type II compliance and AES-256 encryption. By 2026, top-tier CMS providers offer more robust security than most private on-premise servers due to continuous automated updates and dedicated security teams.
Can a CMS integrate with third-party loss adjusters? Modern systems are designed for an ecosystem approach. They allow for "guest" access or secure API integrations with third-party contractors and independent adjusters. This ensures that field reports are ingested into the main claim file immediately rather than sitting in an email inbox for days.
What is the cost structure of these systems? Most vendors operate on a Software-as-a-Service (SaaS) model, charging per user or per claim processed. The initial investment includes licensing fees, integration setup, and staff training. However, the ROI is usually realized through reduced loss adjustment expenses (LAE) and improved fraud recovery.
Do these systems require a dedicated IT staff? While a system administrator is recommended, most modern SaaS CMS platforms are designed for configuration rather than heavy coding. This allows business analysts within the claims department to adjust workflows without relying on a large IT development team for every minor change.
Recommendations for Next Actions
For organizations looking to optimize their claims handling, the first step is to conduct an internal process audit. Map out the current claim journey from the first notice of loss to the final settlement, noting every point where data is manually re-entered or where communication slows down. Once these bottlenecks are identified, define the specific technical requirements for a CMS that addresses those precise gaps.
If your organization is already using a CMS, perform an annual optimization review. Check if your automated rules are still aligned with current policy limits and regulatory statutes. Often, organizations underutilize their systems by keeping them in a "default" state; investing time in configuring advanced reporting and deep-learning fraud modules can unlock significant hidden value.
Image Gallery
Select an image to open it in a new tab.



Simon Caldwell
Enterprise Technology and Systems Editor
